
Semiconductor demand is increasingly being shaped by how much silicon each finished product contains. Unit growth across mature consumer categories has slowed, while AI infrastructure, electric vehicles, software-defined vehicles, industrial automation, and connected devices are increasing semiconductor content per system. For semiconductor companies and investors, the opportunity therefore lies in understanding where silicon intensity is rising and which component architectures are capturing the resulting value.
AI Infrastructure Is Redefining Silicon Content
The shift from conventional cloud computing to AI infrastructure has dramatically changed the semiconductor bill of materials. Traditional enterprise servers typically relied on a small number of CPUs, while AI systems require multiple high-performance accelerators, high-bandwidth memory, advanced packaging, and increasingly sophisticated power-management components.
A modern AI server rack can contain eight high-end AI accelerators, with silicon content reaching approximately $200,000 to $300,000 in the supplied estimates. HBM3e and HBM4 requirements add substantial memory value, while system DDR5 capacity also increases. At the power layer, delivering more than 1,000 amperes of clean, low-voltage current requires multiphase digital voltage regulators, smart power stages, and point-of-load converters.
Networking is another expanding layer of content. High-speed data movement between accelerators and across data centers is driving demand for optical DSPs, high-bandwidth Ethernet and InfiniBand switching silicon, and PCIe retimers.
EVs and Software-Defined Vehicles Are Increasing Automotive Content
Automotive electronics represent another structural growth pool because electrification changes the power architecture of the vehicle while software-defined designs increase computing requirements.
The transition toward 800V EV architectures is accelerating adoption of Silicon Carbide MOSFETs and other wide-bandgap power devices across traction inverters, onboard chargers, and high-voltage DC-DC converters. Power semiconductors represented 58.9% of the EV semiconductor device market in 2025 in the supplied research, reflecting the importance of energy conversion within electric drivetrains.
At the same time, software-defined vehicles are consolidating numerous distributed electronic control units into fewer high-performance zonal controllers connected to centralized compute platforms. Microcomponents and processors accounted for approximately 24% to 27% of automotive semiconductor demand in 2025–2026, supported by this architectural shift.
For companies evaluating these segments, a Semiconductor demand analysis needs to track how semiconductor content changes with vehicle architecture, powertrain type, ADAS capability, and computing consolidation. Aggregate vehicle shipments alone cannot capture these differences.
Industrial Automation Creates Multiple Silicon Growth Pools
Industrial automation is expanding semiconductor demand across several component categories simultaneously. Collaborative robots, autonomous mobile robots, machine-vision systems, and industrial IoT deployments require combinations of motion-control processors, motor-control devices, sensors, connectivity chips, and power-management components.
Robotic platforms increasingly incorporate edge processors capable of real-time object classification and path planning alongside magnetic rotary encoders and isolated gate drivers. Industrial IoT systems add MEMS pressure and vibration sensors, low-power wireless transceivers, and energy-harvesting power-management chips.
These applications can also support longer product cycles than consumer electronics. Industrial equipment may remain in service for many years, creating recurring demand for mature-node microcontrollers, communication chips, power semiconductors, and replacement components.
Consumer Devices Are Becoming More Compute-Intensive
Consumer electronics remain important, but their semiconductor opportunity is increasingly tied to architectural upgrades rather than simple shipment growth. AI-enabled PCs are introducing dedicated Neural Processing Units capable of more than 40 TOPS of int8 compute, alongside higher-density memory and increasingly capable power-management systems.
Smartphones are following a similar path. 5G-Advanced and Wi-Fi 7 increase the complexity of radio-frequency front ends, while advanced application processors, multi-camera image signal processors, and higher memory requirements raise semiconductor value per device. Gallium arsenide power amplifiers and bulk acoustic wave filters add further content to the RF subsystem.
The commercial significance of these shifts depends on which semiconductor categories capture the additional value. Higher device content does not automatically translate into attractive margins if the underlying component remains highly commoditized.
Nexdigm Application-Level Semiconductor Demand Framework
A useful Semiconductor demand analysis distinguishes between rising semiconductor content and economically attractive semiconductor content. AI accelerators, HBM, SiC power devices, automotive compute, and specialized sensors may experience different pricing, competitive, qualification, and capacity dynamics.
The evaluation therefore moves through five stages:
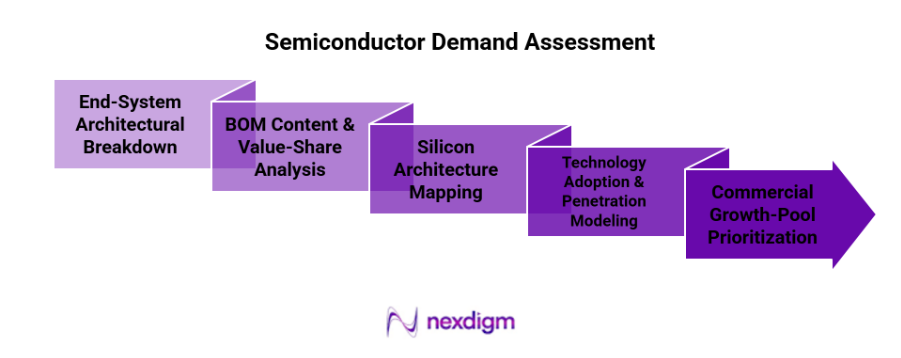
- End-System Architectural Breakdown: Deconstruct target systems into subsystem boards, processors, memory, power devices, sensors, and connectivity components.
- BOM Content & Value-Share Analysis: Calculate current and projected semiconductor dollar content per finished system and identify where value is shifting.
- Silicon Architecture Mapping: Map demand across leading-edge logic, mature-node MCUs, SiC/GaN power devices, HBM, DRAM, and other relevant technologies.
- Technology Adoption & Penetration Modeling: Model adoption curves for technologies such as SiC in 800V EV platforms, edge NPUs in industrial systems, and HBM in AI infrastructure.
- Commercial Growth-Pool Prioritization: Rank application segments according to growth, semiconductor value, ASP potential, competitive intensity, and margin defensibility.
Nexdigm’s approach can connect system-level demand with component-level opportunity by evaluating the applications where semiconductor content is expanding most rapidly. The analysis can help companies determine which end markets warrant capacity expansion, technology investment, portfolio development, or deeper customer engagement.
Nexdigm Case Study: Mapping India’s Semiconductor Growth Potential
Nexdigm conducted a semiconductor and memory technology market assessment for India, mapping chip design houses, OEMs, packaging units, localization policies, data-center capacity expansion, and fabless ecosystem constraints across Bengaluru, Hyderabad, Gujarat, and Assam.
The assessment estimated India’s semiconductor market at $3.83 billion in 2024 and projected it to reach $12.13 billion by 2030, representing a 21.2% CAGR. It also identified strategic joint-venture and investment priorities alongside ecosystem bottlenecks, demonstrating how market sizing can be connected to the application, infrastructure, and investment decisions shaping semiconductor growth.
To take the next step, simply visit our Request a Consultation page and share your requirements with us.
Harsh Mittal
+91-8422857704