
The semiconductor industry is one of the most globally distributed manufacturing systems, yet many of its critical inputs remain highly concentrated. A single chip can depend on design software from one geography, lithography equipment from another, specialty chemicals from a third, wafer fabrication in a fourth, and advanced packaging somewhere else. This creates efficiency at scale, but it also creates points where a localized disruption can propagate across the entire electronics value chain.
For semiconductor companies, electronics manufacturers, and investors, supply-chain resilience therefore requires visibility beyond direct suppliers. The relevant exposure often sits several tiers below the immediate vendor relationship.
Semiconductor Dependencies Are Distributed Across Specialized Hubs
Multiple direct chip vendors can mask deep vulnerabilities, as resilience depends on concentrated lower tiers rather than frontline supplier counts. The entire semiconductor ecosystem hinges on tightly clustered regional monopolies:
- Design & Upstream IP: Concentrated in the United States (EDA software, processor architectures).
- Equipment & Precision Optics: Anchored across the Netherlands, Japan, and Germany (notably lithography).
- Raw Materials & Chemicals: Dominated by Japan, Germany, and Taiwan for wafers and specialty inputs.
- Fabrication & Memory: Taiwan leads advanced logic, while South Korea controls high-bandwidth memory (HBM).
- Packaging & Testing (OSAT): Clustered heavily across Taiwan, Mainland China, and Southeast Asia.
Equipment Creates Some of the Hardest-to-Replace Dependencies
- Critical Equipment Choke Points
Fabrication tools like EUV lithography, etching, deposition, and metrology represent severe structural bottlenecks. Replacing these specialized systems requires proprietary IP, niche manufacturing capabilities, and extensive customer validation, creating multi-year substitution timelines. - Material & Chemical Vulnerabilities
Upstream supplies are equally concentrated. A handful of producers control the global silicon wafer supply, Japanese firms dominate advanced photoresists and coatings, and noble and specialty gases (neon, krypton, xenon, $NF_3$) remain acutely vulnerable to regional and geopolitical disruptions.
For companies conducting a Semiconductor supply chain market analysis, these dependencies need to be assessed at the component and process level. Market share alone does not indicate risk. The more important question is how quickly an alternative supplier could be qualified and production transferred.
Packaging Can Constrain Production Even When Wafers Are Available
Advanced packaging has become a strategic bottleneck as semiconductor architectures move toward multi-die designs. AI accelerators and other high-performance processors increasingly combine logic dies, HBM stacks, and high-speed interconnects within sophisticated 2.5D and 3D packages.
This creates dependencies on advanced substrates, silicon interposers, and Through-Silicon Via technologies. Ajinomoto Build-up Film, for example, is an important substrate material for high-density packaging, while shortages in packaging capacity can constrain finished processor shipments even when sufficient front-end wafer capacity exists.
The geographic concentration of outsourced assembly and testing adds another vulnerability. More than half of global outsourced packaging and testing capacity is concentrated in Taiwan and Mainland China in the supplied research, leaving downstream production exposed to regional disruption.
Exposure Depends on More Than Supplier Concentration
Not every single-source dependency represents the same level of commercial risk. A component may have one supplier but be easily replaced if a qualified alternative exists. Conversely, a component with several nominal suppliers can represent a major risk if all depend on the same upstream material or manufacturing geography.
A practical vulnerability assessment should examine five dimensions: supplier concentration, geopolitical exposure, substitutability, inventory coverage, and re-qualification time. Automotive, aerospace, healthcare, and other regulated industries face particularly high exposure when replacement components require lengthy validation before production can resume.
The objective is to identify the components where a disruption would create the greatest combination of operational downtime, financial impact, and recovery difficulty.
Building a More Resilient Semiconductor Supply Chain
Resilience requires mapping dependencies beyond the Tier-1 supplier relationship. Companies need visibility into wafer fabs, silicon suppliers, packaging houses, specialty chemical manufacturers, and critical equipment providers.
The most exposed components can then be prioritized for dual sourcing, second-fab qualification, strategic inventory buffers, or geographic diversification. Scenario modelling can further estimate the financial consequences of disruptions such as geopolitical restrictions, natural disasters, contamination events, or prolonged utility failures.
This approach also changes the way inventory decisions are made. Holding additional stock is expensive, but the economics can be justified when a replacement requires years of capacity development or months of customer re-qualification. The appropriate buffer therefore depends on recovery time and business criticality rather than a uniform inventory policy.
Nexdigm Supply-Chain Risk Mitigation Framework
A structured resilience program can evaluate semiconductor dependencies through six decision stages:
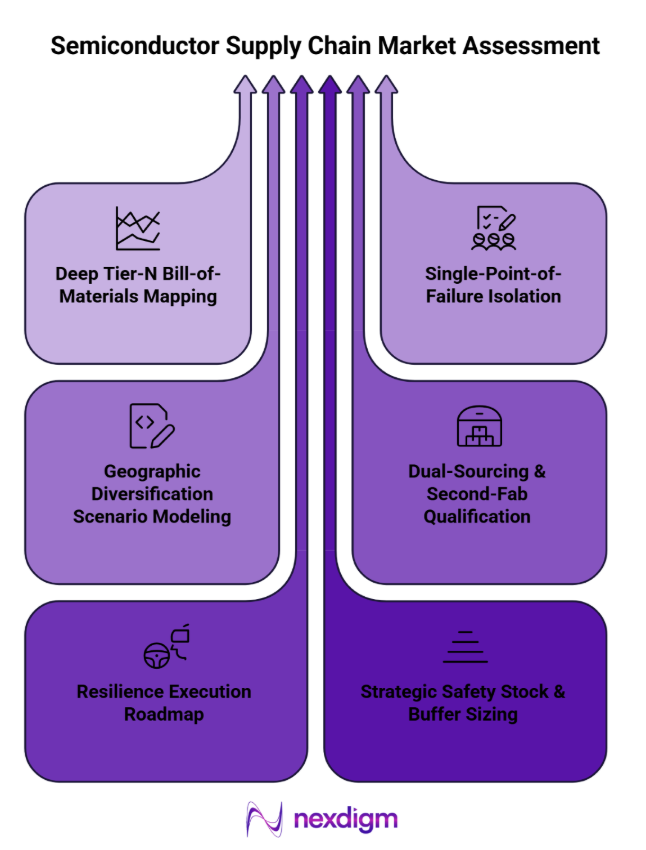
- Deep Tier-N Bill-of-Materials Mapping: Trace critical components beyond Tier-1 suppliers to wafer fabs, material providers, and packaging houses.
- Single-Point-of-Failure Isolation: Identify dependencies on single-source manufacturers, proprietary technologies, or concentrated geographies.
- Dual-Sourcing & Second-Fab Qualification: Evaluate alternative suppliers and qualify secondary manufacturing sources for critical components.
- Strategic Safety Stock & Buffer Sizing: Set inventory levels according to component criticality, lead times, and replacement difficulty.
- Geographic Diversification Scenario Modeling: Model operational and financial consequences under geopolitical and natural-disaster disruption scenarios.
- Resilience Execution Roadmap: Prioritize supply continuity agreements, localized distribution capacity, and recurring supplier business-continuity audits.
Nexdigm Case Study: Semiconductor Ecosystem Assessment in India
Nexdigm’s semiconductor and memory technology market assessment for India mapped chip design houses, OEMs, packaging units, localization policies, data-center capacity expansion, and fabless ecosystem constraints across Bengaluru, Hyderabad, Gujarat, and Assam. The assessment estimated India’s semiconductor market at $3.83 billion in 2024 and projected it to reach $12.13 billion by 2030, representing a 21.2% CAGR. It also identified strategic joint-venture and investment priorities alongside ecosystem bottlenecks.
The case illustrates how mapping the semiconductor ecosystem can connect market growth with the infrastructure, supplier depth, and investment conditions required to build a more resilient domestic value chain.
To take the next step, simply visit our Request a Consultation page and share your requirements with us.
Harsh Mittal
+91-8422857704