
 Download PDF
Market Overview
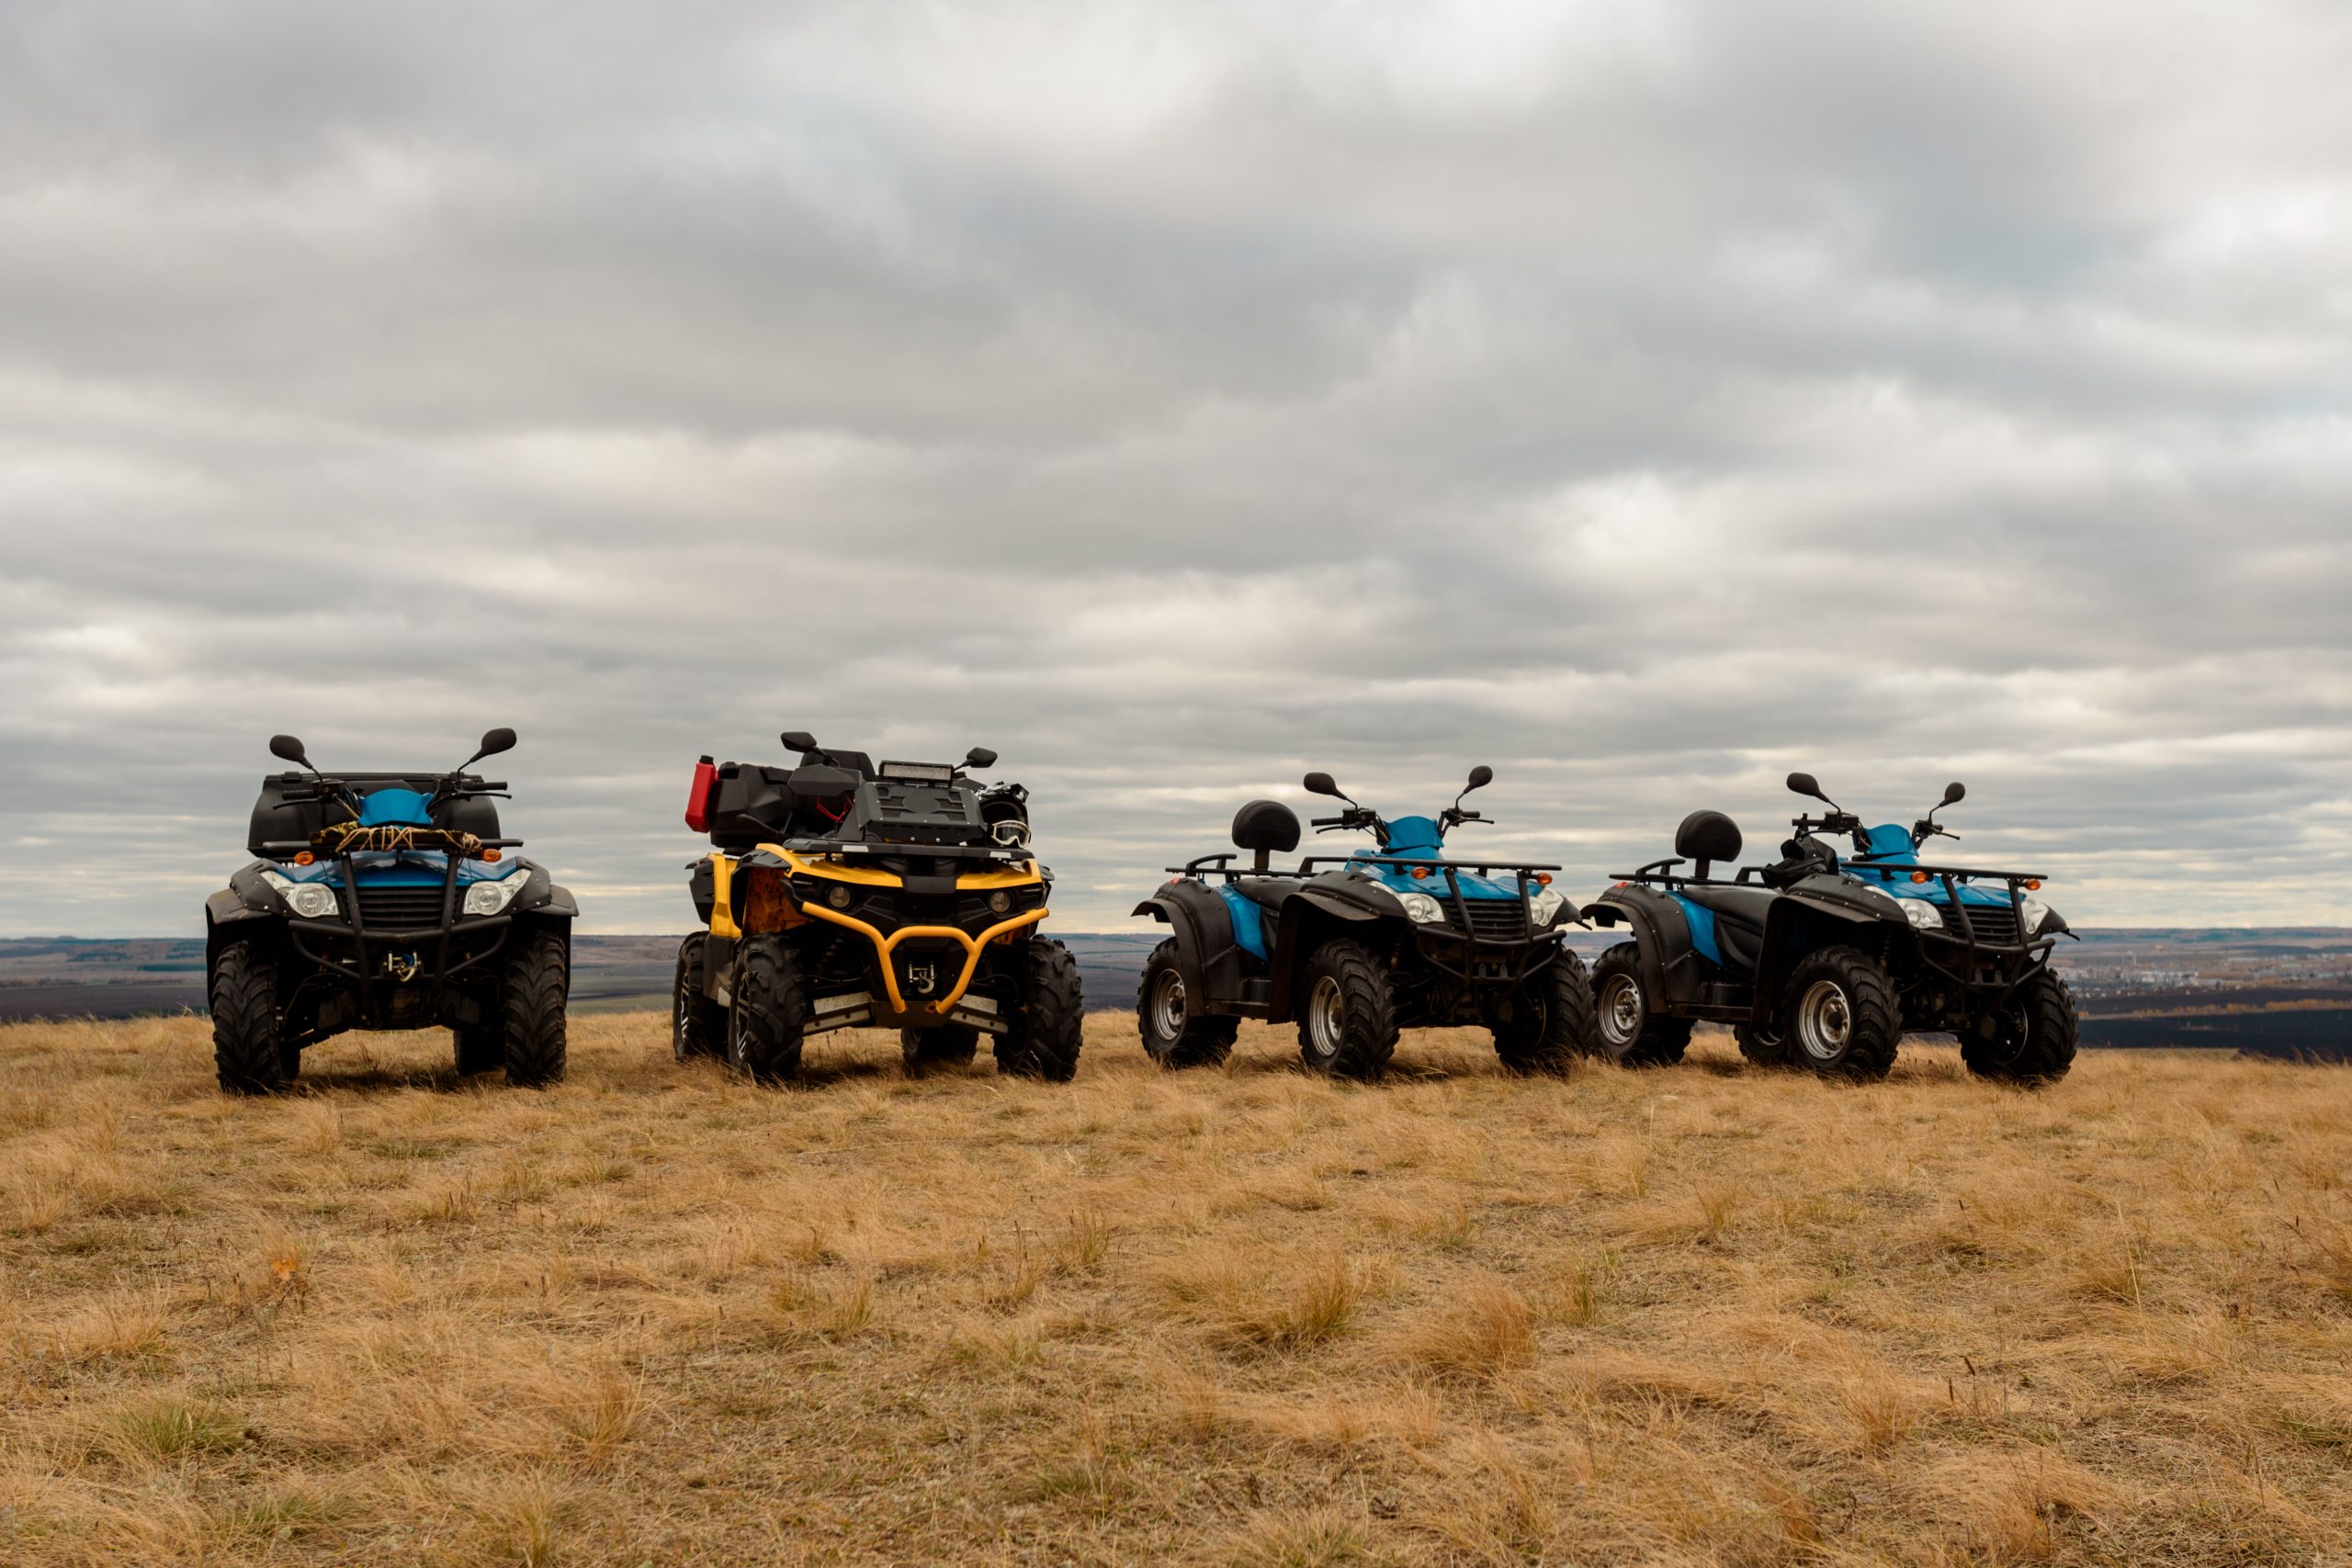
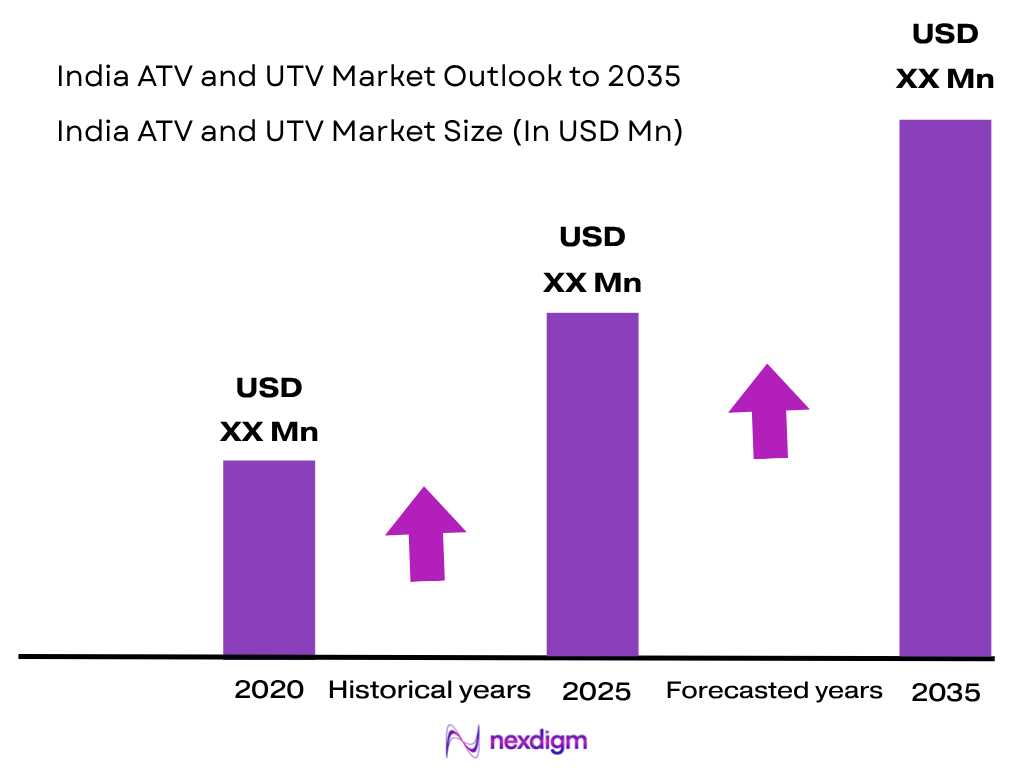
The India ATV and UTV market is valued at approximately ~USD million based on industry assessments, supported by demand from adventure tourism, agriculture, defence mobility, mining operations, and recreational off-road activities. The market is driven by increasing adoption of utility terrain vehicles for remote-area transportation and rising investments in outdoor recreation infrastructure. Global ATV and UTV research indicates continued expansion due to agricultural applications, sports activities, and commercial utility demand.
The India ATV and UTV market is concentrated across cities and regions with strong tourism, agricultural, defence, and industrial activity. Cities such as Delhi NCR, Mumbai, Bengaluru, Pune, Jaipur, Chandigarh, and Hyderabad represent important demand centres due to higher purchasing capability, adventure tourism development, private estates, and institutional applications. Himalayan tourism destinations, Rajasthan desert regions, plantation areas in South India, and defence-sensitive border regions also contribute significantly to adoption.
Market Segmentation
By Vehicle Type
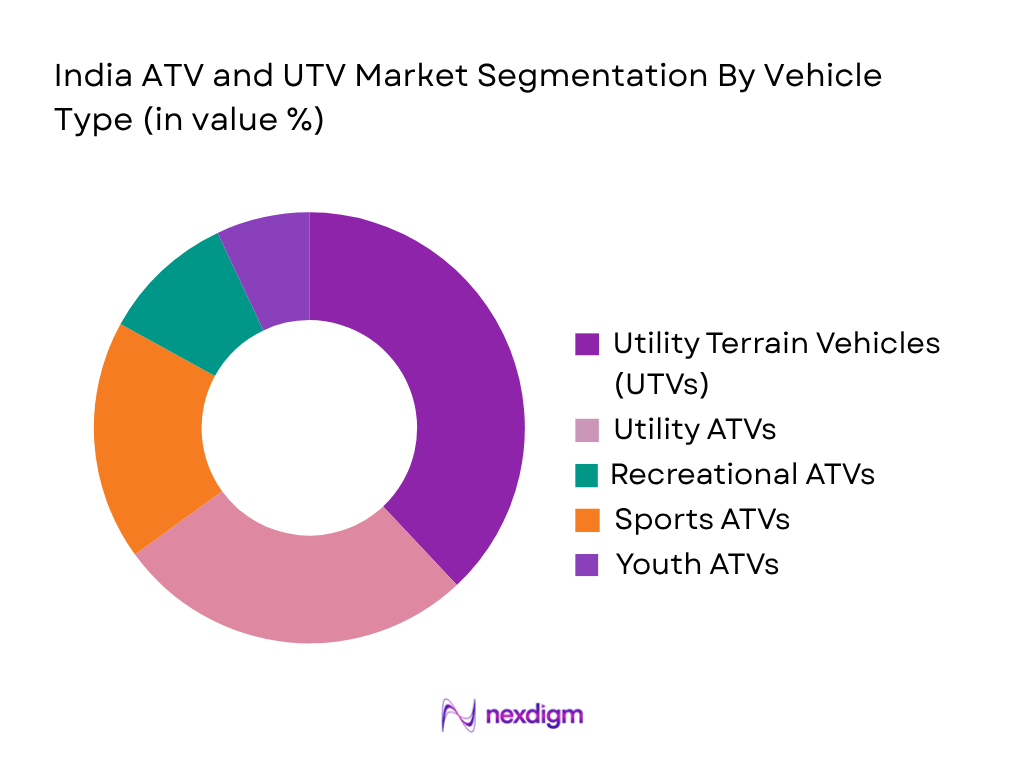
India ATV and UTV market is segmented by vehicle type into utility ATVs, recreational ATVs, sports ATVs, youth ATVs, utility terrain vehicles (UTVs), and side-by-side vehicles (SxS). Utility terrain vehicles and side-by-side vehicles hold a dominant position due to their broader commercial usability across agriculture, defence, tourism, and industrial applications. Their higher passenger capacity, cargo-carrying capability, towing ability, and adaptability across multiple terrains make them preferred over conventional ATVs for professional users.
By Application
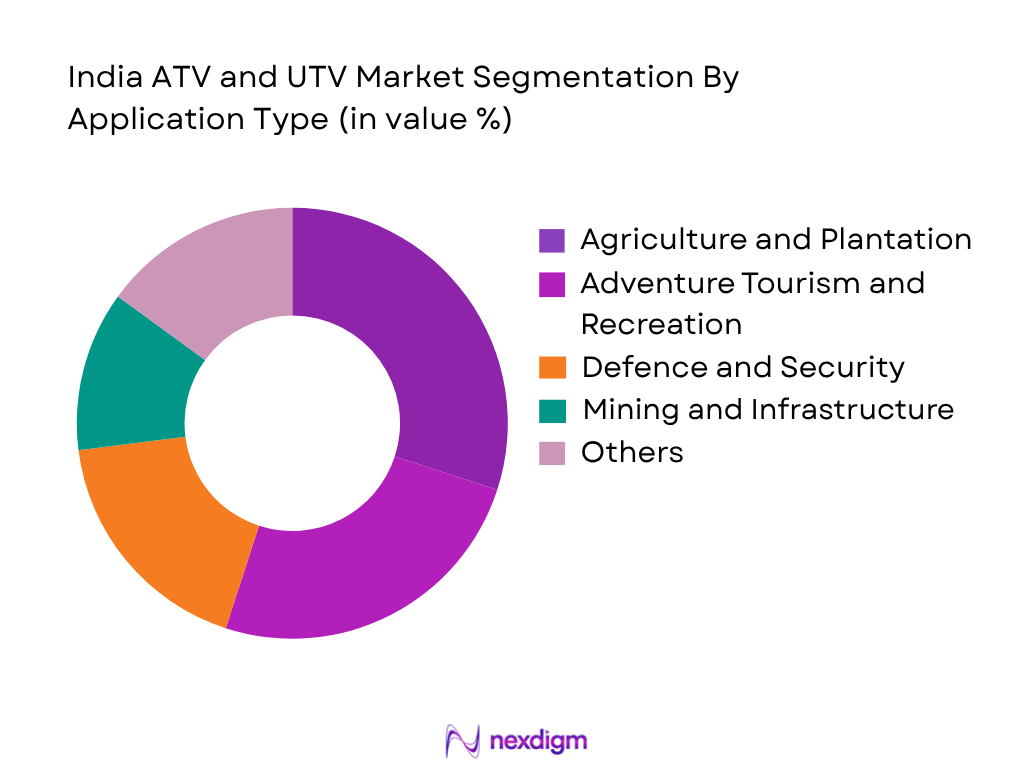
India ATV and UTV market is segmented by application into agriculture, adventure tourism, defence and security, mining, infrastructure, industrial utility, forestry, and recreational usage. Agriculture and adventure tourism represent leading application segments due to increasing need for compact mobility solutions in uneven terrains. Farm owners, plantation operators, resorts, and adventure parks increasingly use ATVs and UTVs for transportation, surveillance, and operational efficiency.
Competitive Landscape
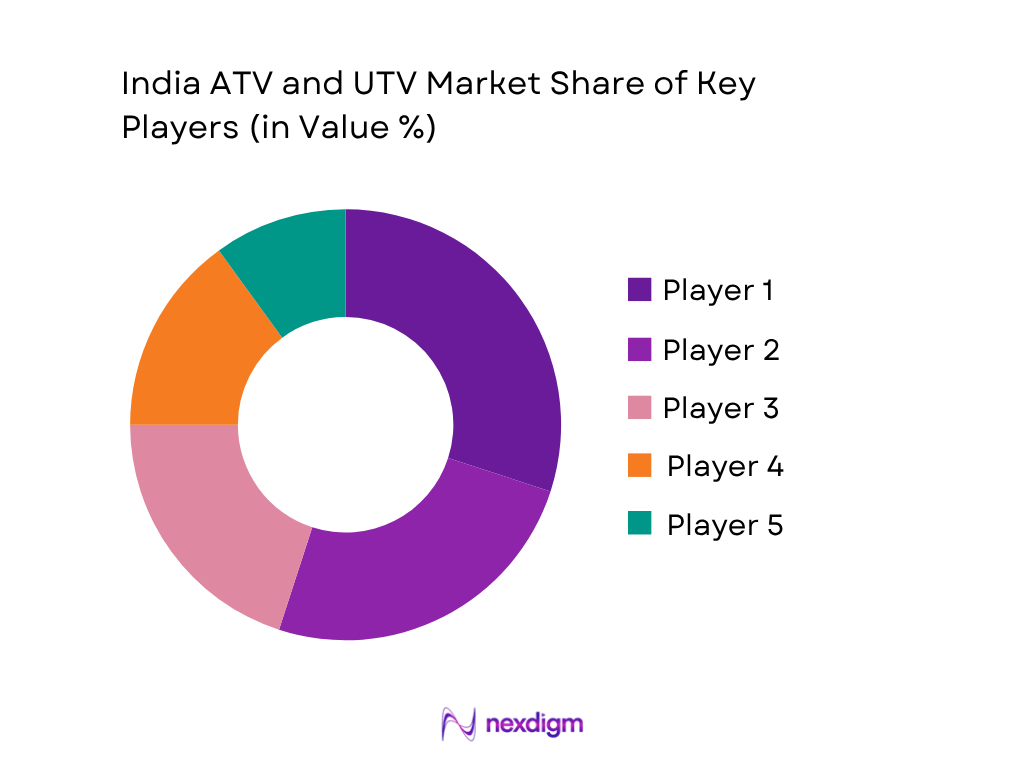
The India ATV and UTV market remains fragmented with participation from global powersports manufacturers, agricultural equipment companies, defence mobility providers, and domestic electric off-road vehicle developers. Global companies such as Polaris, BRP, Honda, Yamaha, and Kawasaki dominate premium recreational and utility segments, while domestic players focus on localized electric and commercial applications.
| Company | Establishment Year | Headquarters | Major Product Focus | Key Application | India Market Approach | Technology Focus | Distribution Strength | Competitive Position |
| Polaris Inc. | 1954 | USA | ~ | ~ | ~ | ~ | ~ | ~ |
| BRP Inc. | 1942 | Canada | ~ | ~ | ~ | ~ | ~ | ~ |
| Honda Motor Co. | 1948 | Japan | ~ | ~ | ~ | ~ | ~ | ~ |
| Yamaha Motor Co. | 1955 | Japan | ~ | ~ | ~ | ~ | ~ | ~ |
| Kubota Corporation | 1890 | Japan | ~ | ~ | ~ | ~ | ~ | ~ |
India ATV and UTV Market Analysis
Growth Drivers
Expansion of Adventure Tourism and Off-Road Recreation Activities
The growth of adventure tourism is supporting increased adoption of ATV and UTV vehicles in India, particularly across mountain, desert, forest, and resort-based recreational locations. According to the Ministry of Tourism, India recorded over 2,500 million domestic tourist visits in 2023, creating a broader customer base for adventure experiences, including off-road activities, camping, and recreational vehicle experiences. States such as Uttarakhand, Himachal Pradesh, Rajasthan, Goa, and Karnataka have witnessed increased development of adventure tourism infrastructure supported by government tourism initiatives. The Ministry of Tourism allocated ₹2,479 crore for tourism development schemes in FY 2024-25, supporting infrastructure enhancement across destinations. The growing number of adventure parks, resorts, and off-road experience centres is increasing demand for recreational ATVs, sports ATVs, and side-by-side vehicles. Additionally, India’s expanding middle-income population and rising domestic travel frequency are encouraging premium recreational activities. The increasing availability of guided ATV experiences and rental-based ownership models is creating new adoption opportunities beyond individual buyers, supporting broader utilization of off-road vehicles across tourism destinations.
Increasing Demand for Utility Mobility in Agriculture, Defence and Remote Operations
ATV and UTV adoption is increasing due to their ability to operate in difficult terrains where conventional vehicles face operational limitations. India’s agriculture sector remains a major demand contributor, with the World Bank reporting that agriculture, forestry, and fishing contributed approximately 18% of India’s GDP in recent assessments and supported the livelihood of over 40% of the workforce. Utility ATVs and UTVs are increasingly used for plantation management, farm monitoring, livestock movement, and transportation across uneven agricultural land. Defence and security applications also represent a significant opportunity due to India’s extensive border areas and challenging terrain conditions. The Ministry of Defence received a budget allocation of ₹6.21 lakh crore in FY 2024-25, supporting modernization programs and procurement of advanced mobility solutions. UTV platforms provide advantages such as high ground clearance, four-wheel-drive capability, and compact mobility for border patrol, logistics support, and tactical applications. Mining, infrastructure, and forest departments are also adopting compact off-road vehicles for remote operations, increasing demand for specialized utility platforms.
Market Challenges
Limited Regulatory Framework and Road Usage Restrictions for ATV and UTV Vehicles
The India ATV and UTV market faces challenges due to limited regulatory clarity regarding road usage, registration, and classification of off-road vehicles. Unlike conventional automobiles, many ATVs and UTVs are primarily designed for private land, agricultural, recreational, defence, and industrial applications rather than public road transportation. The Ministry of Road Transport and Highways reported that India had more than 36 crore registered motor vehicles as of 2023, highlighting the scale of the regulated automotive ecosystem; however, dedicated frameworks for recreational off-road vehicles remain limited. The absence of standardized road-use guidelines restricts wider consumer adoption and limits potential applications in urban mobility. Additionally, state-level variations in vehicle registration requirements create operational uncertainty for buyers and distributors. The requirement for specialized transportation arrangements for vehicles that cannot be freely operated on public roads increases ownership complexity. This challenge particularly affects individual recreational buyers and tourism operators who require easier mobility between operating locations. Development of clearer regulatory pathways, safety standards, and registration mechanisms could improve market accessibility and encourage broader adoption among commercial and recreational users.
High Import Dependency and Limited Local Manufacturing Ecosystem
The India ATV and UTV market remains dependent on imported vehicles, components, and technology due to limited domestic manufacturing capabilities in the powersports segment. According to India’s Ministry of Commerce and Industry, the country imported automotive components worth over USD 20 billion during FY 2023-24, reflecting continued dependence on international supply chains for specialized vehicle technologies. Premium ATV and UTV brands operating in India primarily rely on completely built units or imported assemblies, increasing supply chain complexity and limiting product availability. The lack of large-scale domestic production for engines, transmissions, specialized suspension systems, and off-road drivetrain components restricts cost optimization and customization for Indian conditions. Additionally, limited availability of trained technicians and specialized service centres creates maintenance challenges, especially outside major metropolitan regions. Rural and remote users often face longer service cycles due to limited dealer penetration. Establishing localized assembly capabilities, component manufacturing partnerships, and stronger aftermarket networks would support improved accessibility and long-term adoption of ATV and UTV platforms in India.
Market Opportunities
Development of Electric ATV and UTV Platforms for Sustainable Off-Road Mobility
The transition toward electric mobility is creating opportunities for electric ATV and UTV adoption in agriculture, tourism, industrial, and government applications. India’s electric vehicle ecosystem is expanding rapidly, supported by policy initiatives such as the PM Electric Drive Revolution in Innovative Vehicle Enhancement (PM E-DRIVE) scheme, approved with an allocation of ₹10,900 crore in 2024 to accelerate electric mobility adoption. Electric off-road vehicles can address applications requiring low-noise operation, reduced emissions, and efficient maintenance, particularly in wildlife tourism, resorts, agricultural estates, and industrial facilities. According to the Ministry of Heavy Industries, India’s electric vehicle adoption has crossed millions of registered electric vehicles across categories, indicating increasing acceptance of battery-powered mobility solutions. Electric UTVs can provide operational advantages in controlled environments such as plantations, airports, warehouses, and recreational parks. Domestic development of battery systems, electric drivetrains, and compact utility platforms can reduce dependency on imports and create opportunities for localized manufacturing. Growing environmental regulations and sustainability initiatives among commercial operators are expected to encourage future demand for electric off-road mobility solutions.
Expansion of Agriculture and Commercial Utility Applications
Agriculture and commercial operations represent significant opportunities for ATV and UTV adoption due to increasing demand for efficient mobility solutions in rural and remote environments. According to the Ministry of Agriculture and Farmers Welfare, India had approximately 145 million operational land holdings as per agricultural census data, creating a large base of potential users requiring improved farm mobility solutions. Utility ATVs and UTVs can support activities such as crop monitoring, plantation management, irrigation inspection, livestock movement, and transportation of agricultural inputs. The growth of organized farming, horticulture, and plantation industries is increasing demand for compact vehicles capable of navigating uneven terrain. Additionally, India’s infrastructure development activities are expanding remote construction projects where compact utility vehicles can support material movement and workforce transportation. Government focus on agricultural mechanization through schemes promoting farm equipment adoption further supports opportunities for specialized mobility solutions. Increased awareness among farmers, contractors, and industrial operators regarding productivity benefits can expand ATV and UTV applications beyond recreation into commercial utility segments.
Future Outlook
The India ATV and UTV market is expected to witness steady expansion driven by increasing adventure tourism infrastructure, rising agricultural mechanization, defence modernization programs, and adoption of electric off-road mobility solutions. Demand is expected to shift from recreational-only usage toward commercial utility applications, supported by localization, improved service networks, and diversified financing models. The India ATV and UTV market is expected to grow at a CAGR of ~% during 2026-2035, reaching a market value of approximately ~USD million by the forecast period.
Major Players
- Polaris Inc.
- Bombardier Recreational Products Inc. (BRP)
- Honda Motor Co., Ltd.
- Yamaha Motor Co., Ltd.
- Kawasaki Heavy Industries Ltd.
- Suzuki Motor Corporation
- Textron Inc. (Arctic Cat)
- CFMOTO
- Kubota Corporation
- Deere & Company (John Deere)
- Kwang Yang Motor Co. Ltd. (KYMCO)
- Hisun Motors Corporation
- Mahindra Defence Systems
- BEML Limited
- Powerland Agro Tractor Vehicles
Key Target Audience
- ATV and UTV Manufacturers and Importers
- Adventure Tourism Operators and Off-Road Experience Companies
- Agriculture Equipment Manufacturers and Farm Equipment Companies
- Defence and Security Organizations
- Mining and Infrastructure Companies
- Government and Regulatory Bodies (Ministry of Road Transport and Highways, Ministry of Defence, Ministry of Agriculture and Farmers Welfare)
- Industrial Fleet Operators and Utility Vehicle Buyers
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves developing an ecosystem framework covering ATV and UTV manufacturers, importers, distributors, dealers, end users, and component suppliers. Secondary research is conducted using industry databases, company reports, government publications, and proprietary market information to identify key variables influencing market growth, demand patterns, and competitive dynamics.
Step 2: Market Analysis and Construction
This stage involves analysing historical market trends, vehicle sales patterns, application adoption, import activity, pricing structures, and distribution networks. Market sizing is developed through a combination of supply-side assessment, demand analysis, and vehicle-level evaluation across ATV and UTV categories.
Step 3: Hypothesis Validation and Expert Consultation
Market assumptions are validated through discussions with industry participants, including manufacturers, distributors, dealers, adventure tourism operators, and commercial users. Primary interviews provide insights into purchasing behaviour, operational requirements, technology adoption, and future market opportunities.
Step 4: Research Synthesis and Final Output
The final stage integrates primary and secondary research findings through data triangulation. Insights are consolidated into market size assessment, segmentation analysis, competitive benchmarking, future outlook, and strategic recommendations for stakeholders operating in the India ATV and UTV ecosystem.

- Executive Summary
- Research Methodology (Market Definition and Scope, India ATV and UTV Vehicle Taxonomy, All-Terrain Vehicle Classification, Utility Terrain Vehicle Classification, Recreational Off-Road Vehicle Classification, Sports ATV Classification, Youth ATV Classification, Side-by-Side Vehicle Classification, Engine Displacement Mapping, Vehicle Configuration Assessment, Drive System Classification, Terrain Application Mapping)

- Definition and Scope
- India ATV and UTV Industry Evolution and Off-Road Mobility Development
- ATV and UTV Vehicle Architecture, Manufacturing and Assembly Process
- India ATV and UTV Value Chain Analysis
- India ATV and UTV Supply Chain Analysis
- Engine, Transmission, Suspension, Differential, Drivetrain, Chassis and Safety System Ecosystem Analysis

- Growth Drivers (Increasing Adventure Tourism and Off-Road Recreation Activities, Expansion of Farm Mechanization and Estate Utility Applications, Rising Defence and Border Surveillance Requirements, Growing Adoption in Mining and Infrastructure Mobility, Increasing Demand for Remote Terrain Transportation Solutions, Growth of Off-Road Experience Parks and Recreational Resorts, Rising Awareness of Utility Terrain Vehicles for Commercial Operations, Increasing Availability of Imported Premium ATV and UTV Brands, Growth of Electric ATV and UTV Solutions, Increasing Demand for Compact High-Mobility Vehicles in Challenging Terrains)
- Market Challenges (Limited Public Road Usage Regulations for ATV and UTV Vehicles, High Import Dependency for Premium Off-Road Vehicles, High Acquisition Cost Compared with Conventional Utility Vehicles, Limited Dealer and Service Infrastructure Outside Major Cities, Lack of Consumer Awareness Regarding Utility Applications)
- Market Opportunities (Local Assembly and Component Localization of ATV and UTV Platforms, Electric Off-Road Vehicle Development, Agriculture-Focused Utility ATV Deployment, Adventure Tourism Fleet Expansion, Defence and Paramilitary Procurement Opportunities, Mining and Remote Infrastructure Mobility Applications, Fleet Leasing and Rental Business Models)
- Market Trends (Increasing Adoption of 4WD and All-Wheel Drive Off-Road Platforms, Growth of CVT Automatic Transmission Systems, Premium Recreational Off-Road Vehicle Demand, Expansion of Adventure Tourism-Based ATV Experiences, Growth of Side-by-Side UTV Adoption, Increasing Electric ATV and UTV Development, Integration of GPS Tracking and Vehicle Telematics)
- Regulatory and Standards Landscape (Automotive Research Association of India Vehicle Testing Framework, Central Motor Vehicle Rules Applicability Assessment, Import Certification Requirements, Customs Classification and Import Duty Framework, Defence Procurement Regulations for High-Mobility Vehicles, Adventure Tourism Safety Guidelines)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis

- By Market Value (2020-2025)
- By ATV and UTV Unit Sales (2020-2025)
- By ATV Sales Volume (2020-2025)
- By UTV / Side-by-Side Vehicle Sales Volume (2020-2025)
- By Recreational Off-Road Vehicle Sales (2020-2025)
- By Commercial Utility Off-Road Vehicle Sales (2020-2025)

- By Vehicle Type (In Value %)
Sport ATVs
Utility ATVs
Recreational ATVs
Youth ATVs
Racing ATVs
Agricultural Utility ATVs
Utility Terrain Vehicles (UTVs)
Side-by-Side Vehicles (SxS)
Sport Side-by-Side Vehicles
Recreational Utility Vehicles - By Engine Capacity (In Value %)
Below 250cc ATVs
250cc–500cc ATVs
500cc–700cc ATVs
700cc–1,000cc ATVs
Above 1,000cc UTVs
High-Performance Off-Road Vehicle - By Application Type (In Value %)
Agricultural and Farm Utility Operations
Plantation and Estate Management
Adventure Tourism and Recreational Activities
Off-Road Sports and Racing Events
Defence and Border Patrol Applications
Mining and Quarry Operations
Infrastructure and Construction Site Mobility
Forest and Wildlife Management
Disaster Management and Rescue Operations
Industrial Facility Transportation
Airport Ground Support Operations
Security and Surveillance Applications - By Sales Channel (In Value %)
OEM Direct Sales
Authorized ATV and UTV Dealers
Specialized Off-Road Vehicle Dealers
Agriculture Equipment Dealers
Defence and Government Procurement
Adventure Tourism Operators
Rental and Experience Centers
Online Automotive Platforms
Used ATV and UTV Dealers
Import-Based Distribution Channels - By Region (In Value %)
North India
South India
West India
East India
Central India
Northeast India

- Market Share of Major Players (By Revenue, Unit Sales, ATV Segment, UTV Segment, Engine Capacity, Application Segment, Powertrain Type, Sales Channel, Region)
- Cross Comparison Parameters (Product Portfolio Breadth Across ATV, UTV and Side-by-Side Platforms, Engine Displacement Coverage Across Utility and Performance Segments, 2WD/4WD and Differential Lock Capability, Agriculture Defence Tourism and Industrial Application Coverage, Dealer Network and After-Sales Service Reach Across India)
- SWOT Analysis of Major Players
- Competitive Positioning Matrix
- Product and Technology Portfolio Benchmarking
- Pricing and Distribution Network Benchmarking
- Import and Localization Strategy Assessment
- Dealer Network and Aftermarket Ecosystem Assessment
- Market Entry Strategy Assessment
- Detailed Profiles of Major Companies
Polaris Inc. – Sportsman ATVs, RZR Side-by-Side Vehicles and Ranger Utility Platforms
Bombardier Recreational Products Inc. (BRP) – Can-Am ATV and Side-by-Side Off-Road Platforms
Honda Motor Co., Ltd. – Utility ATVs and Recreational Off-Road Vehicles
Yamaha Motor Co., Ltd. – Grizzly ATVs and Viking Wolverine Utility Vehicles
Kawasaki Heavy Industries Ltd. – Brute Force ATVs and Teryx UTV Platforms
Suzuki Motor Corporation – KingQuad ATV Platforms
Textron Inc. (Arctic Cat) – Utility and Sport ATV Platforms
CFMOTO – Utility ATVs and Side-by-Side Vehicles
Kubota Corporation – RTV Utility Terrain Vehicles
Deere & Company (John Deere) – Gator Utility Vehicles
Kwang Yang Motor Co. Ltd. (KYMCO) – Utility ATV and Side-by-Side Vehicles
Hisun Motors Corporation – Utility ATV and UTV Platforms
Mahindra Defence Systems – Tactical Off-Road Mobility Vehicles
BEML Limited – Defence and Mining High Mobility Vehicles
Powerland Agro Tractor Vehicles – Electric and Utility ATV Platforms

- End User Segmentation Assessment
- Individual Recreational Users Analysis
- Adventure Tourism and Off-Road Experience Operators Analysis
- Agriculture and Plantation User Analysis
- Defence and Security Forces Analysis
- Mining and Quarry Operator Analysis
- Infrastructure and Construction Company Analysis

- By Market Value (2026-2035)
- By ATV and UTV Unit Sales (2026-2035)
- By Utility ATV Sales Volume (2026-2035)
- By Sports ATV Sales Volume (2026-2035)
- By Utility Terrain Vehicle (UTV) Sales Volume (2026-2035)
- By Electric ATV and UTV Sales Volume (2026-2035)
- By Recreational Off-Road Vehicle Sales Volume (2026-2035)
- By Commercial Utility Off-Road Vehicle Sales Volume (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
