
 Download PDF
Market Overview
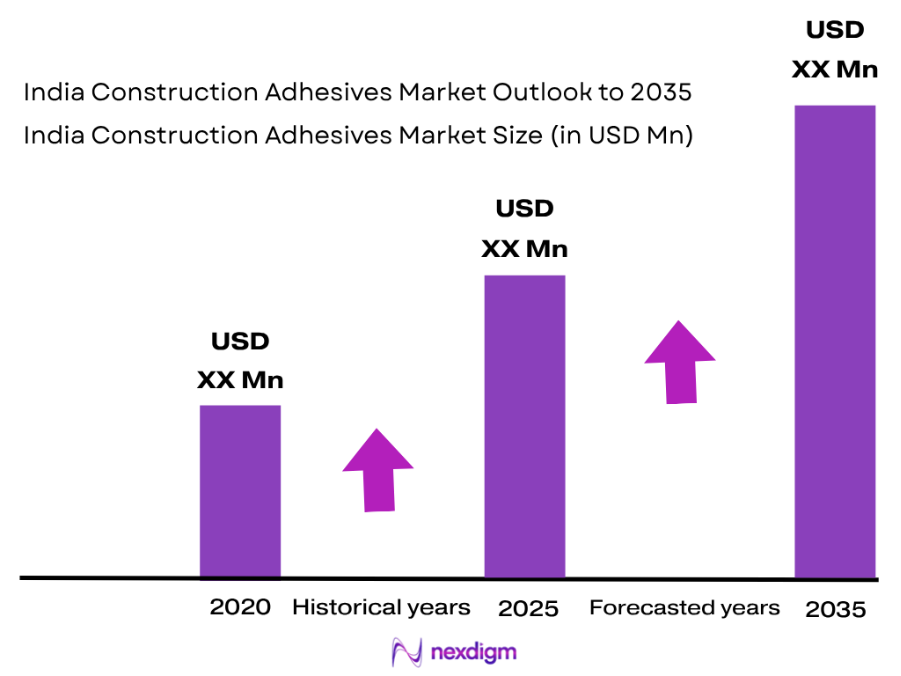
The India Construction Adhesives Market is valued at approximately ~USD XX million, supported by housing, tile installation, infrastructure and factory-produced construction materials. Construction GVA increased from approximately ₹21.09 lakh crore to ₹22.77 lakh crore across the latest two annual observations. Urban housing completions under PMAY-U also increased from more than 74.25 lakh houses to 85.04 lakh houses, expanding the installation base for tile, stone, AAC-block, flooring and interior construction adhesives.
Delhi NCR, Mumbai-Pune, Bengaluru, Hyderabad, Chennai and Ahmedabad are prominent India Construction Adhesives Market demand centers because they combine high-rise housing, commercial buildings, premium tile installation, metro infrastructure and renovation. Across the latest two observations, PMAY-U completed urban homes increased from 74.25 lakh to 85.04 lakh, while grounded houses reached 114.33 lakh. These dense urban corridors particularly favor polymer-modified tile adhesives, large-format tile systems, AAC-block adhesives and structural bonding solutions over traditional site-mixed installation practices.
Market Segmentation
By Product Type
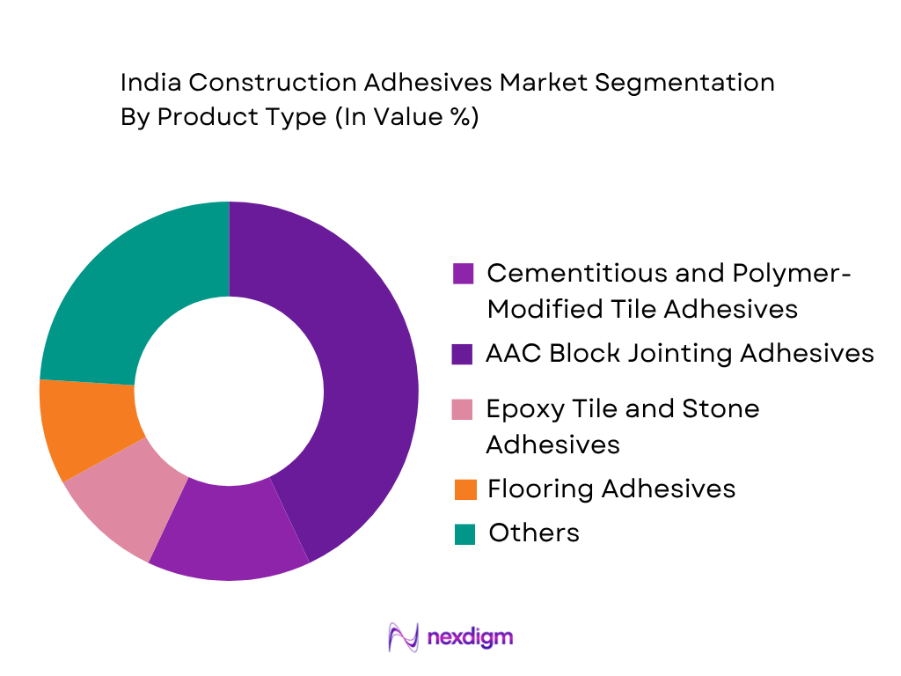
The India Construction Adhesives Market is segmented into cementitious tile adhesives, polymer-modified tile adhesives, epoxy systems, AAC-block jointing adhesives, flooring adhesives, structural anchoring adhesives, polyurethane and hybrid construction adhesives. Cementitious and polymer-modified tile adhesives represent the dominant product category because ceramic, vitrified, porcelain and natural-stone installation forms a major adhesive-consuming construction activity. Factory-produced thin-bed adhesives improve consistency compared with manually proportioned cement-sand mortar and are better suited to vitrified and large-format tiles with low water absorption. Growing apartment construction, premium bathrooms, façades and tile-on-tile renovation reinforce demand for flexible and higher-bond products. India also has an increasingly mature manufacturing and applicator ecosystem: Roff reports more than 10 manufacturing plants and a dealer network exceeding 7,500 outlets, while Saint-Gobain Weber operates manufacturing facilities across 10 strategic Indian locations. These distribution networks make packaged tile adhesives accessible well beyond metropolitan projects and support conversion from conventional mortar to standardized adhesive installation.
By Application
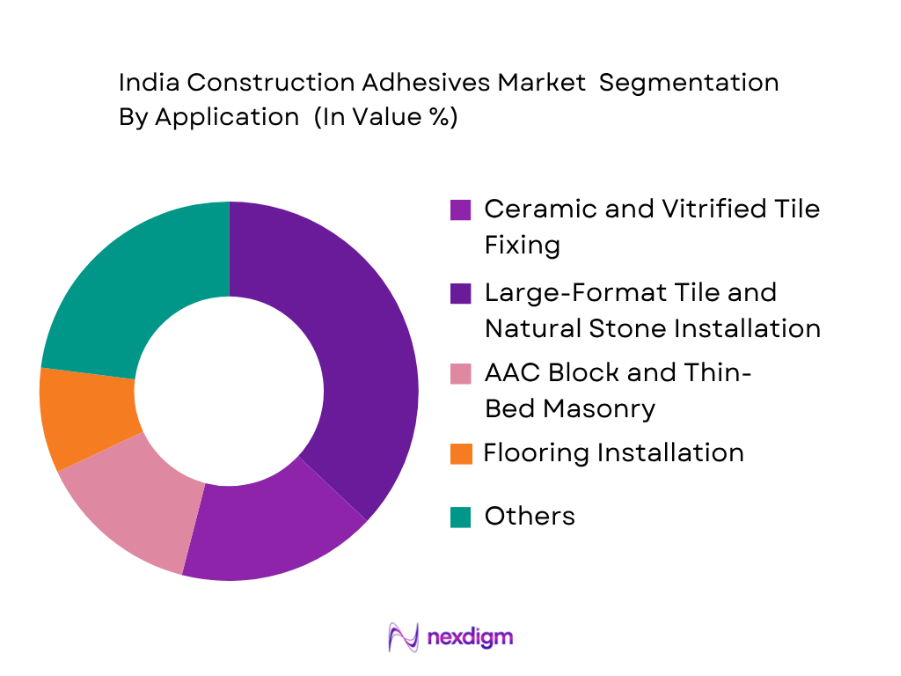
The India Construction Adhesives Market is segmented into ceramic and vitrified tile fixing, large-format tiles and stone, AAC-block jointing, flooring installation, structural anchoring, interior panels and general construction bonding. Tile and stone fixing is the dominant modeled application, supported by extensive residential finishing, commercial interiors and the transition toward larger vitrified and porcelain formats that need engineered adhesion rather than thick-bed mortar. Large tiles place greater demands on tensile adhesion, deformability, open time and slip resistance, accelerating usage of polymer-modified formulations. Renovation further expands the addressable application base because tile-on-tile systems can avoid demolition and reduce project disruption. MYK LATICRETE provides products ranging from standard tile adhesives to highly flexible large-format systems and operates a broad manufacturing footprint across Telangana, Rajasthan, Tamil Nadu, Gujarat, Madhya Pradesh, Andhra Pradesh and West Bengal. ARDEX ENDURA similarly manufactures tile and construction adhesives from multiple plants spanning southern, western, northern and eastern India, illustrating the nationwide nature of demand.
Competitive Landscape
The India Construction Adhesives Market combines a strong domestic specialty-chemical leader with multinational construction-material groups and specialist tile-installation companies. Pidilite/Roff, Saint-Gobain Weber, MYK LATICRETE, ARDEX ENDURA and Sika compete through tile and stone technologies, polymer modification, local manufacturing, dealer reach, contractor training and project specification. Distribution depth is particularly important because consumption extends from large urban developments to individual contractors and renovation projects in Tier-II and Tier-III cities.
| Major Player | Establishment Year | Headquarters | Tile & Stone Adhesives | Large-Format / Flexible Systems | India Manufacturing | Dealer / Applicator Reach | Structural & Specialty Bonding | Technical Support |
| Pidilite Industries / Roff | 1959 | Mumbai, India | ~ | ~ | ~ | ~ | ~ | ~ |
| Saint-Gobain Weber India | 2004 | Mumbai, India | ~ | ~ | ~ | ~ | ~ | ~ |
| MYK LATICRETE India | 1999 | Hyderabad, India | ~ | ~ | ~ | ~ | ~ | ~ |
| ARDEX ENDURA India | 1997 | Bengaluru, India | ~ | ~ | ~ | ~ | ~ | ~ |
| Sika India | 1910* | Baar, Switzerland | ~ | ~ | ~ | ~ | ~ | ~ |
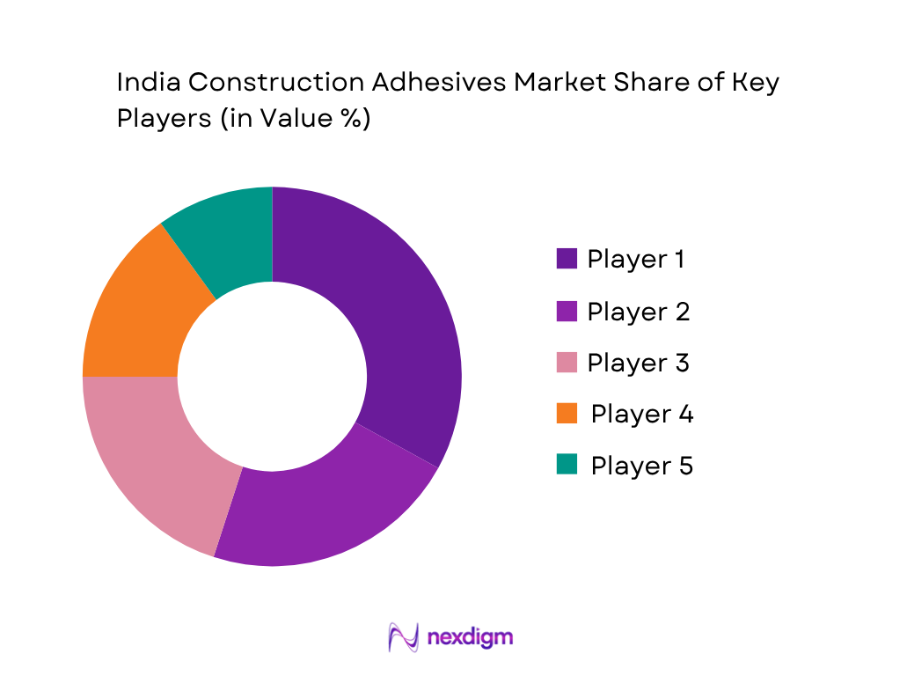
India Construction Adhesives Market Analysis
Growth Drivers
Urban Housing and Large-Scale Construction Activity Expanding Adhesive Consumption
India’s housing and construction pipeline is increasing demand for tile adhesives, AAC-block jointing compounds, flooring adhesives, bonding agents and structural adhesive systems. The Ministry of Housing and Urban Affairs reported 118.63 lakh PMAY-U houses sanctioned, 114.33 lakh grounded and 85.04 lakh completed as of July 2024, creating a large installed base requiring tiles, bathrooms, masonry and interior finishes. National construction GVA at current prices reached ₹22,77,317 crore in FY2023-24 and increased to ₹24,49,208 crore in FY2024-25, while the 2025-26 provisional estimate reached ₹26,55,075 crore. This scale supports conversion from site-mixed mortar toward factory-produced polymer-modified adhesives where installers require consistent bond strength, thinner application layers and compatibility with vitrified or low-absorption tiles. Government infrastructure spending reinforces the demand base, with ₹11,11,111 crore allocated for central capital expenditure in 2024-25 and ₹1.5 lakh crore provided for long-term infrastructure loans to states. World Bank data record India’s 2024 GDP at USD 3.91 trillion and GDP per capita at USD 2,694.7, while IMF data place nominal GDP for FY2023-24 at ₹295,357 billion, supporting continued expansion of construction-material consumption.
Infrastructure, Data Centres and Specification-Based Construction Increase High-Performance Adhesive Demand
India’s shift toward larger infrastructure, digital facilities and technically specified buildings is strengthening demand for higher-performance epoxy, polyurethane, flooring and structural anchoring adhesives. The Union Budget provided ₹11,11,111 crore for capital expenditure in 2024-25, alongside ₹1.5 lakh crore of long-term interest-free financing for state infrastructure. Construction GVA subsequently reached ₹24,49,208 crore in FY2024-25 and ₹26,55,075 crore in FY2025-26, reflecting the expanding physical asset base. Digital infrastructure adds another adhesive-intensive application: government data show national data-centre capacity exceeded 1,500 MW during 2025 and reached about 1,575 MW in 2026, with major facilities concentrated in Mumbai, Navi Mumbai, Chennai, Hyderabad, Bengaluru, Delhi NCR and Jamnagar. Such buildings require flooring systems, raised-floor installation, insulation bonding, interior panel fixing and anchoring products with predictable performance. Infrastructure and institutional projects also increasingly use specification-driven materials rather than informal site mixes, favouring standardized construction adhesives with tested open time, adhesion and substrate compatibility. World Bank figures place India’s 2024 GDP at USD 3.91 trillion, while the IMF records nominal FY2023-24 GDP of ₹295,357 billion, demonstrating the economic scale supporting sustained capital formation and premium construction-material adoption.
Market Challenges
Site-Mixed Mortar Practices and Execution Variability Limit Consistent Adhesive Conversion
Traditional cement-sand mortar remains an important competitive substitute for packaged tile and masonry adhesives, particularly where project specifications and applicator practices are less standardized. The challenge becomes significant because India’s construction base is exceptionally large: construction GVA stood at ₹22,77,317 crore in FY2023-24 and ₹24,49,208 crore in FY2024-25, while 114.33 lakh PMAY-U houses had already been grounded and 85.04 lakh completed by July 2024. This volume creates thousands of installation environments with different substrates, tile formats, water dosages, surface preparation and contractor skill levels. Polymer-modified tile adhesives require controlled mixing, correct notch-trowel selection, adequate coverage and suitable curing; incorrect execution can cause hollow spots, slip or tile detachment despite using a technically compliant product. Larger vitrified and porcelain formats increase this challenge because low-absorption surfaces rely more heavily on polymer adhesion than conventional ceramic tiles. Standardization therefore depends not only on product availability but on applicator training and specification enforcement. World Bank data put India’s 2024 GDP at USD 3.91 trillion and GDP per capita at USD 2,694.7, while IMF data show nominal FY2023-24 GDP of ₹295,357 billion, illustrating the scale of the construction economy across which manufacturers must improve installation consistency.
Specialty Polymer and Petrochemical Input Dependence Creates Formulation Supply Risk
Construction adhesive manufacturers face raw-material risk because higher-performance products depend on redispersible polymers, acrylic chemistries, polyurethane intermediates, epoxy components and specialty rheology additives whose supply chains are linked to broader petrochemical trade. Government chemical statistics show India imported 314,526 metric tonnes of low-density polyethylene, 1,306,283 metric tonnes of high-density polyethylene and 106,478 metric tonnes of polystyrene during FY2024-25, illustrating the country’s continuing reliance on imported polymer streams across the chemical economy. Imports of the fibre intermediate acrylonitrile reached 210,456 metric tonnes, while purified terephthalic acid imports reached 2,093,444 metric tonnes in the same period. These are not direct proxies for construction-adhesive consumption, but they demonstrate the scale of external petrochemical sourcing faced by domestic formulators operating within connected resin and additive supply chains. For construction adhesives, disruption in specialty polymer availability can affect formulation consistency, localization strategies and production planning for polymer-modified tile adhesives, epoxies and reactive systems. India’s large demand base magnifies this exposure: World Bank data record 2024 GDP of USD 3.91 trillion, and the IMF places FY2023-24 nominal GDP at ₹295,357 billion. Construction GVA of ₹24,49,208 crore in FY2024-25 means disruptions affect a construction sector operating at substantial physical scale.
Market Opportunities
Large-Format Tiles, Renovation and Premium Installation Create Higher-Value Adhesive Demand
Large-format vitrified tiles, porcelain slabs and renovation applications create a strong future opportunity for flexible polymer-modified, epoxy and tile-on-tile construction adhesives. Current housing activity provides a substantial installed base: PMAY-U reported 118.63 lakh houses sanctioned, 114.33 lakh grounded and 85.04 lakh completed in July 2024. These homes add kitchens, bathrooms and tiled living areas that will generate both initial installation and subsequent replacement demand. The broader construction sector reached ₹24,49,208 crore of current-price GVA in FY2024-25 and ₹26,55,075 crore in FY2025-26, creating a continuing flow of apartments, commercial interiors and institutional buildings where larger tile formats are increasingly technically feasible. Large slabs place greater demands on deformability, tensile adhesion, extended open time and anti-slip performance than traditional cement mortar, giving organized adhesive manufacturers scope to move customers into higher-performance grades. Tile-on-tile renovation can further reduce demolition requirements by bonding new finishes directly over adequately prepared existing surfaces. World Bank data place India’s 2024 GDP at USD 3.91 trillion and GDP per capita at USD 2,694.7, while IMF data record nominal FY2023-24 GDP at ₹295,357 billion. These current indicators support future expansion of premium construction finishing and organized adhesive usage across metropolitan and Tier-II urban markets.
Data Centres, Prefabrication and Structural Anchoring Expand Specialty Adhesive Applications
India’s growing digital and industrial infrastructure provides a future opportunity for structural anchoring, flooring, panel bonding and prefabrication adhesives beyond conventional tile fixing. Government data indicate data-centre capacity exceeded 1,500 MW during 2025 and reached approximately 1,575 MW in 2026, with major operating clusters in Mumbai, Navi Mumbai, Chennai, Hyderabad, Bengaluru and Delhi NCR. The government also reported 38,231 GPUs onboarded through 14 empanelled service providers and data centres under the national AI compute framework, illustrating the scale of advanced digital facilities requiring technically controlled construction environments. These assets create demand for chemical anchors, raised-floor adhesives, resilient flooring systems, panel bonding and fast-curing installation products. Parallel infrastructure spending remains substantial, with the Union Budget allocating ₹11,11,111 crore for capital expenditure and ₹1.5 lakh crore for state infrastructure support in 2024-25. Prefabricated construction can further expand adhesive usage because factory assembly favors repeatable bonding of panels, insulation and modular components instead of reliance solely on mechanical fasteners. World Bank data record India’s 2024 GDP at USD 3.91 trillion, while IMF data place nominal FY2023-24 GDP at ₹295,357 billion. This current economic and construction base provides room for specialty adhesives to expand into technically demanding non-tile applications.
Future Outlook
The India Construction Adhesives Market is forecast to expand at approximately ~X.X% CAGR during 2026–2035, supported by urban housing, infrastructure expenditure, renovation, larger tile formats and increased use of factory-produced building materials. The market is expected to move progressively from basic cementitious fixing toward polymer-modified, flexible, epoxy and specialty bonding systems. Contractor training, organized distribution and compliance with performance standards will increasingly determine product adoption. Housing provides a substantial structural demand base. PMAY-U had 118.63 lakh houses sanctioned, 114.33 lakh grounded and 85.04 lakh completed as of July 2024. The subsequently approved PMAY-U 2.0 framework targets assistance for 1 crore urban families with an envisaged investment of ₹10 lakh crore and government assistance of ₹2.30 lakh crore. These programs broaden the future base of tiled floors, bathrooms, kitchens, masonry and interior finishes where packaged construction adhesives are applied.
Major Players
- Pixilate Industries / Roff
- Saint-Gobain Weber India
- MYK LATICRETE India
- ARDEX ENDURA India
- Sika India
- MAPEI Construction Products India
- Fosroc Chemicals India
- Asian Paints SmartCare
- UltraTech Building Products / TileFixo
- Astral Adhesives
- Kerakoll India
- CICO Technologies
- STP Limited
- MC-Bauchemie India
- Berger Paints India / HomeShield
Key Target Audience
- Construction Adhesive and Construction Chemical Manufacturers
- Tile, Ceramic and Natural Stone Manufacturers
- Real Estate Developers and General Contractors
- Building Material Distributors and Tile Dealers
- Flooring, Tile and Interior Installation Contractors
- AAC Block and Prefabricated Building Product Manufacturers
- Investments and Venture Capitalist Firms
- Government and Regulatory Bodies (Bureau of Indian Standards, Ministry of Housing and Urban Affairs, Central Public Works Department, Ministry of Road Transport and Highways, National Highways Authority of India)
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves constructing an ecosystem map covering adhesive manufacturers, polymer suppliers, dry-mix plants, tile manufacturers, distributors, developers and applicators. Extensive secondary research is used to identify variables including construction activity, tile type, installation method, adhesive coverage, polymer loading, application class, distribution reach and organized versus traditional installation practices.
Step 2: Market Analysis and Construction
Historical information for the India Construction Adhesives Market is evaluated using top-down and bottom-up approaches. Top-down analysis examines construction GVA, housing development, infrastructure activity and renovation demand. Bottom-up modelling evaluates adhesive consumption using tile area, AAC-block construction, flooring installations, structural anchoring applications, product coverage and application-specific dosage assumptions.
Step 3: Hypothesis Validation and Expert Consultation
Market hypotheses are validated through computer-assisted telephone interviews with adhesive manufacturers, dry-mix producers, tile companies, distributors, project contractors and applicators. These consultations validate product penetration, polymer-modified adhesive adoption, large-format tile requirements, regional channel structures, contractor purchasing patterns and technical criteria affecting product selection.
Step 4: Research Synthesis and Final Output
The final phase triangulates national construction indicators, housing data, company disclosures, technical standards and primary research. Bottom-up product-consumption models are reconciled with top-down construction activity to establish a consistent market framework. The analysis is then structured by product type, application, region, distribution channel, competitive positioning and future opportunity.

- Executive Summary
- Research Methodology (Market Definitions and Assumptions, India Construction Adhesives Market Boundary, Cementitious versus Polymer Adhesive Classification, Tile Adhesive Assessment, Stone Adhesive Assessment, Flooring Adhesive Assessment, AAC Block Jointing Adhesive Assessment, Construction Bonding Agent Assessment, Epoxy Adhesive Assessment, Polyurethane Adhesive Assessment, Acrylic Adhesive Assessment, Hybrid Polymer Adhesive Assessment, Structural Anchoring Adhesive Assessment, Panel and Interior Adhesive Assessment, Roofing and Insulation Adhesive Assessment, Prefabricated Construction Adhesive Assessment, Large-Format Tile Assessment, Vitrified Tile Assessment, Natural Stone Assessment, IS 15477 Compliance Mapping, EN 12004 Classification Mapping, Green Building and Low-VOC Assessment, Contractor and Applicator Mapping, Dealer and Distributor Mapping, Supply-Side Assessment, Demand-Side Assessment, Top-Down Market Sizing, Bottom-Up Market Sizing, Primary Industry Interviews, Construction Pipeline Assessment, Data Triangulation, Forecasting Framework)

- Definition and Scope
- Evolution of Construction Adhesive Technologies in India, Transition from Site-Mixed Cement-Sand Mortars to Factory-Produced Tile Adhesives, Polymer-Modified Cementitious Adhesives, Vitrified Tile Adhesives, Large-Format Tile Adhesives, Natural Stone Adhesives, Epoxy Adhesives, Flexible Tile Adhesives, AAC Block Jointing Adhesives, Flooring Adhesives, Structural Anchoring Systems, Polyurethane Construction Adhesives, Hybrid Polymer Adhesives, Ready-to-Use Adhesives, Low-VOC Adhesives, Prefabrication and Modular Construction Bonding Systems
- Construction Adhesives Industry Value Chain Analysis
- Construction Adhesives Supply Chain Analysis
- Cement Suppliers, Redispersible Polymer Powder Suppliers, Cellulose Ether Suppliers, Acrylic Polymer Suppliers, Epoxy Resin Suppliers, Polyurethane Raw Material Suppliers, Mineral Filler Suppliers, Specialty Additive Suppliers, Construction Adhesive Manufacturers, Dry-Mix Mortar Plants, Local Blenders, Packaging Suppliers, Building Material Distributors, Tile and Sanitaryware Dealers, Hardware Retailers, Waterproofing Dealers, Contractors, Tile Applicators, Flooring Contractors, Developers, Architects and Specifiers

- Growth Drivers (Urban Housing Construction, Vitrified Tile Consumption, Large-Format Tile Adoption, Residential Renovation, Commercial Fit-Out, Infrastructure Development, AAC Block Adoption, Factory-Mixed Construction Products, Skilled-Labor Productivity Requirements, Premium Tile and Stone Installation, Organized Retail Expansion, Specification-Based Construction)
- Market Challenges (Site-Mixed Cement Mortar Substitution, Low-Cost Unorganized Competition, Incorrect Adhesive Selection, Poor Substrate Preparation, Incorrect Water Dosage, Insufficient Adhesive Coverage, Applicator Skill Gaps, Counterfeit and Low-Grade Products, Polymer Raw Material Dependence, Product Standard Awareness, Tile Detachment Risk, Regional Quality Variation)
- Market Opportunities (Large-Format Tile Adhesives, Flexible Exterior Adhesives, AAC Block Jointing Adhesives, Epoxy Tile and Stone Systems, Tile-on-Tile Renovation Adhesives, Low-VOC Construction Adhesives, Structural Anchoring Systems, Data Centre Flooring Adhesives, Prefabricated Construction Bonding, Natural Stone Adhesives, Rapid-Setting Adhesives, Contractor Training and Certification, Premium Tier-II and Tier-III City Expansion)
- Market Trends (C2-Class Tile Adhesive Adoption, Flexible Polymer-Modified Adhesives, Large-Format Tile Systems, Thin-Bed Installation, Ready-to-Use Adhesives, Epoxy Adhesive Systems, Tile-on-Tile Renovation, AAC Thin-Joint Technology, Low-Dust Formulations, Low-VOC Systems, Factory-Mixed Mortars, Applicator Training, Digital Product Selection Tools)
- Government Regulations and Standards (IS 15477 Ceramic Tile and Stone Adhesive Requirements, BIS Product Performance Requirements, EN 12004-Based Product Classification Practices, CPWD Material Specifications, State PWD Product Approval Requirements, Green Rating for Integrated Habitat Assessment Requirements, Indian Green Building Council Material Considerations, Occupational Safety Requirements, Chemical Labelling and Handling Requirements)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis

- By Market Value (2020-2025)
- By Construction Adhesive Consumption Volume (2020-2025)
- By Cementitious Tile Adhesive Consumption (2020-2025)
- By Polymer-Modified Tile Adhesive Consumption (2020-2025)
- By Epoxy Adhesive Consumption (2020-2025)
- By Polyurethane Adhesive Consumption (2020-2025)
- By AAC Block Jointing Adhesive Consumption (2020-2025)
- By Flooring Adhesive Consumption (2020-2025)

- By Product Type (In Value %)
Cementitious Tile Adhesives
Polymer-Modified Tile Adhesives
Flexible Tile Adhesives
Epoxy Tile and Stone Adhesives
Ready-to-Use Tile Adhesives
AAC Block Jointing Adhesives
Construction Bonding Agents
Flooring Adhesives
Polyurethane Construction Adhesives
Acrylic Construction Adhesives
Hybrid Polymer Adhesives
Panel and Interior Adhesives
Roofing and Insulation Adhesives
Specialty Repair Adhesives - By Resin and Chemistry Type (In Value %)
Cementitious Polymer-Modified Systems
Redispersible Polymer Powder-Based Systems
Acrylic Polymer-Based Adhesives
Epoxy Resin-Based Adhesives
Polyurethane-Based Adhesives
Hybrid Polymer Adhesives
Vinyl Acetate and PVA Systems
Reactive Methacrylate Adhesives
Synthetic Resin Bonding Agents
Specialty Mineral-Polymer Systems - By Application (In Value %)
Ceramic Tile Fixing
Vitrified Tile Fixing
Large-Format Tile Installation
Natural Stone Fixing
Wall Tile Installation
Floor Tile Installation
Tile-on-Tile Applications
Exterior Façade Tile Fixing
Swimming Pool Tile Fixing
AAC Block Jointing - By Construction Activity (In Value %)
New Residential Construction
New Commercial Construction
Infrastructure Construction
Industrial Construction
Residential Renovation
Commercial Refurbishment
Tile Replacement
Interior Fit-Out - By Building Type (In Value %)
Individual Houses and Villas
Commercial Offices
Shopping Malls and Retail Buildings
Hotels and Hospitality Buildings
Hospitals and Healthcare Facilities
Educational Buildings
Data Centres
Mixed-Use Developments - By Tile and Surface Type (In Value %)
Ceramic Tiles
Vitrified Tiles
Porcelain Tiles
Large-Format Slabs
Natural Stone
Granite
Mosaic Tiles
Glass Tiles
Engineered Stone
Existing Tile Substrates

- Market Share of Major Players (By India Revenue, Construction Adhesive Volume, Tile Adhesive Portfolio, Large-Format Tile Adhesive Portfolio, AAC Block Adhesive Exposure, Flooring Adhesive Exposure, Structural Anchoring Portfolio, Residential Construction Exposure, Commercial Construction Exposure, Infrastructure Exposure, Manufacturing Footprint, Dealer Network, Applicator Network, Technical Support Coverage)
- Cross Comparison Parameters (Tile Stone and Construction Adhesive Portfolio Breadth, IS 15477 and High-Performance Tile Adhesive Capability, Large-Format Vitrified Tile and Exterior Application Capability, AAC Block Flooring and Structural Bonding Capability, India Manufacturing and Dry-Mix Production Footprint, Dealer Distributor and Applicator Network Reach, Low-VOC Green-Building and Premium Polymer Technology Capability, Technical Specification Applicator Training and Jobsite Support Capability)
- SWOT Analysis of Major Players (Brand Strength, Technology Portfolio, Manufacturing, Distribution, Applicator Reach)
- Major Companies
Pidilite Industries / Roff
Saint-Gobain Weber India
MYK LATICRETE India
ARDEX ENDURA India
Sika India
MAPEI Construction Products India
Fosroc Chemicals India
Asian Paints SmartCare
UltraTech Building Products / TileFixo
Astral Adhesives
Kerakoll India
CICO Technologies
STP Limited
MC-Bauchemie India
Berger Paints India / HomeShield

- Real Estate Developer Requirement Assessment
- General Contractor Requirement Assessment
- Tile Applicator Requirement Assessment
- Flooring Contractor Requirement Assessment
- Interior Contractor Requirement Assessment
- Infrastructure Contractor Requirement Assessment
- AAC Block Contractor Requirement Assessment
- Architect and Specification Requirement Assessment

- By Market Value (2026-2035)
- By Construction Adhesive Consumption Volume (2026-2035)
- By Cementitious Tile Adhesive Consumption (2026-2035)
- By Polymer-Modified Tile Adhesive Consumption (2026-2035)
- By Epoxy Adhesive Consumption (2026-2035)
- By Polyurethane Adhesive Consumption (2026-2035)
- By AAC Block Jointing Adhesive Consumption (2026-2035)
- By Flooring Adhesive Consumption (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
