
 Download PDF
Market Overview
The India Dump Truck Market is valued at approximately ~USD XX billion, supported by mining, quarrying, highway construction and bulk-material movement. Coal production increased from 969.07 million tonnes to 1,039.59 million tonnes, while coal dispatch rose from 950.39 million tonnes to 1,012.72 million tonnes across the latest two annual periods. This large physical-material base sustains demand for multi-axle tippers, rigid mining dump trucks and severe-duty hauling equipment.
Odisha, Jharkhand, Chhattisgarh, Rajasthan, Karnataka and Maharashtra represent important India Dump Truck Market demand clusters because of coal, iron ore, limestone, quarrying and infrastructure activity. Coal production moved from 969.07 million tonnes to 1,039.59 million tonnes, while dispatch increased from 950.39 million tonnes to 1,012.72 million tonnes across the latest two annual periods. Mining belts require high-payload dumpers, whereas industrial and infrastructure corridors support multi-axle construction tippers.
Market Segmentation
By Dump Truck Type
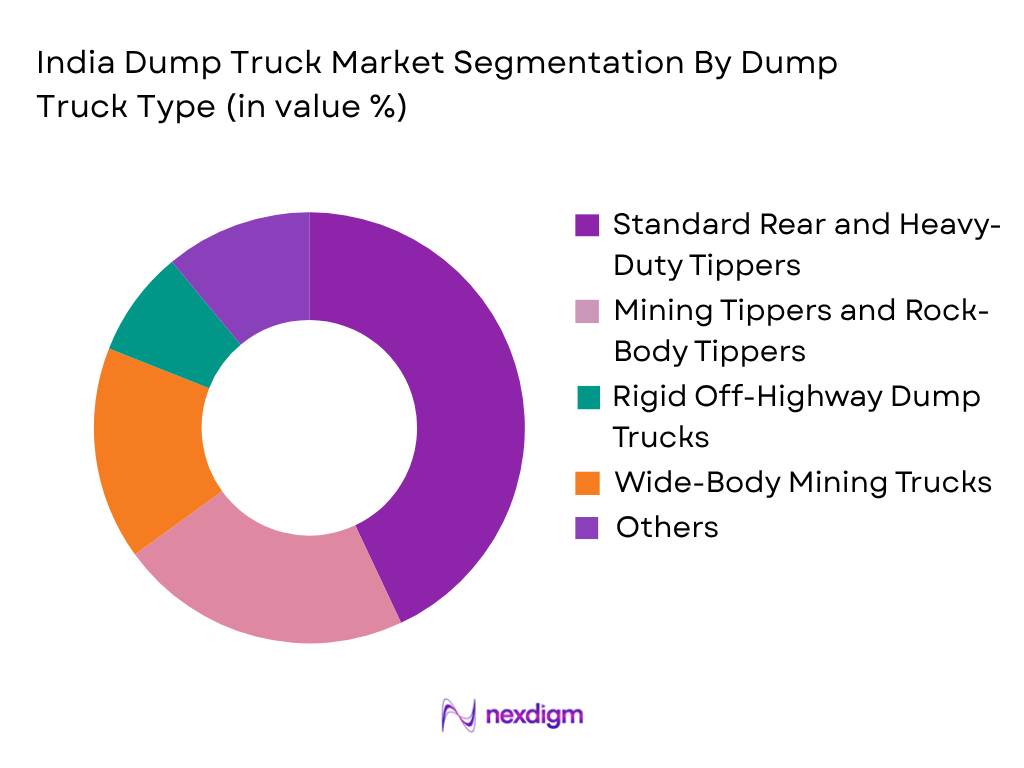
The India Dump Truck Market is segmented into standard rear tippers, rock-body and box-body tippers, mining tippers, rigid off-highway dump trucks, wide-body mining trucks, articulated dump trucks and electric mining dump trucks. Standard and heavy-duty on-road tippers hold the dominant position because they address the widest range of road construction, earthmoving, coal transportation, aggregates, cement, quarrying and mineral movement applications. Their ability to operate both within project sites and on public roads gives them a broader addressable customer base than dedicated off-highway equipment. Indian OEMs also offer extensive GVW and axle configurations for contractor-specific requirements. Tata Motors, for example, offers heavy tipper configurations including the 35,000 kg Prima 3530.K, while the wider Indian market includes 28-ton, 35-ton, 42-ton and higher multi-axle formats. Dedicated rigid dump trucks remain crucial in large open-cast mines where payload and cost per tonne moved take priority over highway mobility.
By Application Type
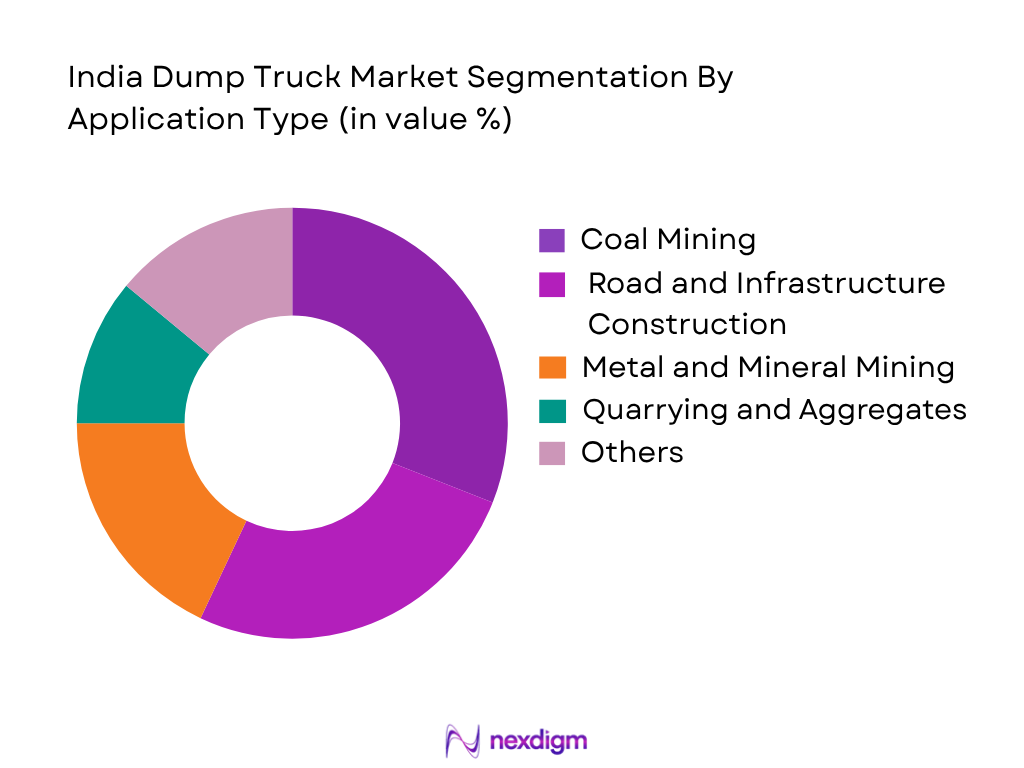
The India Dump Truck Market is segmented into coal mining, metal and mineral mining, road and infrastructure construction, quarrying and aggregates, cement and limestone transportation, and other industrial applications. Coal mining represents the dominant application because India’s open-cast mining system requires continuous movement of coal and large quantities of overburden between excavation areas, crushers, stockyards and dumping locations. Domestic coal production reached 1,039.59 million tonnes, while subsequent fiscal-year production reached 1,047.523 million tonnes, sustaining high equipment utilization in coal-producing states. Iron ore production also reached 289 million metric tonnes, compared with 277 million metric tonnes in the preceding fiscal period. These physical volumes support demand ranging from conventional multi-axle mining tippers to high-capacity rigid dump trucks. Infrastructure remains another major application as national highway construction and earthmoving require continuous movement of soil, aggregates and construction material.
Competitive Landscape
The India Dump Truck Market combines domestic commercial-vehicle manufacturers with global and indigenous mining-equipment suppliers. Tata Motors, Ashok Leyland and BharatBenz have strong positions in multi-axle construction and mining tippers, while BEML and global heavy-equipment suppliers address higher-payload off-highway applications. Competition is increasingly based on GVW and payload breadth, engine torque, axle robustness, body configuration, mine-site service capability, connected fleet technology and alternative powertrains rather than truck acquisition alone.
| Major Player | Establishment Year | Headquarters | Core Dump Truck Focus | Payload / GVW Breadth | Mining Capability | Construction Capability | Powertrain Capability | India Manufacturing / Service Position |
| Tata Motors Ltd. | 1945 | Mumbai, India | ~ | ~ | ~ | ~ | ~ | ~ |
| Ashok Leyland Ltd. | 1948 | Chennai, India | ~ | ~ | ~ | ~ | ~ | ~ |
| BEML Limited | 1964 | Bengaluru, India | ~ | ~ | ~ | ~ | ~ | ~ |
| Volvo Trucks | 1928 | Gothenburg, Sweden | ~ | ~ | ~ | ~ | ~ | ~ |
| Komatsu Ltd. | 1921 | Tokyo, Japan | ~ | ~ | ~ | ~ | ~ | ~ |
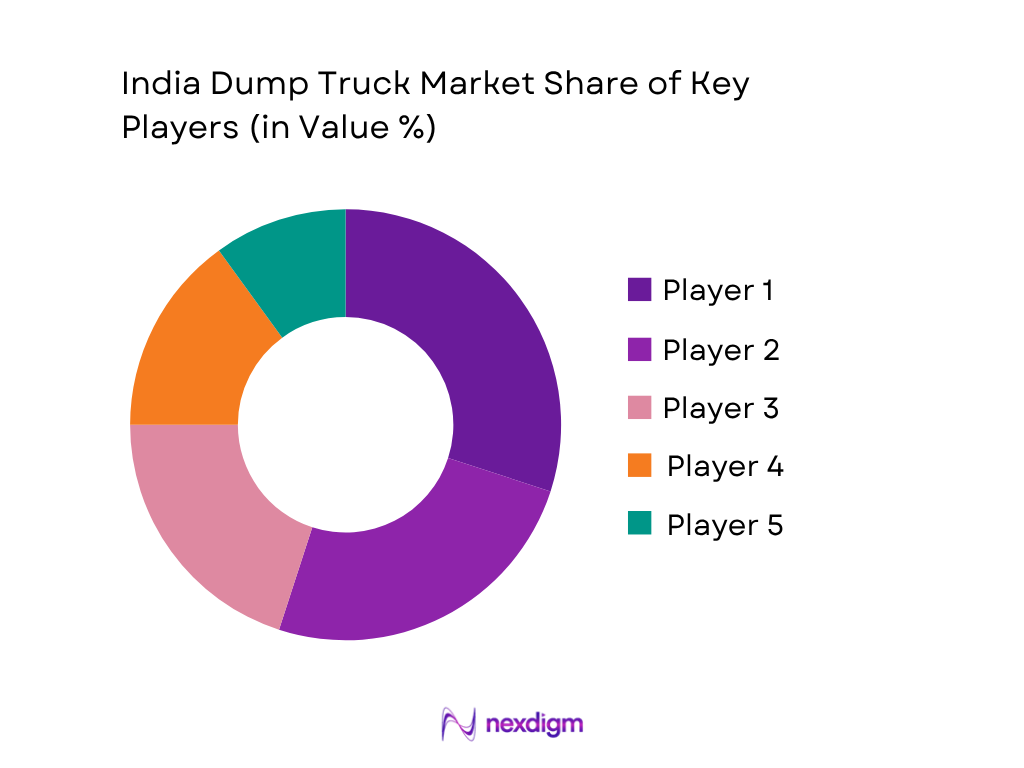
India Dump Truck Market Analysis
Growth Drivers
Expansion of Coal Production and Open-Cast Mining Haulage
India’s coal mining ecosystem is a direct demand driver for the India Dump Truck Market because open-cast mines require continuous movement of coal, overburden and excavated material between mine faces, crushers, stockyards and loading points. Calendar-year coal production reached 1,039.59 million tonnes in 2024, while coal dispatch reached 1,012.72 million tonnes. During FY2024-25, production subsequently reached 1,047.523 million tonnes, with coal supply totaling 1,025.33 million tonnes. Calendar-year production remained at 1,042.90 million tonnes in 2025, while captive and commercial mines alone produced 203.70 million tonnes, creating a substantial operating base for rigid dump trucks, mining tippers and high-payload haulage vehicles. High material volumes favor trucks engineered for repetitive loading cycles, steep gradients, unpaved haul roads and severe axle loads. The wider economic environment also supports continued industrial activity, with India recording USD 3.91 trillion in GDP and USD 2,694.74 GDP per capita in 2024. Increasing mine mechanization further raises demand for higher-horsepower engines, automatic or powershift transmissions, reinforced bodies, payload monitoring, mine telematics and dependable site-service support, strengthening the operating requirement for specialized dump-truck fleets.
Highway Construction and Mineral Production Supporting Multi-Axle Tipper Demand
The India Dump Truck Market is also driven by the combination of highway development and large-scale mineral extraction, both of which require intensive movement of aggregates, earth, rock and excavated materials. India’s National Highway network extends 146,195 km, including 45,947 km of four-lane-and-above highways and 2,474 km of high-speed corridors. National Highway construction reached 12,349 km in FY2023-24, while 5,853 km was completed during April-December 2024-25. Mining creates an additional demand layer: iron ore production reached 289 million metric tonnes in FY2024-25, manganese ore output reached 3.8 million metric tonnes, bauxite reached 24.7 million metric tonnes, and lead concentrate reached 393 thousand tonnes. Iron ore production during April-May FY2025-26 stood at 53.0 million metric tonnes, while bauxite reached 4.73 million metric tonnes. These activities require 6×4, 8×4 and higher multi-axle tippers for road-accessible haulage and larger off-highway vehicles inside mines and quarries. India’s USD 3.91 trillion GDP in 2024 provides the macroeconomic base for infrastructure and industrial investment, supporting sustained utilization of construction tippers, rock-body trucks and mining haulage fleets across mineral-producing and infrastructure-intensive states.
Market Challenges
Commercial Vehicle Demand Cyclicality and Fleet Procurement Volatility
The India Dump Truck Market faces procurement volatility because construction and mining tippers form part of the broader commercial-vehicle ecosystem, where fleet additions depend on contractor order books, mine production schedules, financing conditions and replacement decisions. Commercial vehicle production stood at 1,034,947 units in FY2024-25 and increased to 1,170,150 units in FY2025-26, while domestic commercial vehicle sales moved from 958,679 units to 1,079,871 units across the same periods. Commercial vehicle exports reached 80,751 units in FY2024-25 and 94,793 units in FY2025-26. During April-June 2026 alone, domestic commercial vehicle sales reached 264,831 units. These large changes in annual procurement volumes create production-planning challenges for dump-truck OEMs because tipper demand is additionally concentrated around mining contracts, infrastructure execution and fleet replacement cycles. A mining operator may require high-volume purchases during project mobilization but significantly fewer additions after fleet deployment, while infrastructure contractors can defer replacement when project awards slow. India’s economy generated USD 3.91 trillion in GDP during 2024, with GDP per capita at USD 2,694.74, but strong macroeconomic scale does not eliminate equipment-cycle volatility. OEMs therefore need flexible production, dealer inventories, financing support and aftermarket capacity to manage changing heavy-duty truck procurement patterns.
Road-to-Rail Freight Diversion Increasing Competition for Bulk Haulage Activity
Expansion of rail freight infrastructure presents a structural challenge for sections of the India Dump Truck Market involved in longer-distance movement of coal, minerals, cement and other bulk materials. Indian Railways has approved 306 Gati Shakti Multi-Modal Cargo Terminals, with 118 terminals commissioned and an estimated combined handling capacity of 192 million tonnes per annum. These terminals have mobilized approximately ₹8,600 crore in private investment, while freight revenue generated through the terminal network reached ₹12,608.05 crore in FY2024-25. More significantly for road-based haulage, an additional 2,672 million tonnes of freight has shifted from road to rail since 2014. This does not remove dump-truck requirements inside mines, quarries, construction sites or first-mile and last-mile logistics, but it can reduce addressable long-distance bulk transportation undertaken by road-based tipper fleets. Dump-truck operators increasingly need to concentrate on mine-face movement, crusher-to-stockyard transport, terminal feeder movements, infrastructure sites and shorter-haul applications where rail cannot substitute direct vehicle access. India’s USD 3.91 trillion GDP in 2024 supports expanding freight activity overall, yet greater multimodal integration changes where trucks generate utilization. The challenge therefore shifts from absolute freight availability toward fleet positioning, utilization rates and selecting applications where specialized tipper mobility remains operationally essential.
Market Opportunities
Electrification and Indigenous Development of High-Payload Mining Dump Trucks
Electrification of mining haulage creates a future growth opportunity for the India Dump Truck Market because India already operates a large material-movement base that can support deployment of advanced electric-drive and high-payload equipment. Coal production reached 1,039.59 million tonnes in 2024 and 1,042.90 million tonnes in 2025, while FY2024-25 iron ore production reached 289 million metric tonnes. These current volumes provide intensive haul cycles where regenerative braking, electric drive systems, payload optimization and centralized fleet monitoring can deliver operational advantages. Indigenous equipment development is progressing simultaneously: current Indian mining-truck platforms include electric-drive dumpers with payload capabilities of approximately 136 metric tonnes and 186 metric tonnes, body capacities of 82 cubic metres and 111 cubic metres, and high-power configurations reaching 2,300 hp. Such equipment demonstrates domestic capability to move beyond conventional highway tippers into technologically complex mine-haulage platforms. India’s wider industrial base is supported by USD 3.91 trillion of GDP in 2024 and a population of approximately 1.45 billion, providing scale for domestic manufacturing and component localization. Future opportunities therefore extend into traction systems, high-voltage electrical equipment, regenerative braking, mine charging infrastructure, thermal management, telematics, autonomous-ready controls and long-term maintenance contracts specifically designed around large open-cast mining fleets.
Expansion of Mineral Mining and Mine-Site Mechanization Creating High-Payload Fleet Opportunities
India’s growing mineral-production base creates an opportunity for higher-payload dump trucks, wide-body mining vehicles and specialized mine-fleet services as operators seek to move larger physical volumes with fewer haul cycles. Iron ore production reached 289 million metric tonnes in FY2024-25, manganese ore reached 3.8 million metric tonnes, bauxite reached 24.7 million metric tonnes, and lead concentrate reached 393 thousand tonnes. The momentum continued into FY2025-26, with April-May iron ore production reaching 53.0 million metric tonnes, manganese ore reaching 0.70 million metric tonnes, bauxite reaching 4.73 million metric tonnes, and zinc concentrate reaching 0.28 million metric tonnes. Coal adds substantially greater material movement, with 1,042.90 million tonnes produced during calendar 2025 and 1,016.14 million tonnes supplied. These volumes create an operating environment where mine owners can increasingly justify high-capacity rigid dumpers, wide-body trucks, automatic transmissions, onboard weighing, proximity detection, tire-pressure monitoring and centralized dispatch systems. India’s USD 3.91 trillion GDP and USD 2,694.74 GDP per capita in 2024 provide the broader economic foundation for industrial investment. Future market growth can therefore emerge not only from additional truck purchases but also from mine-site service contracts, remanufacturing, predictive maintenance, fleet optimization and localized production of heavy-duty drivetrain, hydraulic and dump-body components.
Future Outlook
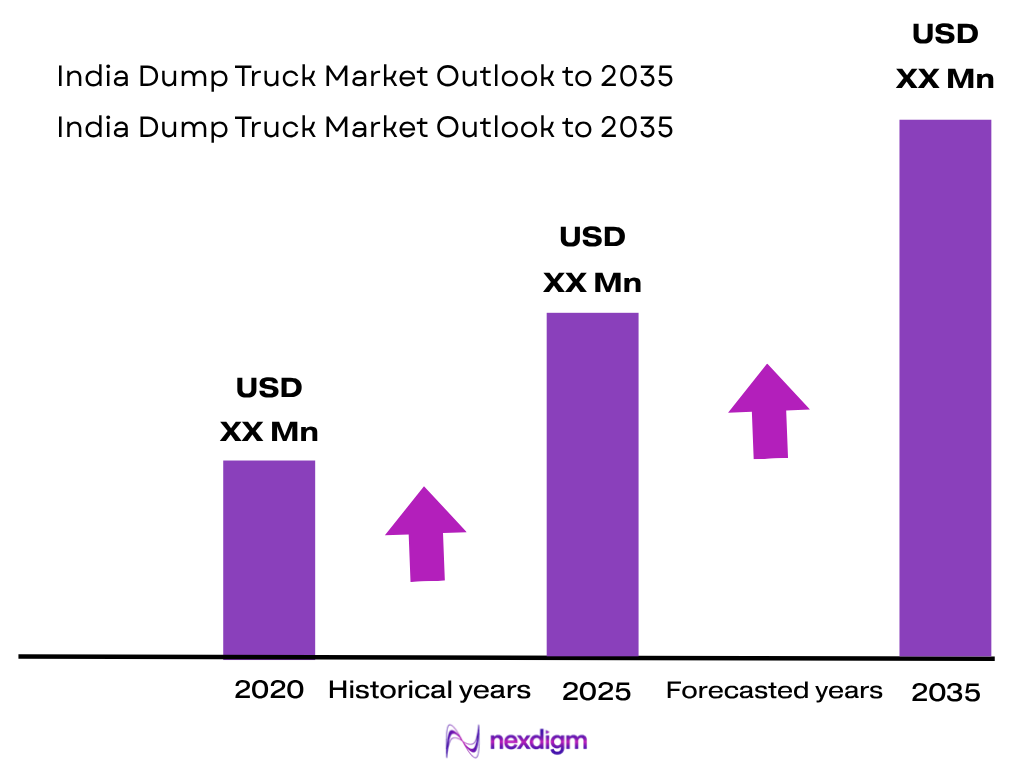
The India Dump Truck Market is expected to expand at approximately ~X.X% CAGR during 2026–2035, supported by sustained mining mechanization, infrastructure construction, fleet replacement and movement toward higher-payload vehicles. The market will increasingly separate into productivity-focused on-road tippers and specialized off-highway mining haulage systems. Electric drivetrains, connected fleet platforms, automated transmissions, payload monitoring and indigenous mining-equipment manufacturing will become increasingly important competitive differentiators.
Road infrastructure remains a substantial demand platform. India’s National Highway network extends approximately 146,195 km, including 45,947 km of four-lane and above highways and 2,474 km of high-speed corridors. National Highway construction reached 12,349 km in one recent fiscal period, while NHAI subsequently constructed 5,614 km and recorded more than ₹2,50,000 crore of capital expenditure. Large highway projects require excavation, quarry materials, aggregates, embankment fill and asphalt movement, supporting repeated tipper utilization throughout project execution. Mining will remain central to high-capacity dump-truck demand. Coal output reached 1,047.523 million tonnes, while iron ore production reached 289 million metric tonnes, manganese ore reached 3.8 million metric tonnes, and bauxite reached 24.7 million metric tonnes. Increased mine mechanization creates opportunities for higher payload trucks, stronger powertrains, automatic transmissions, fleet dispatch platforms and mine-site maintenance contracts.
Major Players
- Tata Motors Ltd. – Prima and Signa Construction Tippers / Mining Tippers / Electric Tipper Platforms
- Ashok Leyland Ltd. – AVTR Modular Tippers / Mining and Construction Tippers
- Daimler India Commercial Vehicles Pvt. Ltd. – BharatBenz Heavy-Duty Construction and Mining Tippers
- VE Commercial Vehicles Ltd. – Eicher Pro Heavy-Duty Tippers / Volvo Trucks Mining Solutions
- Volvo Trucks India – FMX Mining and Construction Tippers / Heavy-Haul Applications
- Scania Commercial Vehicles India Pvt. Ltd. – Heavy Mining Tippers / Off-Road Haulage Solutions
- BEML Limited – Indigenous Rigid Dump Trucks / Electric Mining Dump Trucks / Mining Equipment
- Komatsu India Pvt. Ltd. – Rigid Mining Dump Trucks / Electric Drive Mining Trucks
- Caterpillar India Pvt. Ltd. – Off-Highway Dump Trucks / Rigid Mining Trucks / Mine Fleet Technology
- SANY Heavy Industry India Pvt. Ltd. – Wide-Body Mining Dump Trucks / Electric Open-Cast Mining Trucks
- Mahindra & Mahindra Ltd. – BLAZO X Heavy-Duty Construction and Mining Tippers
- AMW Motors Ltd. – Heavy-Duty Tipper and Mining Truck Platforms
- Action Construction Equipment Ltd. – Construction and Heavy Equipment Applications
- LiuGong India Pvt. Ltd. – Mining and Quarry Equipment / Heavy Material-Handling Solutions
- XCMG India – Mining Dump Trucks / Wide-Body Haulage and Construction Equipment
Key Target Audience
- Dump Truck and Heavy Commercial Vehicle Manufacturers
- Mining and Construction Equipment Manufacturers
- Mining, Coal and Mineral Extraction Companies
- Infrastructure, Highway and EPC Contractors
- Cement, Aggregate and Quarry Operators
- Commercial Vehicle Dealers, Fleet Operators and Equipment Rental Companies
- Investments and Venture Capitalist Firms
- Government and Regulatory Bodies (Ministry of Road Transport and Highways, Ministry of Coal, Ministry of Mines, Directorate General of Mines Safety, National Highways Authority of India, Coal India Limited)
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves developing a detailed ecosystem map for the India Dump Truck Market covering truck OEMs, mining-equipment manufacturers, dump-body suppliers, mining companies, contractors, dealers and fleet operators. Key variables include GVW, rated payload, axle configuration, engine output, body capacity, mining production, highway construction, fleet replacement and equipment utilization.
Step 2: Market Analysis and Construction
Historical demand is constructed using a bottom-up assessment of on-road tippers, mining tippers, rigid dump trucks and specialized haulage equipment. Mining production, infrastructure activity, commercial-vehicle output and equipment applications are mapped against available payload classes. The resulting estimates are cross-checked with OEM product portfolios, manufacturing capacity, end-use requirements and regional mining activity.
Step 3: Hypothesis Validation and Expert Consultation
Market hypotheses are validated through structured interviews and CATIs with truck manufacturers, mining companies, infrastructure contractors, fleet owners, dealers and equipment-service providers. These discussions assess payload selection, mine duty cycles, replacement patterns, axle configurations, maintenance intensity, financing preferences, fleet uptime requirements, electrification readiness and procurement criteria used by institutional and private buyers.
Step 4: Research Synthesis and Final Output
The final phase triangulates primary findings with official mining, road-infrastructure and commercial-vehicle indicators. Bottom-up unit estimates are reconciled with supply-side product availability and application-level demand. This process produces the final market segmentation, competitive benchmarking, technology assessment, fleet outlook and strategic opportunity framework for the India Dump Truck Market.

- Executive Summary
- Research Methodology (Market Definition and Scope, India Dump Truck and Tipper Taxonomy, On-Road Tipper and Off-Highway Dump Truck Classification, Rigid and Mining Dump Truck Mapping, GVW and Payload Capacity Assessment, Axle Configuration Mapping, Construction and Mining Application Assessment, Coal and Mineral Haulage Mapping, Infrastructure Project Assessment, Commercial Vehicle Sales and Fleet Assessment, Replacement Cycle Analysis, OEM Production Mapping, Dealer and Service Network Assessment, Market Sizing Framework)

- Definition and Scope
- India Dump Truck and Tipper Industry Evolution and Mining Mechanization Development
- Dump Truck Manufacturing and Assembly Process
- Dump Truck Value Chain Analysis
- India Dump Truck Supply Chain Analysis
- Engine, Transmission, Axle, Suspension, Hydraulic Hoist and Dump Body Ecosystem Analysis
- India Dump Truck Manufacturing, Body-Upfitting and Localization Footprint Assessment
- OEM, Authorized Dealer, Mining Fleet, Infrastructure Contractor and Aftermarket Framework

- Growth Drivers (National Highway and Expressway Expansion, Coal Production and Overburden Movement, Iron Ore and Mineral Mining Activity, Construction and Infrastructure Capital Formation, Cement and Limestone Transportation, Multi-Axle Tipper Replacement, Mechanization of Open-Cast Mines, High-Payload Fleet Adoption)
- Market Challenges (Cyclicality in Mining and Construction Demand, Diesel Fuel Dependence, Severe-Duty Maintenance Requirements, Tire and Drivetrain Wear, Payload Overloading, Driver Availability, Mining Tender Concentration, High-Capacity Charging Infrastructure Requirements, Battery Weight and Mine Duty-Cycle Constraints)
- Market Opportunities (Electric Mining Dump Trucks, Indigenous Mining Equipment Manufacturing, High-Payload Wide-Body Mining Trucks, Automated Transmission Tippers, Mine Fleet Telematics, Predictive Maintenance, Autonomous and Semi-Autonomous Mining Haulage, Remanufactured Powertrain Components, High-Strength Lightweight Dump Bodies, Long-Term Mining Fleet Service Contracts)
- Market Trends (Transition Toward Higher GVW Tippers, Adoption of Automated Manual Transmissions, High-Horsepower Mining Tippers, Multi-Axle Configurations, Electric Open-Cast Mining Trucks, Regenerative Braking, Fleet Telematics, Onboard Weighing, Driver-Assistance Systems, Advanced Mine Safety Systems, Localized Powertrain Components, Connected Fleet Monitoring)
- Regulatory and Standards Landscape (Ministry of Road Transport and Highways Commercial Vehicle Requirements, Central Motor Vehicles Rules, Vehicle Axle Load Regulations, Bharat Stage Emission Requirements, Ministry of Coal Mining Framework, Ministry of Mines Regulatory Framework, Directorate General of Mines Safety Requirements, Vehicle Fitness Regulations, Mining Safety Standards, Electric Commercial Vehicle Policy Framework, Make in India and Localization Initiatives)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Competition Ecosystem

- By Market Value (2020-2025)
- By New Dump Truck and Tipper Unit Sales (2020-2025)
- By On-Road Tipper Unit Sales (2020-2025)
- By Off-Highway Dump Truck Unit Sales (2020-2025)
- By Mining Dump Truck Unit Sales (2020-2025)
- By Electric Dump Truck Unit Sales (2020-2025)

- By Dump Truck Type (In Value %)
Standard Rear Tippers
Rock Body Tippers
Box Body Tippers
Mining Tippers
Construction Tippers
Coal Carriers
Rigid Off-Highway Dump Trucks
Wide-Body Mining Trucks
Articulated Dump Trucks
Electric Mining Dump Trucks
Heavy Mining Haul Trucks
Specialized Dump Trucks - By Gross Vehicle Weight and Payload Capacity (In Value %)
Below 19 Ton GVW
19–28 Ton GVW
28–35 Ton GVW
35–42 Ton GVW
42–55 Ton GVW
55–75 Ton Payload
75–100 Ton Payload
100–150 Ton Payload
150–200 Ton Payload
Above 200 Ton Payload - By Application Type (In Value %)
Road and Highway Construction
Expressway Construction
Urban Infrastructure Construction
Railway and Metro Construction
Dam and Irrigation Projects
Earthmoving and Site Development
Coal Mining
Iron Ore Mining
Bauxite Mining
Limestone Mining
Metal and Mineral Mining
Stone Quarrying
Sand and Aggregate Transportation
Cement and Limestone Haulage
Steel and Raw Material Transportation
Port and Industrial Infrastructure
Tunnel and Hydropower Construction
Municipal and Public Works - By Powertrain Type (In Value %)
Diesel Internal Combustion Dump Trucks
High-Horsepower Diesel Mining Trucks
Automated Manual Transmission Tippers
Automatic Transmission Mining Tippers
Diesel-Electric Mining Haul Trucks
Battery Electric Dump Trucks
Battery Electric Mining Trucks
Regenerative Braking Electric Mining Trucks
Alternative-Fuel Tippers
Hydrogen-Ready and Emerging Powertrain Dump Trucks - By Sales Channel (In Value %)
OEM Direct Sales
Authorized Commercial Vehicle Dealers
Construction and Mining Equipment Dealers
Fleet Direct Procurement
Mining Company Tender Procurement
Government and PSU Procurement
Infrastructure Contractor Procurement
Equipment Rental and Leasing Companies
Independent Used Commercial Vehicle Dealers
Used Mining Equipment Dealers
Equipment Auction Channels
Digital Commercial Vehicle Platforms - By Region (In Value %)
North India
West India
South India
East India
Central India
Jharkhand-Odisha Mineral Belt
Chhattisgarh Coal and Iron Ore Belt
Madhya Pradesh Mining and Infrastructure Corridor
Rajasthan Mining and Quarrying Belt
Maharashtra Infrastructure and Industrial Corridor
Gujarat Industrial and Port Corridor
Karnataka Iron Ore and Infrastructure Belt
Telangana-Andhra Pradesh Mining and Construction Corridor
Tamil Nadu Construction and Quarrying Cluster
Northeast Infrastructure Development Corridor

- Market Share of Major Players (By Revenue, Unit Sales, On-Road Tippers, Mining Dump Trucks, Payload Class, Mining Application, Construction Application, Regional Presence)
- Cross Comparison Parameters (On-Road Tipper and Off-Highway Mining Dump Truck Portfolio Breadth, GVW Payload and Multi-Axle Configuration Coverage, Coal Iron Ore Quarry and Infrastructure Application Capability, High-Horsepower Engine AMT Automatic and Electric Drivetrain Capability, India Manufacturing Localization and Mining Equipment Production Footprint, Dealer Parts Field-Service and Fleet-Uptime Support Network, Electric Mining Truck Telematics Safety and Connected-Fleet Technology Readiness, PSU Mining Infrastructure Contractor and Large-Fleet Relationship Strength)
- SWOT Analysis of Major Players
- Competitive Positioning Matrix
- Pricing and Distribution Network Benchmarking
- Detailed Profiles of Major Companies
Tata Motors Ltd. – Prima and Signa Construction Tippers / Mining Tippers / Electric Tipper Platforms
Ashok Leyland Ltd. – AVTR Modular Tippers / Mining and Construction Tippers
Daimler India Commercial Vehicles Pvt. Ltd. – BharatBenz Heavy-Duty Construction and Mining Tippers
VE Commercial Vehicles Ltd. – Eicher Pro Heavy-Duty Tippers / Volvo Trucks Mining Solutions
Volvo Trucks India – FMX Mining and Construction Tippers / Heavy-Haul Applications
Scania Commercial Vehicles India Pvt. Ltd. – Heavy Mining Tippers / Off-Road Haulage Solutions
BEML Limited – Indigenous Rigid Dump Trucks / Electric Mining Dump Trucks / Mining Equipment
Komatsu India Pvt. Ltd. – Rigid Mining Dump Trucks / Electric Drive Mining Trucks
Caterpillar India Pvt. Ltd. – Off-Highway Dump Trucks / Rigid Mining Trucks / Mine Fleet Technology
SANY Heavy Industry India Pvt. Ltd. – Wide-Body Mining Dump Trucks / Electric Open-Cast Mining Trucks
Mahindra & Mahindra Ltd. – BLAZO X Heavy-Duty Construction and Mining Tippers
AMW Motors Ltd. – Heavy-Duty Tipper and Mining Truck Platforms
Action Construction Equipment Ltd. – Construction and Material-Handling Equipment / Emerging Heavy Equipment Applications
LiuGong India Pvt. Ltd. – Mining and Quarry Equipment / Heavy Material-Handling Solutions
XCMG India – Mining Dump Trucks / Wide-Body Haulage and Construction Equipment

- Dump Truck Fleet Buyer Segmentation
- Mining Fleet Procurement Behaviour
- Infrastructure Contractor Procurement Behaviour
- Dump Truck OEM and Dealer Selection Criteria
- Fleet Buyer and Operator Pain Points
- Payload, GVW and Powertrain Adoption Assessment
- Replacement, Rental and Repurchase Behaviour

- By Market Value (2026-2035)
- By New Dump Truck and Tipper Unit Sales (2026-2035)
- By On-Road Tipper Unit Sales (2026-2035)
- By Off-Highway Dump Truck Unit Sales (2026-2035)
- By Mining Dump Truck Unit Sales (2026-2035)
- By Electric Dump Truck Unit Sales (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
