
 Download PDF
Market Overview
The India Plastic Pipes and Fittings Market is valued at approximately USD ~XX billion, supported by rising demand from residential construction, agricultural irrigation networks, municipal water supply projects, and industrial applications. The market growth is driven by increasing replacement of traditional metal piping systems with lightweight and corrosion-resistant plastic alternatives. According to industry sources, plastic pipe consumption has expanded due to infrastructure investments, urban housing development, and government-led water connectivity programs. The market witnessed steady expansion based on increased PVC, CPVC, and HDPE pipe adoption.
The India Plastic Pipes and Fittings Market is concentrated across major industrial and construction hubs including Maharashtra, Gujarat, Tamil Nadu, Karnataka, Telangana, Uttar Pradesh, and Rajasthan due to strong manufacturing presence, agricultural activity, and infrastructure development. Cities such as Mumbai, Pune, Ahmedabad, Chennai, Bengaluru, Hyderabad, and Delhi NCR act as major demand centers because of residential construction growth, commercial projects, water management requirements, and established distribution networks. These regions dominate due to proximity to raw material suppliers, manufacturing facilities, and large end-user markets.
Market Segmentation
By Material Type
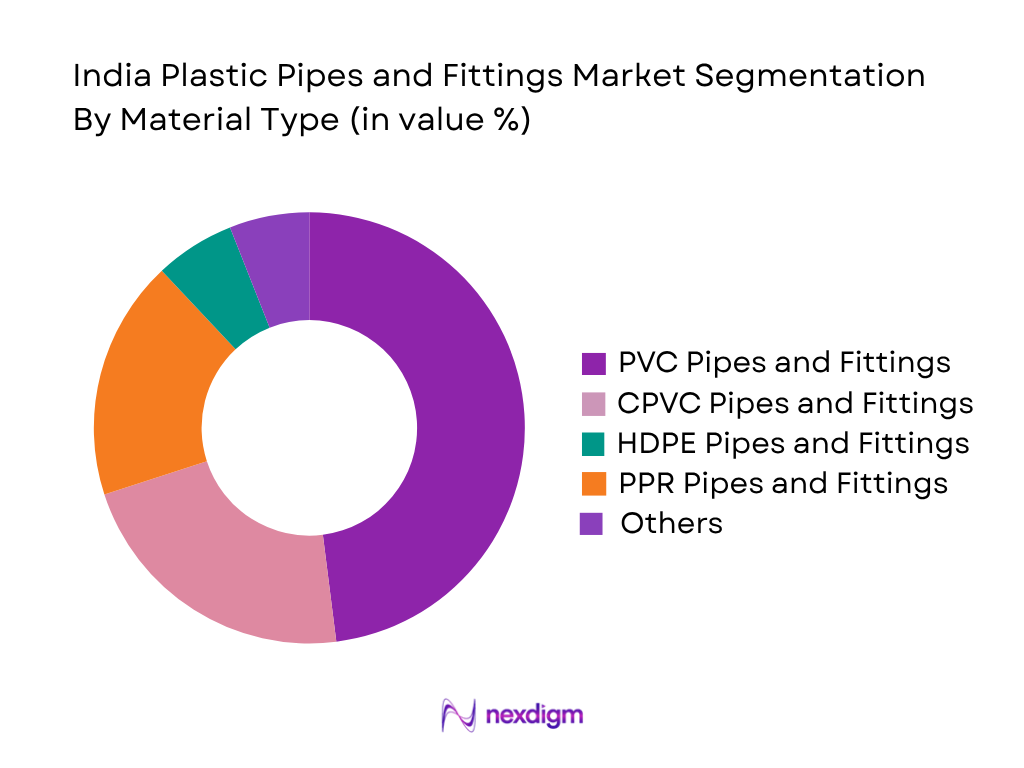
The India Plastic Pipes and Fittings Market is segmented by material type into PVC pipes and fittings, CPVC pipes and fittings, HDPE pipes and fittings, PPR pipes and fittings, LDPE pipes and fittings, and composite plastic piping systems. PVC pipes and fittings hold a dominant market position due to their extensive usage in agricultural irrigation, water supply systems, drainage applications, and residential plumbing. The segment benefits from established manufacturing infrastructure, cost competitiveness, availability of raw materials, and widespread acceptance among contractors and farmers. CPVC is increasingly adopted in residential plumbing applications due to heat resistance and durability, while HDPE continues gaining traction in infrastructure and industrial applications because of flexibility and high-pressure performance.
By Application
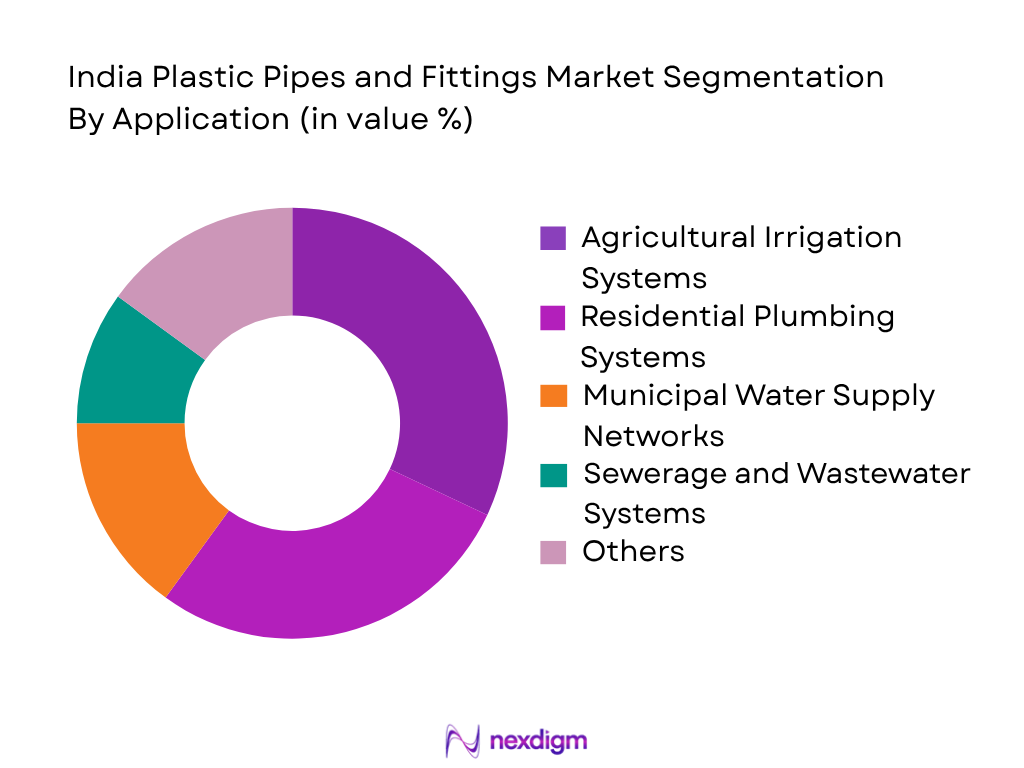
The India Plastic Pipes and Fittings Market is segmented by application into agricultural irrigation systems, residential plumbing systems, municipal water supply networks, sewerage and wastewater systems, industrial process piping, drainage systems, and telecom and electrical conduit applications. Agricultural irrigation represents a dominant application segment due to extensive usage of PVC and HDPE pipes in drip irrigation, groundwater transportation, and farm water management systems. Government initiatives supporting irrigation modernization and rural water infrastructure have increased demand for plastic piping solutions. Residential plumbing is another major application due to urbanization, housing development, and increasing preference for CPVC-based plumbing systems. Infrastructure projects including water supply networks and wastewater management systems continue creating long-term demand opportunities.
Competitive Landscape
The India Plastic Pipes and Fittings Market is characterized by the presence of organized manufacturers with diversified product portfolios across PVC, CPVC, HDPE, and specialized piping solutions. Major companies including Astral Limited, Supreme Industries, Finolex Industries, Prince Pipes and Fittings, and Jain Irrigation Systems have established strong market presence through extensive manufacturing capabilities, dealer networks, product certifications, and application-specific solutions. The competitive environment is influenced by product innovation, distribution expansion, manufacturing scale, and ability to serve infrastructure, agriculture, and construction sectors.
| Company | Establishment Year | Headquarters | Major Product Portfolio | Manufacturing Capability | Key Application Focus | Distribution Strength | Certification Coverage | Market Presence |
| Astral Limited | 1996 | Ahmedabad, Gujarat | ~ | ~ | ~ | ~ | ~ | ~ |
| Supreme Industries Limited | 1942 | Mumbai, Maharashtra | ~ | ~ | ~ | ~ | ~ | ~ |
| Finolex Industries Limited | 1981 | Pune, Maharashtra | ~ | ~ | ~ | ~ | ~ | ~ |
| Prince Pipes and Fittings Limited | 1987 | Mumbai, Maharashtra | ~ | ~ | ~ | ~ | ~ | ~ |
| Jain Irrigation Systems Limited | 1986 | Jalgaon, Maharashtra | ~ | ~ | ~ | ~ | ~ | ~ |
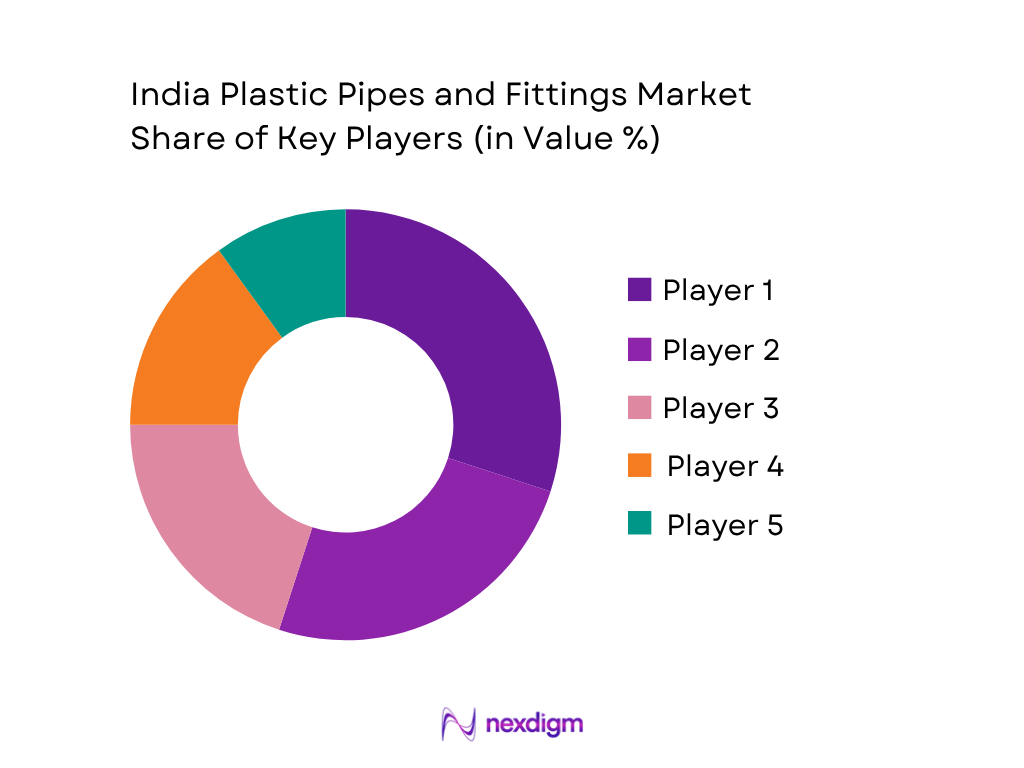
India Plastic Pipes and Fittings Market Analysis
Growth Drivers
Expansion of Water Infrastructure and Government-Led Piped Water Supply Programs
The India Plastic Pipes and Fittings Market is being supported by the expansion of water infrastructure projects, particularly through government initiatives focused on improving household water connectivity and municipal water distribution networks. The Ministry of Jal Shakti reported that more than 15 crore rural households had access to tap water connections under the Jal Jeevan Mission, creating continuous demand for PVC, HDPE, and CPVC piping systems used in water transportation networks. According to the World Bank, India’s urban population reached more than 518 million people, increasing pressure on cities to expand water supply, drainage, and wastewater infrastructure. The Ministry of Housing and Urban Affairs has also continued infrastructure development through urban water management programs, supporting demand for large-diameter plastic pipes in municipal applications. Increasing investments in rural and urban water connectivity are encouraging the adoption of lightweight, corrosion-resistant, and easy-to-install plastic piping solutions. The expansion of water supply networks, wastewater treatment facilities, and infrastructure modernization projects is expected to strengthen demand for plastic pipes and fittings across residential, municipal, and industrial applications.
Rising Construction Activity and Increasing Adoption of Modern Plumbing Systems
The India Plastic Pipes and Fittings Market is benefiting from continued construction activity and rising demand for modern plumbing solutions across residential, commercial, and infrastructure developments. The Ministry of Statistics and Programme Implementation reported continued expansion in India’s construction-related economic activity, supported by infrastructure development and real estate projects. According to the World Bank, India’s GDP reached approximately USD 3.9 trillion, reflecting broader economic expansion supporting investment in housing, commercial buildings, and industrial facilities. The Ministry of Housing and Urban Affairs has highlighted increasing urban development requirements as cities expand and require improved water supply, sanitation, and drainage systems. Plastic pipes such as CPVC, PVC, and PPR are increasingly preferred in modern buildings due to durability, corrosion resistance, and ease of installation compared with traditional metal alternatives. The growth of organized residential development, affordable housing projects, and commercial construction is increasing demand for plumbing-grade plastic pipes and fittings. Expansion of building infrastructure and adoption of standardized plumbing systems continue to create opportunities for manufacturers supplying application-specific piping solutions.
Market Challenges
Volatility in Polymer Raw Material Supply and Dependence on Petrochemical Feedstock
The India Plastic Pipes and Fittings Market faces challenges due to fluctuations in the availability and pricing stability of polymer raw materials, particularly PVC resin and polyethylene-based materials. Plastic pipe manufacturing depends heavily on petrochemical-derived polymers, making the industry sensitive to changes in global crude oil supply conditions and petrochemical production trends. According to the International Energy Agency, global oil demand remained above 100 million barrels per day, highlighting the continued dependence of polymer industries on petroleum-based feedstock. India imported approximately 85% of its crude oil requirements, according to government energy statistics, creating exposure to international commodity supply conditions. Changes in crude oil availability, global petrochemical capacity, and import dependency can influence raw material procurement conditions for pipe manufacturers. These challenges are particularly significant for manufacturers operating in price-sensitive agricultural and infrastructure segments where material cost fluctuations affect procurement decisions. Managing raw material security, improving supply chain efficiency, and increasing domestic polymer production capacity remain important requirements for maintaining stability in the plastic pipes and fittings industry.
Competition from Unorganized Manufacturers and Quality Standardization Issues
The India Plastic Pipes and Fittings Market experiences challenges from the presence of numerous regional and unorganized manufacturers competing primarily through pricing strategies. The fragmented nature of the market creates differences in product quality, manufacturing standards, and compliance levels across suppliers. The Bureau of Indian Standards has established specifications for plastic piping products including PVC and HDPE pipes to improve quality consistency and consumer safety. However, enforcement and awareness remain important factors, particularly in smaller regional markets where buyers may prioritize lower acquisition costs. According to government statistics, India’s Micro, Small and Medium Enterprises sector includes more than 6 crore registered enterprises, reflecting the large base of small-scale manufacturing and distribution businesses operating across industries. In plastic piping, this fragmented ecosystem creates competitive pressure for organized manufacturers investing in certifications, technology upgrades, and dealer networks. Maintaining product reliability, ensuring compliance with standards, and improving customer awareness regarding certified piping solutions remain key challenges for industry participants.
Market Opportunities
Expansion of Agricultural Irrigation and Water Management Infrastructure
The India Plastic Pipes and Fittings Market has significant opportunities from increasing demand for efficient agricultural water management systems. Agriculture remains a major water-consuming sector in India, creating demand for PVC and HDPE pipes used in irrigation, groundwater transportation, and farm water distribution. According to the Ministry of Agriculture and Farmers Welfare, India has more than 140 million hectares of agricultural land under cultivation, supporting continued requirements for irrigation infrastructure. The Ministry of Jal Shakti has emphasized improving water-use efficiency through irrigation modernization and conservation programs. Micro-irrigation systems, including drip and sprinkler networks, require durable plastic piping solutions for efficient water delivery. Government initiatives supporting agricultural productivity and water conservation are encouraging farmers and irrigation contractors to adopt modern piping systems. Expansion of irrigation coverage, replacement of traditional irrigation channels, and increasing adoption of water-efficient farming practices are creating long-term opportunities for plastic pipe manufacturers focused on agricultural applications.
Growth of Wastewater Management and Sustainable Infrastructure Development
The India Plastic Pipes and Fittings Market is expected to benefit from increasing focus on wastewater management, sanitation infrastructure, and sustainable urban development. Municipalities and industrial facilities are expanding wastewater treatment and drainage networks, creating demand for durable plastic piping systems such as HDPE and PVC pipes. The Ministry of Housing and Urban Affairs has continued implementation of urban sanitation and wastewater improvement programs through initiatives focused on improving sewage infrastructure. According to the World Bank, India’s urban population is expected to continue expanding, increasing the requirement for efficient water and wastewater management systems. Plastic pipes provide advantages in underground applications due to corrosion resistance, lightweight properties, and longer service life. Industrial sectors including manufacturing, chemical processing, and water treatment facilities are also adopting specialized plastic piping systems for fluid transportation requirements. Increasing emphasis on sustainable infrastructure, efficient water management, and modernization of urban utilities is creating opportunities for advanced plastic pipe solutions across municipal and industrial applications.
Future Outlook
Over the next decade, the India Plastic Pipes and Fittings Market is expected to demonstrate sustained growth driven by infrastructure development, increasing urbanization, agricultural modernization, and rising adoption of advanced piping systems. The market is expected to benefit from expansion of municipal water networks, wastewater treatment projects, residential construction, and industrial applications. Increasing preference for durable, lightweight, and corrosion-resistant piping solutions will further support market expansion. The market is projected to register a CAGR of approximately XX% during 2026-2035.
Major Players
- Astral Limited
- Supreme Industries Limited
- Finolex Industries Limited
- Prince Pipes and Fittings Limited
- Jain Irrigation Systems Limited
- Apollo Pipes Limited
- Skipper Limited
- Ashirvad Pipes
- Ori-Plast Limited
- Kisan Group
- Captain Pipes Limited
- Dutron Group
- Wavin India
- Rex Polyextrusion Limited
- Ashok PVC Pipes Private Limited
Key Target Audience
- Plastic Pipe and Fittings Manufacturers
- Building Material Manufacturers and Distribution Companies
- Real Estate Developers and Construction Companies Agricultural Irrigation Equipment Companies
- Infrastructure Development Companies
- Investments and Venture Capitalist Firms (Sequoia Capital India, Accel, Nexus Venture Partners)
- Government and Regulatory Bodies (Ministry of Jal Shakti, Bureau of Indian Standards, Ministry of Housing and Urban Affairs, Ministry of Agriculture and Farmers Welfare)
- Industrial Companies Using Process Piping Systems
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves developing a comprehensive ecosystem map covering polymer suppliers, plastic pipe manufacturers, distributors, contractors, infrastructure developers, and end-use industries. Extensive secondary research is conducted through industry databases, company reports, government publications, and sector-specific sources. The objective is to identify critical market variables including production capacity, consumption patterns, pricing trends, and application demand.
Step 2: Market Analysis and Construction
In this phase, historical market information related to plastic pipe production, consumption volume, application demand, and revenue contribution is analyzed. The assessment includes evaluation of PVC, CPVC, HDPE, and other thermoplastic pipe categories across agriculture, construction, infrastructure, and industrial applications. Market sizing is developed using demand-side and supply-side assessment frameworks.
Step 3: Hypothesis Validation and Expert Consultation
Market assumptions are validated through primary interviews with manufacturers, distributors, contractors, industry professionals, and project stakeholders. These discussions provide operational insights related to production capacity, pricing structures, competitive positioning, and demand trends. Expert inputs are integrated to refine market estimates and validate industry dynamics.
Step 4: Research Synthesis and Final Output
The final stage involves consolidating insights from primary and secondary research to develop a comprehensive market assessment. Information related to product categories, competitive landscape, consumer demand, regulatory environment, and future opportunities is analyzed. The findings are verified through cross-validation techniques to ensure accuracy and reliability.

- Executive Summary
- Research Methodology (Market Definition and Scope, India Plastic Pipes and Fittings Market Classification, Thermoplastic Pipe Demand Assessment, Plastic Pipe Production Volume Analysis, Plastic Fittings Consumption Mapping, PVC Pipe Demand Assessment, CPVC Pipe Adoption Assessment, HDPE Pipe Consumption Analysis, PPR Pipe Demand Evaluation, PE Pipe Application Mapping, Agricultural Irrigation Pipe Requirement Assessment, Residential Plumbing Pipe Consumption Analysis, Real Estate Construction Plumbing Demand Assessment, Municipal Water Supply Pipe Requirement Analysis, Sewerage and Wastewater Infrastructure Pipe Demand Assessment, Industrial Piping System Requirement Analysis, Primary Industry Interviews, Secondary Research Framework, Market Sizing Approach, Top-Down Analysis, Bottom-Up Analysis, Data Triangulation, Forecasting Framework, Assumptions and Limitations)

- Definition and Scope
- India Plastic Pipes and Fittings Industry Evolution and Development of Thermoplastic Piping Infrastructure
- PVC Pipes, CPVC Pipes, HDPE Pipes, MDPE Pipes, PPR Pipes, LDPE Pipes, Composite Pipes, Underground Drainage Pipes, Agricultural Irrigation Pipes, Plumbing Systems
- India Plastic Pipes and Fittings Value Chain Analysis
- India Plastic Pipes and Fittings Supply Chain Analysis
- Polymer Resin Supplier, PVC Compound Manufacturer, Pipe Extruder, Injection Moulding Manufacturer, Pipe and Fittings Distributor, Dealer Network, Plumbing Contractor, Infrastructure Developer, Government Utility End User
- Plastic Pipe Integration Across Agricultural Irrigation Systems, Residential Plumbing Networks, Commercial Buildings, Industrial Facilities, Municipal Water Distribution Networks, Sewerage Infrastructure, Gas Distribution Networks, Drainage Systems and Telecom Duct Infrastructure

- Growth Drivers (Jal Jeevan Mission Expansion, Agricultural Irrigation Development, Rising Residential Construction Activity, Urbanization Growth, Sewerage Infrastructure Expansion, Replacement of Metal Pipes, Increasing CPVC Adoption, Government Infrastructure Investment, Smart City Development, Industrial Manufacturing Growth, Real Estate Expansion, Demand for Corrosion Resistant Piping Systems)
- Market Challenges (Volatility in PVC Resin Prices, Dependency on Petrochemical Feedstock, Competition from Unorganized Manufacturers, Price-Based Market Competition, Quality Variation Across Regional Manufacturers, Skilled Plumbing Workforce Availability, Installation Quality Issues, Environmental Concerns Related to Plastic Waste Management, Raw Material Supply Fluctuation)
- Market Opportunities (Rural Water Infrastructure Expansion, Large Diameter HDPE Pipe Adoption, Wastewater Treatment Infrastructure Growth, Industrial Piping Applications, Export Market Expansion, Sustainable Plastic Pipe Manufacturing, Recycled Polymer Adoption, Digital Distribution Expansion, Smart Water Infrastructure Development, Advanced Fittings Adoption)
- Market Trends (Increasing CPVC Plumbing Penetration, Premiumization of Plumbing Systems, HDPE Fusion Technology Adoption, Expansion of Large Diameter Pipes, Organized Player Market Consolidation, Dealer Network Digitization, Sustainable Polymer Solutions, Prefabricated Plumbing Systems, Infrastructure-Led Demand Growth, Product Portfolio Expansion)
- Regulatory and Standards Landscape (BIS Plastic Pipe Standards, IS 4984 HDPE Pipe Standards, IS 4985 PVC Pipe Standards, IS 15778 CPVC Pipe Standards, Plumbing Code Requirements, Jal Jeevan Mission Guidelines, Plastic Waste Management Rules, Quality Certification Requirements, Infrastructure Project Specifications)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Competition Ecosystem

- By Market Value (2020-2025)
- By Plastic Pipe Consumption Volume (2020-2025)
- By Plastic Fittings Consumption Volume (2020-2025)
- By PVC Pipe Consumption Volume (2020-2025)
- By CPVC Pipe Consumption Volume (2020-2025)
- By HDPE Pipe Consumption Volume (2020-2025)
- By PPR Pipe Consumption Volume (2020-2025)

- By Material Type (In Value %)
PVC Pipes and Fittings
CPVC Pipes and Fittings
HDPE Pipes and Fittings
MDPE Pipes and Fittings
PPR Pipes and Fittings
LDPE Pipes and Fittings
Polyethylene Composite Pipes and Fittings
Multilayer Composite Pipes
Specialty Thermoplastic Pipes - By Product Type (In Value %)
Pressure Pipes
Non-Pressure Pipes
Agricultural Pipes
Plumbing Pipes
Sewerage Pipes
Drainage Pipes
Corrugated Pipes
Solid Wall Pipes
Flexible Pipes and Tubing
Injection Molded Fittings
Fabricated Fittings
Compression Fittings
Electrofusion Fittings
Threaded and Solvent Weld Fittings - By Application Type (In Value %)
Agricultural Irrigation Systems
Residential Plumbing Systems
Commercial Building Plumbing Systems
Municipal Water Supply Networks
Sewerage and Wastewater Management Systems
Industrial Process Piping Systems
Oil and Gas Distribution Systems
Stormwater Drainage Systems
Electrical Conduit Systems
Telecommunication Duct Systems
Fire Protection Systems
Water Treatment Infrastructure
Mining and Industrial Slurry Transportation Systems - By End-Use Industry (In Value %)
Agriculture Sector
Residential Construction Sector
Commercial Construction Sector
Real Estate Development Sector
Municipal Water Utilities
Wastewater Treatment Utilities
Industrial Manufacturing Facilities
Oil and Gas Utilities
Infrastructure Development Projects
Telecommunication Infrastructure
Healthcare Facilities
Educational Institutions
Government Water Supply Projects - By Region (In Value %)
North India
South India
West India
East India
Central India

- Market Share of Major Players (By India Revenue, Plastic Pipe Sales Volume, Plastic Fittings Sales Volume, PVC Pipe Sales Volume, CPVC Pipe Sales Volume, HDPE Pipe Sales Volume, Agricultural Pipe Sales Volume, Plumbing Pipe Sales Volume, Manufacturing Capacity, Distribution Network Coverage, Product Portfolio Breadth, BIS Certification Coverage)
- Cross Comparison Parameters (India Plastic Pipe and Fittings Revenue, Material Portfolio Breadth Across PVC-CPVC-HDPE-PPR, Pipe Extrusion and Injection Moulding Capacity, Large Diameter Pipe Manufacturing Capability, Agricultural and Irrigation Market Presence, Plumbing and Building Material Network Strength, Joining Technology Portfolio, BIS Certification and Quality Compliance Coverage)
- SWOT Analysis of Major Players
- Competitive Positioning Matrix
- Detailed Profiles of Major Companies
Astral Limited
Supreme Industries Limited
Finolex Industries Limited
Prince Pipes and Fittings Limited
Jain Irrigation Systems Limited
Ashirvad Pipes
Apollo Pipes Limited
Skipper Limited
Ori-Plast Limited
Kisan Group
Captain Pipes Limited
Dutron Group
Wavin India
Rex Polyextrusion Limited
Ashok PVC Pipes Private Limited

- Agricultural Consumer Plastic Pipe Procurement Assessment
- Municipal Water Utility Plastic Pipe Requirement Analysis
- Residential Builder Plumbing Material Selection Assessment
- Commercial Construction Plumbing Specification Analysis
- Industrial Facility Process Piping Requirement Assessment
- Real Estate Developer Plumbing System Preference Analysis
- Government Infrastructure Project Procurement Analysis
- Plumbing Contractor Material Preference Assessm

- By Market Value (2026-2035)
- By Plastic Pipe Consumption Volume (2026-2035)
- By Plastic Fittings Consumption Volume (2026-2035)
- By PVC Pipe Consumption Volume (2026-2035)
- By CPVC Pipe Consumption Volume (2026-2035)
- By HDPE Pipe Consumption Volume (2026-2035)
- By PPR Pipe Consumption Volume (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
