
 Download PDF
Market Overview
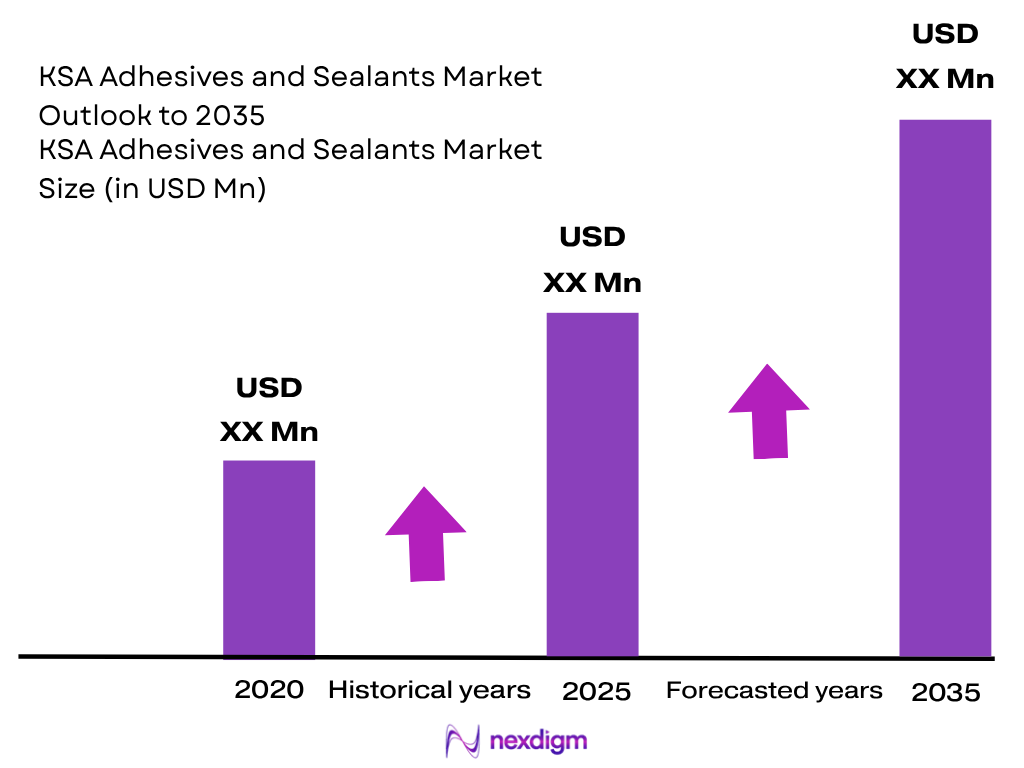
The KSA Adhesives and Sealants Market is valued at approximately USD ~ billion, based on historical industry analysis, supported by rising construction activity, infrastructure development, industrial manufacturing expansion, and increasing demand for advanced bonding and sealing solutions across Saudi Arabia. The market size is driven by demand from construction chemicals, oil and gas maintenance, packaging conversion, automotive assembly, petrochemical facilities, and industrial applications. Saudi Arabia’s expanding manufacturing ecosystem and localization initiatives under Vision 2030 continue to influence adhesive and sealant consumption patterns.
The KSA Adhesives and Sealants Market is concentrated across major economic and industrial regions, including Riyadh, Eastern Province, and Western Province. Riyadh dominates due to large-scale infrastructure development, commercial construction projects, government facilities, and industrial expansion. Eastern Province represents a significant demand center due to oil and gas operations, petrochemical complexes, and industrial facilities. Western Province contributes through construction activities, hospitality projects, infrastructure development, and manufacturing applications linked with major urban centers.
Market Segmentation
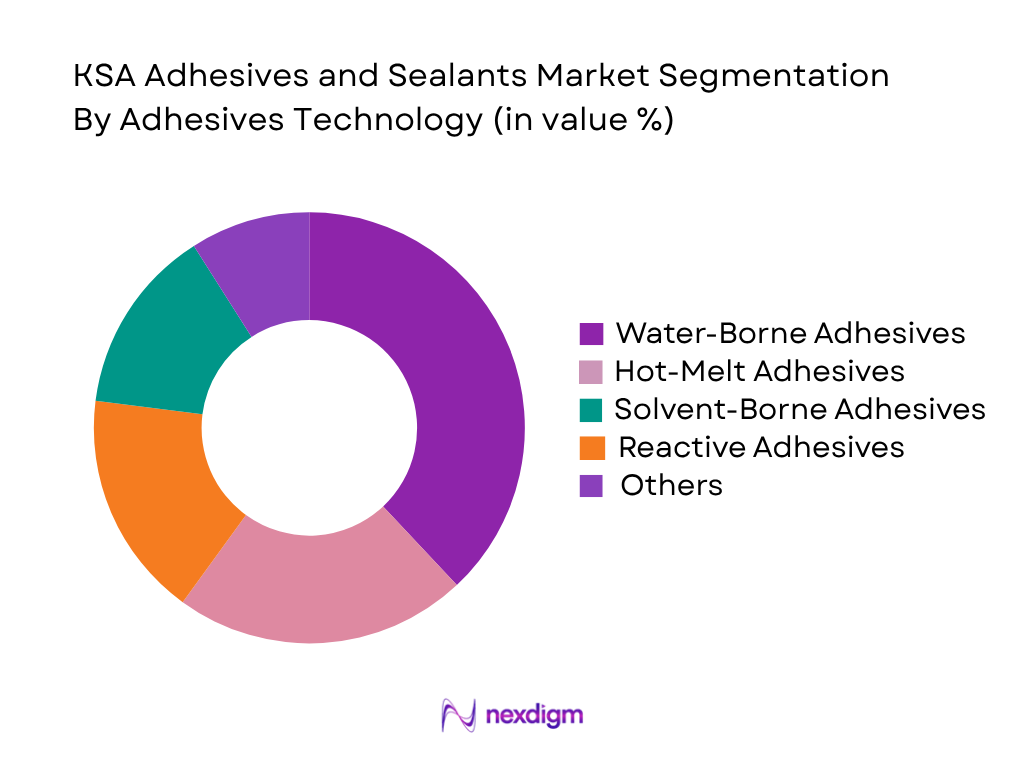
By Adhesive Technology
The KSA Adhesives and Sealants Market is segmented by adhesive technology into water-borne adhesives, solvent-borne adhesives, reactive adhesives, hot-melt adhesives, pressure-sensitive adhesives, UV-cured adhesives, and structural adhesives. Recently, water-borne adhesives hold a dominant market share in Saudi Arabia due to their widespread usage in packaging, woodworking, construction-related applications, and general industrial bonding. Their lower VOC characteristics, ease of application, and compatibility with multiple substrates have increased adoption among manufacturers seeking improved environmental compliance. Reactive and structural adhesive technologies are also gaining importance due to their application in automotive, industrial assembly, and high-performance construction bonding where durability and resistance properties are critical.
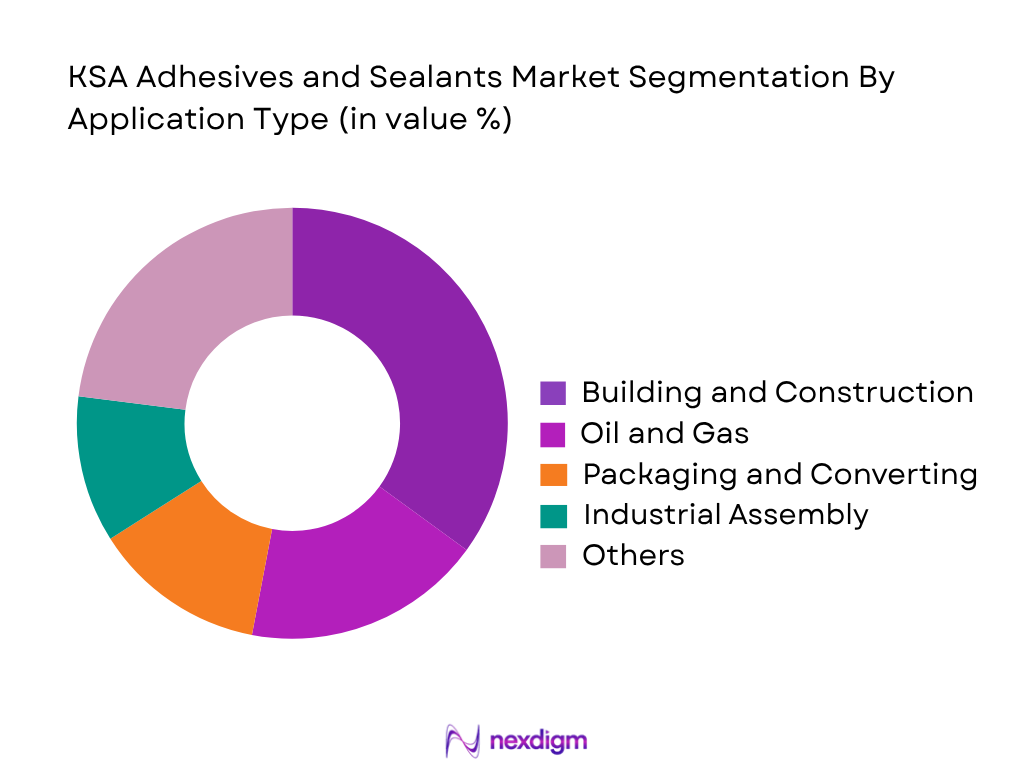
By Application Type
The KSA Adhesives and Sealants Market is segmented by application type into building and construction, oil and gas, petrochemical processing, packaging and converting, automotive and transportation, woodworking and furniture, electronics and electrical, industrial assembly, marine, and consumer applications. Recently, building and construction represents the dominant application segment in the KSA Adhesives and Sealants Market due to extensive infrastructure development, commercial real estate expansion, mega projects, and increasing adoption of construction chemical solutions. Adhesives and sealants are extensively used in flooring, glazing, waterproofing, insulation, facade systems, and structural applications. Oil and gas applications also represent a significant demand area due to sealing requirements in pipelines, processing facilities, and maintenance operations.
Competitive Landscape
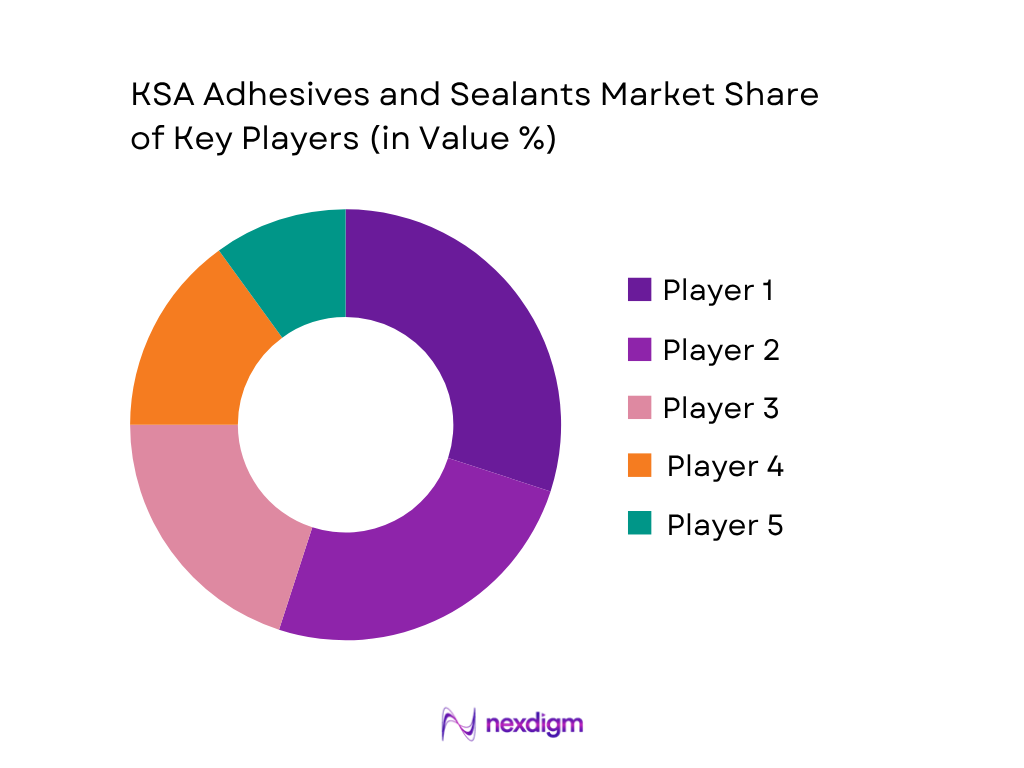
The KSA Adhesives and Sealants Market is characterized by the presence of multinational adhesive manufacturers, construction chemical companies, and specialty chemical suppliers. The competitive environment includes global players such as Henkel, Sika, H.B. Fuller, 3M, Dow, and Bostik, which compete through extensive product portfolios, technical support capabilities, distribution networks, and application-specific solutions. Regional suppliers and distributors also play an important role by providing localized supply capabilities for construction, industrial, and maintenance applications.
| Company | Establishment Year | Headquarters | Adhesive Technology Portfolio | Sealant Product Range | Major Application Focus | Saudi Market Presence | Distribution Capability | Technical Support Capability |
| Henkel | ~1876 | Germany | ~ | ~ | ~ | ~ | ~ | ~ |
| Sika | ~1910 | Switzerland | ~ | ~ | ~ | ~ | ~ | ~ |
| H.B. Fuller | ~1887 | USA | ~ | ~ | ~ | ~ | ~ | ~ |
| 3M | ~1902 | USA | ~ | ~ | ~ | ~ | ~ | ~ |
| Dow | ~1897 | USA | ~ | ~ | ~ | ~ | ~ | ~ |
KSA Adhesives and Sealants Market Analysis
Growth Drivers
Expansion of Construction and Infrastructure Development
The KSA Adhesives and Sealants Market is strongly influenced by Saudi Arabia’s construction and infrastructure expansion, where adhesives and sealants are essential for flooring systems, glazing, waterproofing, insulation, facade installation, and structural applications. Saudi Arabia’s construction activity is supported by large-scale urban development, transportation infrastructure, commercial buildings, and industrial facilities. According to the World Bank, Saudi Arabia’s GDP reached approximately USD 1.07 trillion in 2024, reflecting continued economic capacity to support infrastructure investment and industrial development. The Saudi government reported that the construction sector contributed approximately SAR 354 billion to GDP during 2024, demonstrating the sector’s importance within the national economy. Large-scale projects including urban developments, tourism infrastructure, industrial zones, and public facilities require advanced bonding and sealing solutions with improved durability and environmental performance. The Saudi Building Code framework and increasing adoption of modern construction practices are also encouraging the use of specialized construction adhesives and sealants instead of traditional mechanical fastening methods. This infrastructure-driven demand creates significant opportunities for manufacturers supplying silicone sealants, polyurethane systems, epoxy adhesives, and structural bonding technologies across residential, commercial, and industrial construction applications.
Growth of Oil and Gas, Petrochemical, and Industrial Manufacturing Applications
The KSA Adhesives and Sealants Market benefits significantly from the country’s extensive oil and gas ecosystem, petrochemical production base, and industrial manufacturing expansion. Adhesives and sealants are widely used in pipeline maintenance, equipment assembly, corrosion protection, insulation systems, machinery bonding, and industrial facility maintenance. Saudi Arabia produced approximately 9 million barrels per day of crude oil during 2024, according to the International Energy Agency, maintaining its position as one of the world’s largest oil producers. The country also continued expanding industrial activities through localization programs focused on chemicals, manufacturing, and downstream industries. According to the General Authority for Statistics, Saudi Arabia’s industrial production index remained supported by mining, manufacturing, and energy-related activities during 2024, highlighting continued industrial demand. Petrochemical facilities, processing plants, and manufacturing units require high-performance adhesives and sealants capable of withstanding temperature variation, chemical exposure, and mechanical stress. Increasing industrial diversification under Vision 2030 is encouraging growth in automotive components, machinery production, renewable energy equipment, and advanced manufacturing facilities, supporting demand for specialty adhesive technologies and industrial sealing solutions.
Market Challenges
Dependence on Imported Specialty Raw Materials and Advanced Adhesive Technologies
The KSA Adhesives and Sealants Market faces challenges due to reliance on imported specialty chemicals, resin systems, additives, and advanced formulation technologies required for high-performance adhesive and sealant production. Although Saudi Arabia has a strong petrochemical industry, many specialized adhesive inputs such as modified polymers, specialty resins, and performance additives continue to depend on international supply chains. According to the General Authority for Statistics, Saudi Arabia recorded merchandise imports exceeding SAR 800 billion in 2024, reflecting the country’s continued dependence on imported industrial goods and specialized materials. Adhesive manufacturers using polyurethane, epoxy, silicone, and hybrid polymer technologies require consistent access to high-quality chemical inputs to maintain product performance standards. Supply chain disruptions, international logistics fluctuations, and availability constraints can impact manufacturing continuity and product availability. Additionally, local manufacturers face technical challenges in developing advanced formulations suitable for demanding applications such as oil and gas, automotive assembly, and industrial equipment manufacturing. Strengthening domestic chemical processing capabilities and increasing localized production of specialty materials remain important factors influencing the future development of the Saudi adhesive and sealant ecosystem.
Environmental Compliance and Demand for Sustainable Formulations
The KSA Adhesives and Sealants Market is increasingly affected by environmental regulations and the transition toward sustainable chemical solutions. Adhesive manufacturers are facing growing requirements to develop low-VOC, environmentally compliant, and safer formulations for construction, industrial, and consumer applications. Saudi Arabia has strengthened environmental governance through initiatives led by the National Center for Environmental Compliance and sustainability programs under Vision 2030. According to the World Bank, Saudi Arabia’s urban population exceeded 30 million people in 2024, increasing demand for sustainable buildings, improved indoor air quality standards, and environmentally responsible construction materials. Traditional solvent-based adhesives may face limitations due to emissions and regulatory requirements, encouraging manufacturers to develop water-based, hybrid, and advanced polymer technologies. Construction companies and industrial users are increasingly seeking products that provide durability while meeting environmental performance requirements. The challenge for adhesive manufacturers is balancing technical performance, regulatory compliance, and application efficiency while adapting product portfolios toward sustainable solutions. This transition requires investment in formulation development, testing capabilities, and technical expertise across the Saudi market.
Market Opportunities
Localization of Adhesive and Sealant Manufacturing Through Industrial Development Programs
The KSA Adhesives and Sealants Market presents opportunities through increasing industrial localization and development of domestic manufacturing capabilities. Saudi Arabia’s industrial strategy focuses on expanding local production, reducing import dependency, and developing downstream chemical industries. According to the Ministry of Industry and Mineral Resources, Saudi Arabia had more than 11,000 industrial facilities registered in 2024, indicating a growing manufacturing ecosystem requiring industrial bonding and sealing solutions. The availability of petrochemical feedstocks from domestic producers provides opportunities for developing locally manufactured adhesive and sealant products based on polymer and chemical inputs. Growth in industrial cities, manufacturing clusters, and specialized production facilities is expected to increase demand for adhesives used in equipment assembly, packaging, construction materials, and engineered products. Local production capabilities can improve supply reliability, shorten delivery timelines, and support customized formulation development for Saudi-specific applications. Companies investing in regional formulation facilities, technical laboratories, and application support networks can benefit from increasing demand for specialized bonding technologies across construction, energy, transportation, and industrial manufacturing sectors.
Increasing Adoption of Advanced Bonding Solutions in Automotive, Renewable Energy, and Modern Construction
The KSA Adhesives and Sealants Market has significant opportunities from the adoption of advanced bonding technologies across emerging industrial sectors, including automotive manufacturing, renewable energy, and modern construction systems. Saudi Arabia is expanding non-oil industrial activities through investments in manufacturing and clean energy infrastructure. According to the International Renewable Energy Agency, Saudi Arabia had renewable energy projects totaling more than 2 GW of installed renewable capacity and operational projects during 2024, creating demand for durable adhesives and sealants in solar equipment, electrical components, and infrastructure applications. The automotive sector is also developing through localization initiatives and new manufacturing investments, increasing requirements for lightweight bonding solutions used in vehicle assembly, interiors, and electronic components. Modern construction practices are further increasing the use of structural adhesives, silicone sealants, and hybrid polymer systems for glazing, insulation, and energy-efficient buildings. These applications require products with high durability, temperature resistance, and long service life, creating opportunities for manufacturers offering advanced adhesive and sealant technologies tailored to industrial requirements.
Future Outlook
Over the next decade, the KSA Adhesives and Sealants Market is expected to demonstrate steady expansion driven by infrastructure investments, industrial localization initiatives, construction mega projects, and increasing adoption of advanced bonding technologies. Demand is expected to rise from construction chemicals, oil and gas maintenance, automotive manufacturing, packaging industries, and renewable energy infrastructure. The transition toward sustainable, low-VOC, and high-performance adhesive and sealant solutions is expected to influence future product development and market competition.
The KSA Adhesives and Sealants Market is forecasted to grow at a CAGR of ~% during 2026-2035, reaching a market size of approximately USD ~ billion by 2035. Growth will be supported by increasing construction activities, expansion of industrial manufacturing, demand for specialty sealants, and the development of localized chemical production capabilities. Saudi Arabia’s Vision 2030 industrial diversification initiatives are expected to create additional opportunities for adhesive and sealant manufacturers across multiple end-use sectors.
Major Players
- Henkel Saudi Arabia Limited
- Sika Saudi Arabia Limited
- H.B. Fuller Arabia Adhesives Company
- 3M Saudi Arabia Limited
- Dow Saudi Arabia Limited
- Bostik Saudi Arabia Limited
- Arkema Saudi Arabia Limited
- Wacker Chemicals Middle East FZE
- Mapei Saudi Arabia Limited
- Soudal Middle East FZE
- BASF Saudi Arabia Limited
- PPG Industries Saudi Arabia Limited
- RPM International Inc.
- Jowat Middle East FZE
- Permabond Engineering Adhesives
Key Target Audience
- Adhesive and sealant manufacturers (Henkel, Sika, H.B. Fuller, Dow, Bostik, 3M, Wacker Chemie)
- Construction chemical companies and building material manufacturers
- Oil and gas operators and service providers (Saudi Aramco, Saudi Basic Industries Corporation, oilfield maintenance contractors)
- Automotive manufacturers, component suppliers, and transportation companies
- Packaging manufacturers, flexible packaging converters, and industrial packaging companies
- Investments and venture capitalist firms (Public Investment Fund, Saudi Venture Capital Company, Jadwa Investment)
- Government and regulatory bodies (Saudi Standards, Metrology and Quality Organization, Ministry of Industry and Mineral Resources, Saudi Building Code National Committee)
- Industrial manufacturing companies, electronics manufacturers, and renewable energy equipment producers
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves developing a comprehensive ecosystem map covering all major stakeholders operating within the KSA Adhesives and Sealants Market. This process includes extensive secondary research through industry databases, company publications, trade statistics, chemical industry sources, and construction sector reports. The objective is to identify major market variables including adhesive technologies, resin categories, application industries, manufacturing capabilities, import dependency, and demand drivers.
Step 2: Market Analysis and Construction
In this phase, historical market information related to the KSA Adhesives and Sealants Market is collected and structured across multiple parameters including market value, consumption volume, technology adoption, application demand, and end-use industry contribution. The analysis includes evaluation of construction activity, oil and gas applications, industrial manufacturing requirements, packaging demand, and distribution channels to establish market sizing frameworks.
Step 3: Hypothesis Validation and Expert Consultation
Market assumptions and industry hypotheses are validated through discussions with industry participants, including adhesive manufacturers, construction chemical suppliers, distributors, contractors, industrial buyers, and application specialists. Computer-assisted telephone interviews (CATIs) and expert interactions are conducted to obtain operational insights related to pricing trends, product adoption, procurement behavior, and competitive positioning.
Step 4: Research Synthesis and Final Output
The final phase involves consolidating primary and secondary research findings to create a validated assessment of the KSA Adhesives and Sealants Market. Direct industry interactions are used to verify market segmentation, competitive analysis, customer preferences, technology adoption trends, and future growth opportunities. The final report integrates quantitative and qualitative insights to provide a comprehensive market outlook.

- Executive Summary
- Research Methodology (Market Definition and Scope, KSA Adhesives and Sealants Market Classification, Adhesive and Sealant Product Mapping, Resin-Level Assessment, Technology-Level Assessment, Application-Level Demand Analysis, End-Use Industry Assessment, Domestic Manufacturing Assessment, Import and Export Trade Analysis, Raw Material Supply Assessment, Petrochemical Feedstock Assessment, Demand-Side Assessment, Supply-Side Assessment, Top-Down Market Sizing, Bottom-Up Market Sizing, Primary Industry Interviews, Data Triangulation, Forecasting Framework, Market Share Validation, Limitations and Future Conclusions)

- Definition and Scope
- KSA Adhesives and Sealants Industry Evolution and Development of Saudi Adhesive Manufacturing, Construction Chemical Integration, Petrochemical-Based Raw Material Ecosystem and Industrial Application Infrastructure
- Adhesives and Sealants Value Chain Analysis
- Adhesives and Sealants Supply Chain Analysis
- Petrochemical Feedstock Suppliers, Resin Manufacturers, Adhesive Formulators, Sealant Manufacturers, Construction Chemical Companies, Industrial Distributors, OEM Suppliers, Infrastructure Developers, Oil and Gas Operators, End-Use Industries
- Adhesive Integration Across Building and Construction, Oil and Gas, Petrochemicals, Packaging, Automotive, Transportation, Woodworking, Electronics, Industrial Manufacturing and Consumer Applications
- Sealant Integration Across Building and Construction, Infrastructure Projects, Oil and Gas Facilities, Automotive Manufacturing, Glass and Fenestration, Industrial Equipment, Electronics and General Engineering Applications

- Growth Drivers (Saudi Vision 2030 Infrastructure Development, NEOM and Mega Project Construction Activities, Expansion of Construction Chemicals Demand, Oil and Gas Maintenance Requirements, Petrochemical Industry Growth, Automotive Manufacturing Localization, Packaging Industry Expansion, Industrial Manufacturing Development, Rising Demand for High-Performance Bonding and Sealing Systems)
- Market Challenges (High Dependence on Imported Specialty Adhesive Raw Materials, Petrochemical Feedstock Price Volatility, Limited Domestic Specialty Adhesive Production Capacity, Technology Transfer Requirements, Competition from International Suppliers, Environmental Compliance Requirements, Skilled Technical Application Requirements, Supply Chain Dependency)
- Market Opportunities (Localization of Adhesive and Sealant Manufacturing, Low-VOC and Sustainable Formulations, Green Building Material Adoption, Structural Adhesive Expansion, Oil and Gas Specialty Sealant Demand, Automotive Bonding Applications, Renewable Energy Infrastructure Applications, Advanced Construction Chemical Integration)
- Market Trends (Growth of Silicone and MS Polymer Sealants, Water-Borne Adhesive Adoption, Low-VOC Product Development, Hybrid Sealant Technology Growth, Structural Bonding Replacement of Mechanical Fasteners, High-Performance Construction Adhesives, Sustainable Chemical Solutions, Automated Adhesive Dispensing Systems, Specialty Industrial Bonding Applications)
- Government Regulations and Standards (Saudi Building Code Requirements, Saudi Standards Metrology and Quality Organization Regulations, Environmental Compliance Requirements, Chemical Import Regulations, Industrial Licensing Regulations, Construction Material Standards, Oil and Gas Industry Specifications, Product Safety and Labeling Requirements)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Competition Ecosystem

- By Market Value (2020-2025)
- By Market Volume (2020-2025)
- By Adhesives Consumption Volume (2020-2025)
- By Sealants Consumption Volume (2020-2025)
- By Domestic Production Volume (2020-2025)
- By Import Volume (2020-2025)
- By Export Volume (2020-2025)
- By Average Selling Price (2020-2025)

- By Adhesives Resin Type (In Value %)
Polyurethane Adhesives
Epoxy Adhesives
Acrylic Adhesives
Silicone Adhesives
Cyanoacrylate Adhesives
Ethylene Vinyl Acetate (EVA) Adhesives
Polyvinyl Acetate (PVAc) Adhesives
Modified Silane Polymer Adhesives
Other Adhesive Resins - By Adhesives Technology (In Value %)
Water-Borne Adhesives
Solvent-Borne Adhesives
Reactive Adhesives
Hot-Melt Adhesives
Pressure-Sensitive Adhesives
UV-Cured Adhesives
Structural Adhesives
Other Adhesive Technologies - By Sealants Resin Type (In Value %)
Silicone Sealants
Polyurethane Sealants
Polysulfide Sealants
Acrylic Sealants
MS Polymer Sealants
Hybrid Sealants
Epoxy Sealants
Other Sealant Resins - By Application Type (In Value %)
Building and Construction
Oil and Gas
Petrochemical Processing
Packaging and Converting
Automotive and Transportation
Industrial Assembly and Engineering
Woodworking and Furniture
Electronics and Electrical
Marine and Infrastructure
Consumer and Household Applications - By End-Use Industry (In Value %)
Construction Industry
Oil and Gas Industry
Petrochemical Industry
Packaging Industry
Automotive Industry
Furniture and Woodworking Industry
Electronics and Electrical Industry
Industrial Manufacturing Industry
Renewable Energy Industry
Infrastructure Development Industry - By Region (In Value %)
Central Region
Eastern Region
Western Region
Northern Region
Southern Region

- Market Share of Major Players (By KSA Revenue, Adhesives Sales Volume, Sealants Sales Volume, Resin Portfolio, Technology Portfolio, End-Use Industry Exposure, Manufacturing Presence, Import Distribution Capability, Regional Coverage, Industrial Customer Base, Product Certification Coverage, Technical Service Capability, Application Laboratory Support)
- Cross Comparison Parameters (Adhesives and Sealants Revenue, Adhesive Resin Portfolio Breadth, Sealant Technology Portfolio Breadth, Local Manufacturing and Formulation Capability, Petrochemical Raw Material Integration, Construction Application Coverage, Oil and Gas Application Expertise, Distribution Network Reach)
- SWOT Analysis of Major Players
- Competitive Positioning Matrix
- Adhesive Product Portfolio and Application Benchmarking
- Detailed Profiles of Major Companies
Henkel Saudi Arabia Limited
Sika Saudi Arabia Limited
H.B. Fuller Arabia Adhesives Company
3M Saudi Arabia Limited
Dow Saudi Arabia Limited
Bostik Saudi Arabia Limited
Arkema Saudi Arabia Limited
Wacker Chemicals Middle East FZE
Mapei Saudi Arabia Limited
Soudal Middle East FZE
RPM International Inc.
PPG Industries Saudi Arabia Limited
BASF Saudi Arabia Limited
Jowat Middle East FZE
Permabond Engineering Adhesives

- Construction Contractor Adhesive Procurement Assessment
- Infrastructure Developer Sealant Requirement Analysis
- Oil and Gas Operator Adhesive and Sealant Application Assessment
- Pipeline and Maintenance Sealant Requirement Analysis
- Petrochemical Facility Bonding and Sealing Requirement Analysis
- Automotive OEM Bonding and Sealant Requirement Analysis
- Automotive Component Manufacturer Adhesive Assessment
- Packaging Converter Adhesive Consumption Assessment
- Flexible Packaging Adhesive Application Assessment
- Corrugated Packaging Adhesive Requirement Analysis
- Furniture and Woodworking Adhesive Procurement Assessment
- Electronics and Electrical Assembly Adhesive Requirement Analysis
- Industrial Equipment Manufacturer Bonding Assessment
- Renewable Energy Component Adhesive Requirement Analysis

- By Market Value (2026-2035)
- By Market Volume (2026-2035)
- By Adhesives Consumption Volume (2026-2035)
- By Sealants Consumption Volume (2026-2035)
- By Domestic Production Volume (2026-2035)
- By Import Volume (2026-2035)
- By Export Volume (2026-2035)
- By Average Selling Price (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
