
 Download PDF
Market Overview
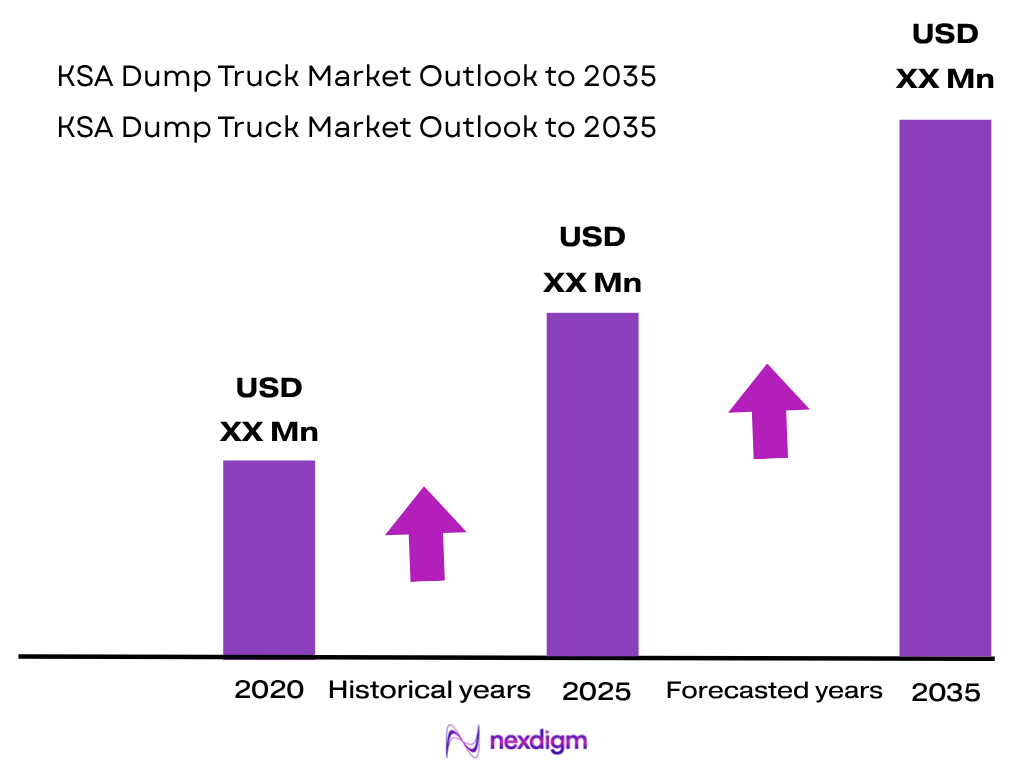
The KSA Dump Truck Market is valued at approximately ~USD XX million, based on historical market assessment, and is driven by giga-project construction, mining, quarrying and heavy-material movement. Saudi Arabia’s registered roadworthy vehicle base increased from 14.8 million vehicles to 15.8 million vehicles, while newly registered vehicles reached 1.026 million units from 878,100 units previously. The World Bank records Saudi GDP at USD 1,239.8 billion, supporting continued capital-intensive infrastructure and equipment demand.
Riyadh, Tabuk, Makkah and the Eastern Province represent the principal KSA Dump Truck Market demand centres because they combine large construction programmes, mining activity, logistics development and industrial investment. NEOM alone spans 26,500 square kilometres, while more than 100 active development sites operated across the project footprint, with 20 million cubic metres of earth excavated and 2.4 million cubic metres of concrete used during the latest reported annual period, supporting substantial requirements for construction tippers and off-highway haulers.
Market Segmentation
By Truck Type
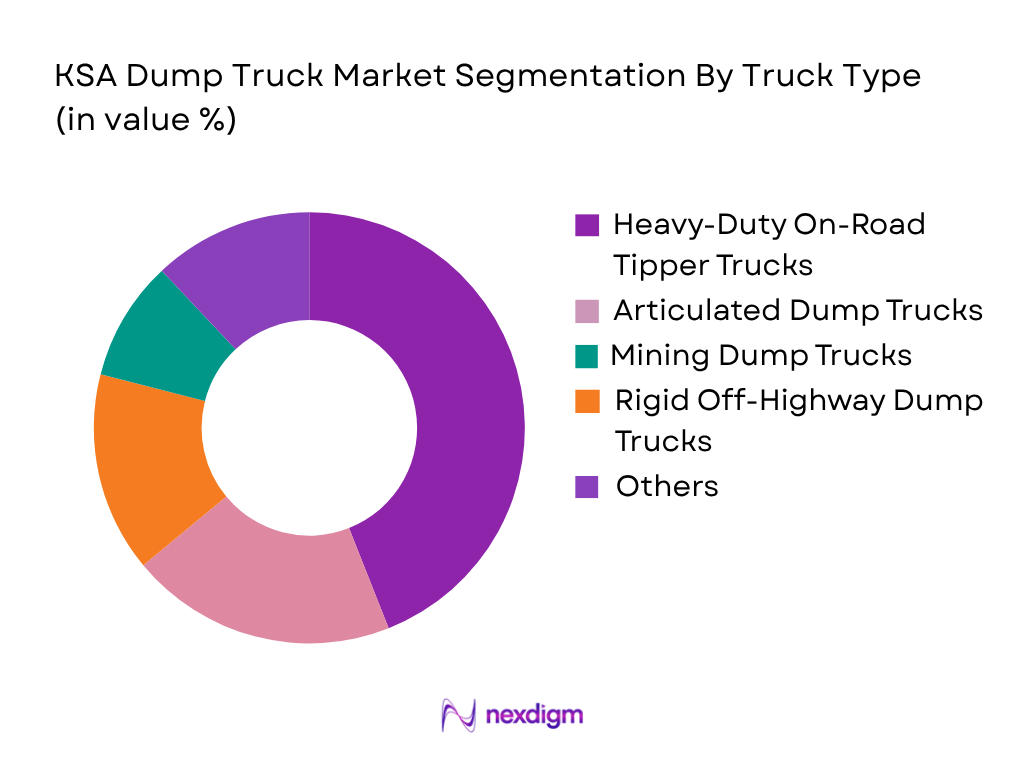
The KSA Dump Truck Market is segmented into heavy-duty on-road tipper trucks, articulated dump trucks, rigid off-highway dump trucks, mining dump trucks, medium-duty tippers and specialist dump trucks. Heavy-duty on-road tipper trucks hold the dominant market position because Saudi construction projects require frequent movement of excavated soil, sand, aggregates, limestone and demolition materials between construction sites, quarries and road networks. Their ability to operate legally on public roads gives 6×4 and 8×4 tippers considerably broader utilisation than dedicated mining haulers. Giga-projects in Riyadh, Tabuk, Makkah and other development corridors also favour high-capacity rigid tippers that can move between suppliers, batching plants and project sites. Articulated and rigid off-highway dump trucks remain strategically important in mines and large quarries, where steep gradients, loose surfaces and repetitive haul cycles favour purpose-built equipment. The segmentation therefore reflects both the scale of infrastructure activity and Saudi Arabia’s substantial mineral and quarry ecosystem.
By Application Type
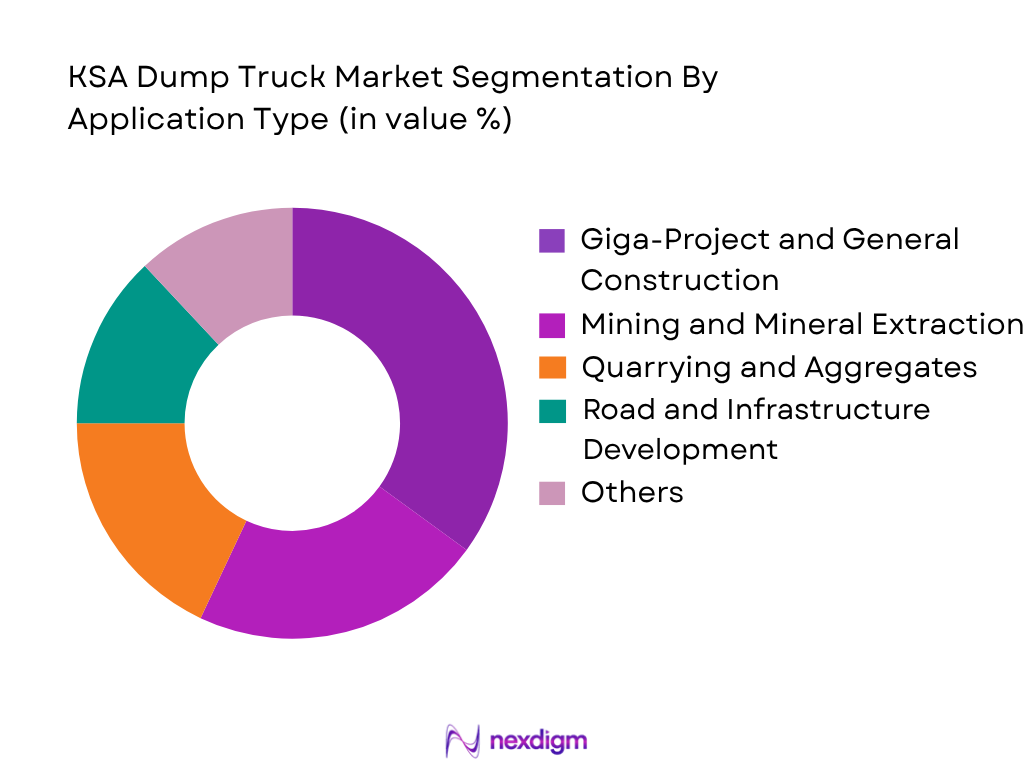
The KSA Dump Truck Market is segmented into giga-project and general construction, mining and mineral extraction, quarrying and aggregates, road and infrastructure development, cement and limestone operations, and other applications. Construction and giga-project activity represents the dominant application segment because Saudi Arabia is simultaneously developing urban districts, tourism destinations, logistics corridors, roads, airports and large mixed-use developments. Dump trucks are required during excavation, bulk earthworks, embankment formation, road-base preparation and aggregate transportation. Mining and quarrying form the second major demand cluster because Saudi Arabia has a substantial mineral-resource base and a large building-material quarry ecosystem. GASTAT recorded 2,401 issued mining licences, including 1,481 building-material quarry licences, demonstrating the operational depth of quarry and extraction activities. This demand structure supports both road-going 8×4 tippers and specialised high-payload mining trucks, with equipment selection determined by road access, haul distance, ground conditions, material density and required tonnes moved per cycle.
Competitive Landscape
The KSA Dump Truck Market is characterised by competition between European heavy-truck manufacturers, Japanese commercial-vehicle suppliers, Chinese high-payload truck producers and global off-highway equipment manufacturers. Mercedes-Benz Trucks, Volvo Trucks, Scania and MAN compete strongly in premium construction fleets, while SINOTRUK and SHACMAN address high-volume heavy-duty applications. Caterpillar, Volvo Construction Equipment, Komatsu, SANY and Liebherr are more prominent in mining, quarrying and off-highway haulage. Competitive advantage depends on payload, severe-duty cooling, drivetrain durability, dealer coverage and remote-site support.
| Major Player | Establishment Year | Headquarters | Core KSA Dump Truck Portfolio | Configuration / Payload Capability | Severe-Duty Desert Capability | Primary Applications | Electrification / Technology Readiness | KSA Aftermarket Support |
| Mercedes-Benz Trucks | 1926 | Stuttgart, Germany | ~ | ~ | ~ | ~ | ~ | ~ |
| Volvo Trucks | 1928 | Gothenburg, Sweden | ~ | ~ | ~ | ~ | ~ | ~ |
| Scania | 1891 | Södertälje, Sweden | ~ | ~ | ~ | ~ | ~ | ~ |
| Caterpillar | 1925 | Irving, USA | ~ | ~ | ~ | ~ | ~ | ~ |
| SINOTRUK | 1956 | Jinan, China | ~ | ~ | ~ | ~ | ~ | ~ |
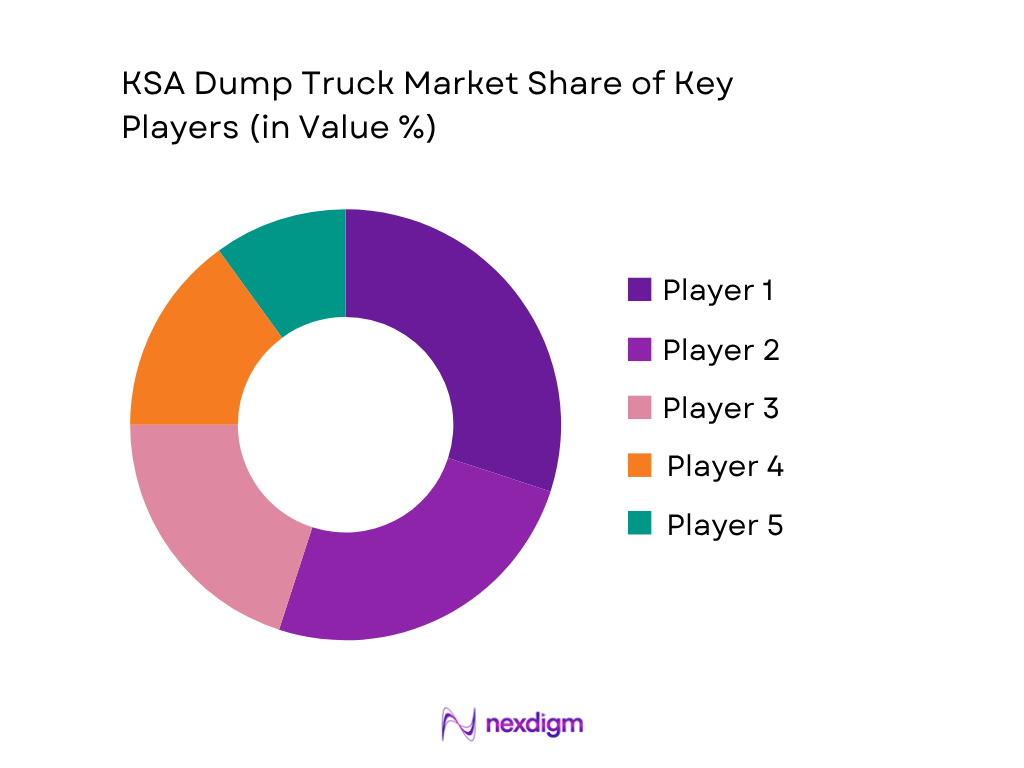
KSA Dump Truck Market Analysis
Growth Drivers
Giga-Project Earthworks and Infrastructure Construction Are Sustaining Heavy Dump Truck Utilisation
Saudi Arabia’s giga-project construction pipeline is a direct growth driver for the KSA Dump Truck Market because large-scale excavation, grading, aggregate movement and site preparation require continuous deployment of 6×4 and 8×4 road tippers alongside articulated off-highway haulers. PIF reported that NEOM covered 26,500 square kilometres and operated more than 100 active development sites in 2024. Construction activities during the year involved excavation of 20 million cubic metres of earth, installation of 200 kilometres of water pipelines, 500 kilometres of fibre infrastructure, and use of 2.4 million cubic metres of concrete. More than 115,000 employees and contractors were working across the NEOM development footprint. These physical construction volumes translate into substantial requirements for moving excavated material, aggregates, fill and construction inputs between work fronts, crushers and disposal locations. The macroeconomic foundation is similarly substantial: World Bank data place Saudi Arabia’s GDP at USD 1,239.8 billion in 2024 and GDP per capita at USD 35,121.7. The combination of major earthworks and large economic capacity supports continued utilisation and replacement of construction-focused dump-truck fleets.
Large Mining and Building-Material Quarry Base Supports Off-Highway Haulage Demand
Saudi Arabia’s expanding mining and quarry ecosystem supports dump-truck demand because extraction sites require repetitive movement of overburden, ore, limestone, aggregates and construction minerals between working faces, crushers and stockpiles. The General Authority for Statistics recorded 5,651 discovered mineralisation sites in 2024, comprising 3,058 non-metallic mineral sites, 2,423 metallic mineral sites and 170 sites containing both categories. The Kingdom also had 2,401 issued mining licences, including 1,481 building-material quarry licences, 642 exploration licences, 215 exploitation licences, 41 reconnaissance licences and 22 surplus mineral-ore licences. This operating footprint creates application-specific demand for articulated dump trucks, rigid mining trucks and high-payload construction tippers capable of operating on unpaved haul roads and under repetitive loading cycles. Mineral logistics are also substantial: Saudi Arabia exported 283,000 tonnes of aluminium and 59,000 tonnes of lead, while phosphate-fertiliser exports reached 5.7 million tonnes in 2024. Supporting this industrial activity, World Bank data record Saudi GDP of USD 1,239.8 billion and GDP per capita of USD 35,121.7 in 2024, providing a sizeable economic base for mining equipment procurement and fleet renewal.
Market Challenges
Severe Construction and Mining Duty Cycles Increase Dump Truck Reliability Requirements
The KSA Dump Truck Market faces demanding utilisation conditions because vehicles supporting construction, quarrying and mining must repeatedly carry high-density material over unfinished roads and remote project sites while maintaining operational availability. The scale of physical activity illustrates the intensity placed on fleets: NEOM alone excavated 20 million cubic metres of earth in 2024 and consumed 2.4 million cubic metres of concrete, while more than 100 development sites were active across its 26,500-square-kilometre footprint. Saudi Arabia simultaneously had 1,481 building-material quarry licences and 215 exploitation licences covering building materials, mining and quarrying, creating numerous locations where dump trucks encounter abrasive rock, repeated tipping cycles and difficult haul-road conditions. Such applications place additional requirements on cooling systems, filtration, hydraulic cylinders, brakes, tyres, suspension, transmissions and drive axles, making uptime and maintenance capability central fleet-selection considerations. Road-safety conditions further reinforce operational pressures: GASTAT recorded 17,231 serious road accidents in 2024, including 4,282 fatalities and 24,077 injuries. These challenges exist within a USD 1,239.8 billion economy, according to the World Bank, increasing the importance of dependable heavy-haul equipment for Saudi infrastructure and industrial activity.
Expanding Heavy-Vehicle Activity Raises Fleet Safety, Compliance and Operational-Control Requirements
Increasing road and construction activity creates a challenge for the KSA Dump Truck Market because road-going tippers must operate within an increasingly dense national vehicle environment while complying with payload, axle-load, roadworthiness and driver-safety requirements. GASTAT reported more than 15.8 million registered and roadworthy vehicles in Saudi Arabia at the end of 2024, compared with 14.8 million vehicles in 2023. New vehicle registrations reached 1,025,700 units in 2024, compared with 878,100 units in the preceding year. Road freight crossing Saudi land ports was also substantial, comprising 13.4 million tonnes of export cargo and 12.2 million tonnes of import cargo. Against this traffic base, the country recorded 17,231 serious traffic accidents, 4,282 fatalities, and 24,077 injuries during 2024. Dump trucks present specific operating challenges because loaded multi-axle vehicles have different braking distances, visibility characteristics and manoeuvring requirements than lighter vehicles, particularly around construction entrances and urban projects. The World Bank’s USD 1,239.8 billion GDP and USD 35,121.7 GDP per capita for 2024 indicate the scale of the economy within which operators must strengthen driver management, telematics, vehicle inspection and preventive maintenance.
Market Opportunities
Expanding Mining Licence Base Creates Future Scope for High-Payload and Technology-Enabled Haulers
Saudi Arabia’s established mineral-resource base creates a strong future opportunity for high-payload dump trucks, articulated haulers and mine-specific fleet technologies. GASTAT recorded 2,401 mining licences in 2024, including 1,481 building-material quarry licences, 642 exploration licences and 215 exploitation licences. The country also contained 5,651 identified mineralisation sites, including 3,058 non-metallic sites and 2,423 metallic sites. These current operating indicators establish a substantial addressable ecosystem in which future mine development can require additional overburden removal, mine-to-crusher transportation and stockpile movement. The opportunity extends beyond vehicle volume toward onboard payload measurement, telematics, automated dispatch, tyre monitoring and semi-autonomous haulage because repetitive mine routes allow fleet productivity to be measured at individual-cycle level. Mineral output and logistics reinforce the opportunity: Saudi Arabia exported 5.7 million tonnes of phosphate fertilisers in 2024, alongside 283,000 tonnes of aluminium and 59,000 tonnes of lead. With World Bank data placing national GDP at USD 1,239.8 billion and GDP per capita at USD 35,121.7 in 2024, equipment suppliers have a sizeable economic and industrial platform for expanding severe-duty mining truck portfolios and supporting technologies.
Large Controlled-Site Construction Activity Creates Future Opportunity for Electrified and Connected Dump Trucks
Saudi Arabia’s concentration of large, controlled construction sites creates future potential for battery-electric, connected and digitally managed dump trucks because fixed haul routes can support centralised charging, dispatch optimisation and predictable operating cycles. NEOM provides a relevant current operating benchmark: more than 100 active development sites were operating in 2024, with 20 million cubic metres of earth excavated, 2.4 million cubic metres of concrete consumed, 200 kilometres of water pipelines laid and 500 kilometres of fibre infrastructure installed. More than 115,000 employees and contractors were active across the project’s 26,500-square-kilometre footprint. Such concentrated construction activity creates conditions in which fleet managers can deploy payload monitoring, geofencing, cycle-time optimisation and eventually electric haulers on repetitive site routes without relying entirely on public charging infrastructure. PIF also reported cumulative investments exceeding USD 171 billion in priority sectors since 2021 in its 2024 reporting, demonstrating the investment platform supporting Saudi economic transformation. At the macroeconomic level, the World Bank records Saudi Arabia’s 2024 GDP at USD 1,239.8 billion and GDP per capita at USD 35,121.7, providing a substantial foundation for future adoption of higher-productivity and lower-emission construction-haulage technologies.
Future Outlook
The KSA Dump Truck Market is forecast to expand at approximately ~X.X% CAGR during 2026–2035, supported by continued construction, mining development, road infrastructure and large-scale earthmoving activity. Demand is expected to shift gradually toward higher-payload 8×4 tippers, advanced articulated haulers, connected fleet-management systems and low-emission mining equipment. Saudi giga-projects will remain a major source of equipment utilisation. PIF reports that NEOM encompasses 26,500 square kilometres, while Qiddiya City covers more than 360 square kilometres. NEOM operated more than 100 active development sites, excavated 20 million cubic metres of earth, installed 200 kilometres of water pipelines, and deployed 500 kilometres of fibre infrastructure during the latest annual reporting period. These figures illustrate the scale of bulk earthmoving and construction-material movement associated with Saudi development programmes.
Mining will create a second structural growth pathway. GASTAT recorded 5,651 discovered mineralisation sites, including 3,058 non-metallic mineral sites, 2,423 metallic mineral sites and 170 mixed mineral sites. Saudi Arabia also had 2,401 mining licences, comprising 1,481 building-material quarry licences, 642 exploration licences, 215 exploitation licences, 41 reconnaissance licences and 22 surplus mineral-ore licences. These operations create future demand for rigid mining trucks, articulated haulers, severe-duty tippers and supporting fleet-maintenance services.
Major Players
- Mercedes-Benz Trucks – Arocs Construction Tippers / 6×4 and 8×4 Heavy-Duty Construction Applications
- Volvo Trucks – FMX Construction Tippers / Heavy Construction / Quarry and Mining Applications
- Scania – P-Series / G-Series / XT Construction Tippers / 6×4 and 8×4 Applications
- MAN Truck & Bus – TGS Construction Tippers / Multi-Axle Heavy-Duty Applications
- IVECO – T-Way / X-Way Tippers / On-Road and Off-Road Construction Applications
- Isuzu Motors – Heavy-Duty Truck Chassis / Tipper and Construction Applications
- SINOTRUK – HOWO Heavy-Duty 6×4 / 8×4 Dump Trucks / Construction and Quarry Applications
- Shaanxi Automobile Group / SHACMAN – X3000 / X5000 / F3000 Dump Trucks / Mining and Heavy Construction Applications
- Volvo Construction Equipment – Articulated Haulers / Rigid Haulers / Quarry / Mining and Earthmoving Applications
- Caterpillar Inc. – Articulated Trucks / Off-Highway Trucks / Mining and Quarry Applications
- Komatsu Ltd. – Rigid Dump Trucks / Mining Trucks / Quarry and Heavy Earthmoving Applications
- SANY Heavy Industry – Wide-Body Mining Dump Trucks / Off-Highway Haulers / Mining and Quarry Applications
- XCMG Group – Mining Dump Trucks / Wide-Body Haulers / Construction and Extraction Applications
- Liebherr Group – Mining Trucks / Heavy-Duty Rigid Haulers / Large Mining Applications
- Bell Equipment – Articulated Dump Trucks / Quarry / Earthmoving / Mining and Heavy Construction Applications
Key Target Audience
- Dump Truck and Heavy Commercial Vehicle Manufacturers
- Construction and Off-Highway Equipment Manufacturers
- Authorized Heavy-Truck and Mining Equipment Distributors
- Giga-Project Infrastructure and EPC Contractors
- Mining Quarry Cement and Aggregate Operators
- Equipment Rental Leasing and Heavy-Fleet Management Companies
- Investments and Venture Capitalist Firms
- Government and Regulatory Bodies (Ministry of Transport and Logistic Services, Transport General Authority, Ministry of Industry and Mineral Resources, Saudi Standards Metrology and Quality Organization, General Authority for Roads)
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves developing an ecosystem map covering the KSA Dump Truck Market across truck manufacturers, equipment OEMs, distributors, contractors, mining companies, quarry operators, bodybuilders and rental fleets. Critical variables include truck architecture, payload, GVW, axle configuration, application, propulsion, regional deployment, severe-duty capability and fleet replacement behaviour. These variables define the structure and boundaries of the addressable market.
Step 2: Market Analysis and Construction
Historical market development is assessed through construction activity, giga-project implementation, mining and quarry licences, heavy-vehicle fleet indicators and equipment procurement patterns. Top-down analysis evaluates macroeconomic, infrastructure and mineral-resource indicators, while bottom-up analysis examines OEM portfolios, distributor activity, fleet composition and specific on-road and off-highway applications. Both approaches are reconciled to construct the market framework.
Step 3: Hypothesis Validation and Expert Consultation
Market hypotheses are validated through computer-assisted telephone interviews with commercial-vehicle dealers, mining-equipment distributors, contractors, quarry operators, fleet managers, bodybuilders and workshop operators. Discussions assess 6×4 versus 8×4 demand, payload preferences, desert-duty performance, parts availability, fleet replacement cycles and electric-hauler readiness. Primary insights are used to refine assumptions developed through secondary research.
Step 4: Research Synthesis and Final Output
The final phase triangulates government statistics, manufacturer data, infrastructure activity, mining indicators, dealer information and expert consultations. Road-going construction tippers and dedicated off-highway dump trucks are analysed separately before consolidation to avoid double counting. This methodology produces a structured assessment of market segmentation, competitive positioning, fleet procurement, regional demand, technology transition and future development of the KSA Dump Truck Market.

- Executive Summary
- Research Methodology (Market Definition and Scope, KSA Dump Truck Taxonomy, On-Road Tipper and Off-Highway Dump Truck Classification, Articulated Dump Truck and Mining Truck Mapping, Heavy Commercial Vehicle Fleet Assessment, Construction Equipment Fleet Mapping, Mining and Quarry Fleet Assessment, Giga-Project and Infrastructure Mapping, Payload and GVW Assessment, Axle Configuration Mapping, Fleet Replacement Assessment, Equipment Rental and Leasing Mapping, Dealer and Workshop Network Assessment, Market Sizing Framework)

- Definition and Scope
- KSA Dump Truck Industry Evolution and Heavy Construction Haulage Development
- Dump Truck Manufacturing, Assembly and Bodybuilding Process
- Dump Truck Value Chain Analysis
- KSA Dump Truck Supply Chain Analysis
- Cab, Chassis, Diesel Engine, Transmission, Drive Axle, Hydraulic Tipping Gear, Tipper Body and Heavy-Duty Tyre Ecosystem Analysis
- KSA Dump Truck Import, Distribution, Bodybuilding and Parts Supply Footprint Assessment
OEM, Authorized Distributor, Construction Contractor, Mining Operator, Rental Fleet and Independent Workshop Framework

- Growth Drivers (Vision 2030 Giga-Project Construction, Road and Urban Infrastructure Development, Mining and Mineral Exploration Expansion, Quarry and Aggregate Haulage Demand, Cement and Limestone Movement, Fleet Replacement, High-Payload 6×4 and 8×4 Adoption, Expansion of Equipment Rental Fleets)
- Market Challenges (Extreme Heat and Dust Operating Conditions, High Tyre and Driveline Wear, Payload and Axle-Load Compliance, Imported Component Dependence, Remote Mining-Site Service Requirements, Diesel Fleet Decarbonisation Pressure, Skilled Heavy-Equipment Technician Availability, Severe-Duty Fleet Downtime)
- Market Opportunities (Battery-Electric Mining Trucks, High-Payload 8×4 Construction Tippers, Autonomous and Semi-Autonomous Mine Haulage, Local Tipper Body Manufacturing, Heavy-Duty Component Localization, Payload Monitoring and Fleet Telematics, Mining Equipment Rental Expansion, Remanufacturing and Rebuild Services)
- Market Trends (High-Horsepower Powertrains, 8×4 Construction Tipper Adoption, Wide-Body Mining Trucks, Automated Manual Transmissions, Reinforced Abrasion-Resistant Bodies, On-Board Payload Weighing, Connected Fleet Management, Operator-Assistance Systems)
- Regulatory and Standards Landscape (Transport General Authority Heavy Truck Requirements, Saudi Standards Metrology and Quality Organization Vehicle Technical Regulations, Gross Vehicle Weight and Axle-Load Requirements, Vehicle Dimensions Requirements, Heavy Vehicle Operating Requirements, Mining Safety Requirements, Municipal Construction Vehicle Requirements, Vehicle Conformity and Inspection Requirements, Environmental and Emission Compliance Requirements)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Competition Ecosystem

- By Market Value (2020-2025)
- By New Dump Truck Sales Volume (2020-2025)
- By Replacement Dump Truck Volume (2020-2025)
- By On-Road Rigid Tipper Volume (2020-2025)
- By Articulated Dump Truck Volume (2020-2025)
- By Mining and Quarry Dump Truck Volume (2020-2025)

- By Truck Type (In Value %)
Heavy-Duty On-Road Tipper Trucks
Medium-Duty Tipper Trucks
Construction-Specification Rigid Tippers
Mining Dump Trucks
Articulated Dump Trucks
Rigid Off-Highway Dump Trucks
Quarry-Specification Dump Trucks
Wide-Body Mining Dump Trucks
Battery-Electric Dump Trucks
Other Special-Purpose Dump Trucks - By Payload and GVW Class (In Value %)
Below 15-Tonne Payload
15-Tonne to 25-Tonne Payload
Above 25-Tonne to 35-Tonne Payload
Above 35-Tonne to 45-Tonne Payload
Above 45-Tonne to 60-Tonne Payload
Above 60-Tonne to 100-Tonne Payload
Above 100-Tonne Payload
26-Tonne GVW Road Tippers
32-Tonne GVW Road Tippers
Heavy Off-Highway Payload Classes - By Axle and Drive Configuration (In Value %)
4×2 Tippers
4×4 Tippers
6×4 Tippers
6×6 Tippers
8×4 Tippers
8×6 Heavy-Duty Tippers
8×8 Severe-Duty Tippers
Three-Axle Articulated Dump Trucks
Multi-Axle Mining Dump Trucks
Other Heavy-Duty Configurations - By Application Type (In Value %)
Giga-Project Construction
Road and Highway Construction
Urban Infrastructure Development
Residential and Commercial Construction
Mining and Mineral Extraction
Quarrying and Aggregates
Cement and Limestone Operations
Earthmoving and Site Preparation
Oil and Gas Infrastructure
Industrial and Logistics Zone Development
Demolition and Muckaway
Waste and Landfill Operations - By Propulsion Type (In Value %)
Heavy-Duty Diesel Dump Trucks
Severe-Duty Mining Diesel Dump Trucks
Low-Emission Diesel Dump Trucks
Battery-Electric Dump Trucks
Battery-Electric Mining Trucks
Hybrid Dump Trucks
Hydrogen-Ready Heavy Trucks
Other Alternative-Fuel Dump Trucks - By Procurement and Ownership Model (In Value %)
Construction Contractor Direct Ownership
Mining Company Fleet Ownership
Quarry and Aggregate Operator Ownership
Giga-Project Contractor Procurement
Equipment Rental and Plant Hire
Long-Term Equipment Leasing
Fleet Management Company Procurement
Government and Municipal Procurement
Used Dump Truck Procurement
Project-Specific Short-Term Rental - By Region (In Value %)
Riyadh Region
Makkah Region
Eastern Province
Madinah Region
Tabuk Region
Asir Region
Al-Qassim Region
Jazan Region
Northern Borders Region
Al-Jouf Region
Other KSA Regions

- Market Share of Major Players (By Revenue, Truck Type, Payload Class, Axle Configuration, Application, End-User Type, Region, Dealer and Rental Network Presence)
- Cross Comparison Parameters (KSA Road Tipper and Off-Highway Dump Truck Portfolio Breadth, Payload GVW and 6×4 8×4 Articulated Configuration Coverage, Giga-Project Construction Quarry Mining and Infrastructure Application Coverage, High-Temperature Desert Severe-Duty Powertrain Capability, Battery-Electric and Low-Emission Dump Truck Readiness, KSA Dealer Rental Parts Uptime and Remote-Site Technical Support Network, Tipper Bodybuilder Integration Payload Optimisation and Hydraulic System Capability, Payload Monitoring Telematics Operator-Assistance and Autonomous-Haulage Capability)
- SWOT Analysis of Major Players
- Competitive Positioning Matrix
- Pricing and Distribution Network Benchmarking
- Detailed Profiles of Major Companies
Mercedes-Benz Trucks – Arocs Construction Tippers / 6×4 and 8×4 Heavy-Duty Construction Applications
Volvo Trucks – FMX Construction Tippers / Heavy Construction / Quarry and Mining Applications
Scania – P-Series / G-Series / XT Construction Tippers / 6×4 and 8×4 Applications
MAN Truck & Bus – TGS Construction Tippers / Multi-Axle Heavy-Duty Applications
IVECO – T-Way / X-Way Tippers / On-Road and Off-Road Construction Applications
Isuzu Motors – Heavy-Duty Truck Chassis / Tipper and Construction Applications
SINOTRUK – HOWO Heavy-Duty 6×4 / 8×4 Dump Trucks / Construction and Quarry Applications
Shaanxi Automobile Group / SHACMAN – X3000 / X5000 / F3000 Dump Trucks / Mining and Heavy Construction Applications
Volvo Construction Equipment – Articulated Haulers / Rigid Haulers / Quarry / Mining and Earthmoving Applications
Caterpillar Inc. – Articulated Trucks / Off-Highway Trucks / Mining and Quarry Applications
Komatsu Ltd. – Rigid Dump Trucks / Mining Trucks / Quarry and Heavy Earthmoving Applications
SANY Heavy Industry – Wide-Body Mining Dump Trucks / Off-Highway Haulers / Mining and Quarry Applications
XCMG Group – Mining Dump Trucks / Wide-Body Haulers / Construction and Extraction Applications
Liebherr Group – Mining Trucks / Heavy-Duty Rigid Haulers / Large Mining Applications
Bell Equipment – Articulated Dump Trucks / Quarry / Earthmoving / Mining and Heavy Construction Applications

- Dump Truck Buyer Segmentation
- Construction Contractor and Mining Operator Procurement Behaviour
- Dump Truck Supplier and Dealer Selection Criteria
- Fleet Operator, Quarry and Mining Contractor Pain Points
- Payload, Severe-Duty and Electrification Adoption Assessment
- Replacement and Repurchase Behaviour

- By Market Value (2026-2035)
- By New Dump Truck Sales Volume (2026-2035)
- By Replacement Dump Truck Volume (2026-2035)
- By On-Road Rigid Tipper Volume (2026-2035)
- By Articulated Dump Truck Volume (2026-2035)
- By Mining and Quarry Dump Truck Volume (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
