
 Download PDF
Market Overview
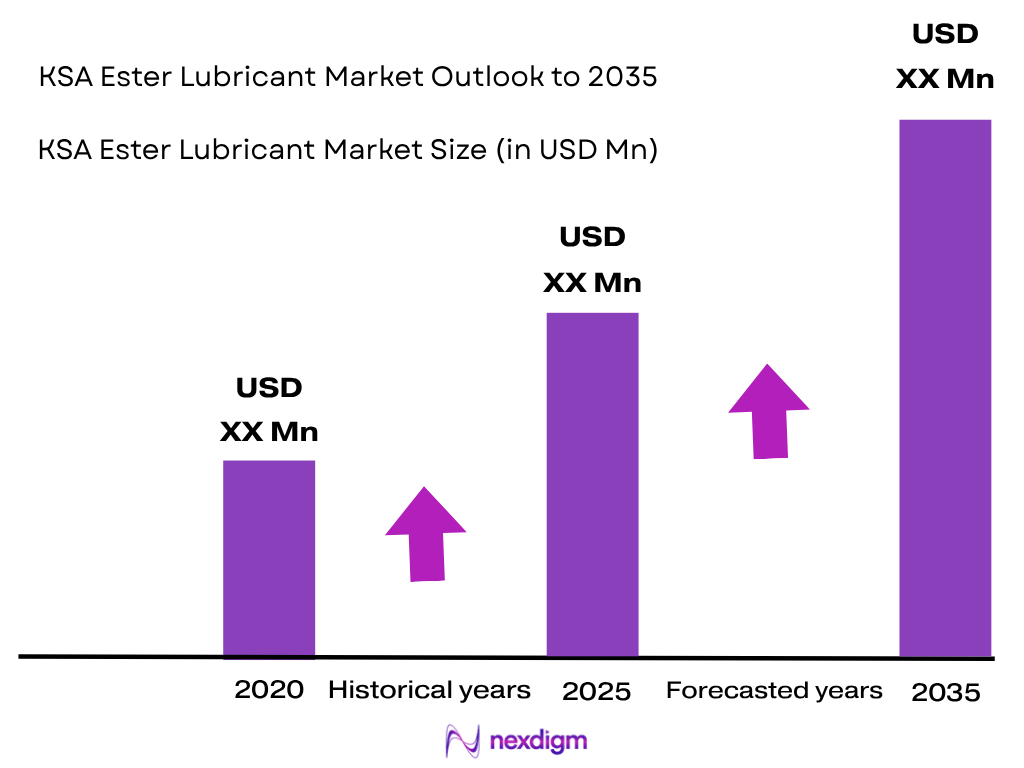
The KSA Ester Lubricant Market is valued at USD ~XX billion in 2024 and is driven by increasing demand for high-performance lubrication solutions across oil and gas, petrochemical, automotive, and industrial applications. Saudi Arabia’s industrial ecosystem supports ester lubricant consumption due to its extensive energy sector, which produced approximately 9 million barrels per day of crude oil in 2024. The country’s GDP reached around USD 1.1 trillion, reflecting continued industrial activity and investment in advanced machinery requiring efficient lubrication systems. The market growth is supported by rising adoption of synthetic lubricants offering thermal stability, oxidation resistance, and improved equipment protection.
The KSA Ester Lubricant Market is concentrated around industrial hubs including Riyadh, Jeddah, Dammam, Jubail, and Yanbu due to their strong presence of manufacturing facilities, petrochemical complexes, refineries, and heavy industrial operations. The Eastern Province dominates demand because it contains major oil and gas production assets and industrial cities such as Jubail Industrial City, which hosts large-scale petrochemical and chemical manufacturing activities. Riyadh contributes through automotive, construction, and industrial equipment demand, while Jeddah supports marine, logistics, and commercial transportation applications. Saudi Arabia’s industrial diversification initiatives continue supporting demand for specialty lubrication technologies.
Market Segmentation
By Ester Type
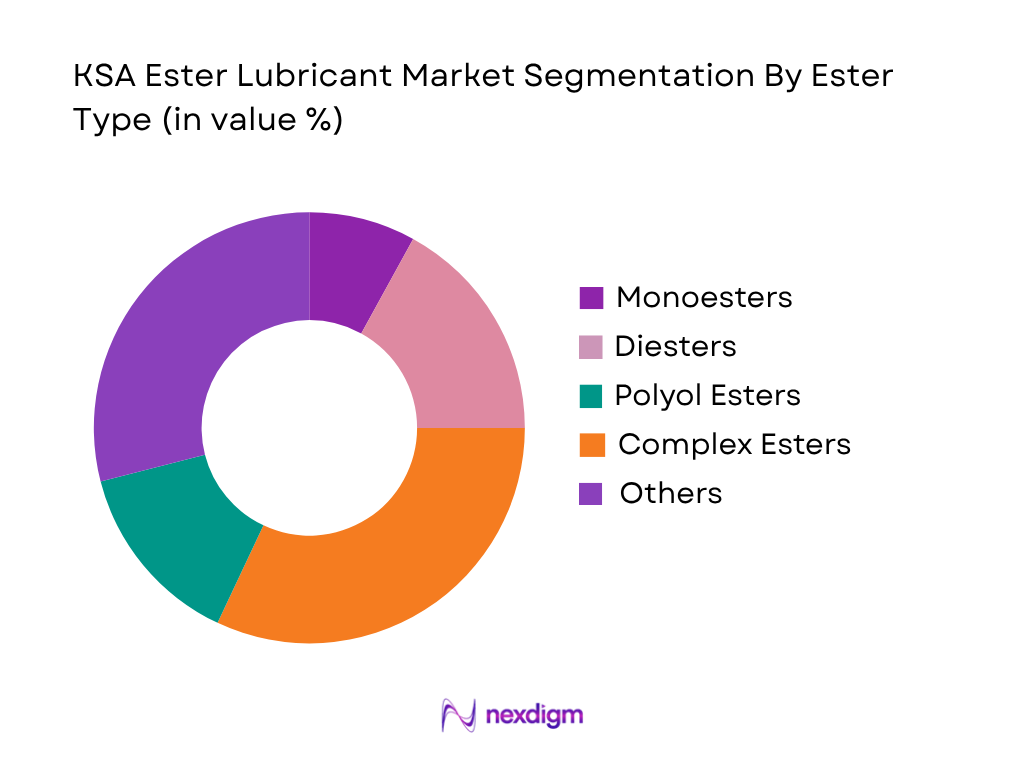
The KSA Ester Lubricant Market is segmented by ester type into monoesters, diesters, polyol esters, complex esters, trimellitate esters, phosphate esters, neopolyol esters, and other specialty esters. Polyol esters represent the dominant sub-segment due to their superior thermal stability, oxidation resistance, and performance under extreme operating conditions. These properties make polyol esters suitable for aerospace systems, turbines, compressors, and industrial machinery operating under high temperatures. Oil and gas operations in Saudi Arabia require lubricants capable of maintaining performance in harsh environments, increasing demand for advanced ester formulations. Diesters remain important due to their excellent low-temperature properties and solvency characteristics, while complex esters are increasingly used where customized performance requirements are necessary. The growing requirement for extended equipment life and reduced maintenance frequency supports adoption of high-performance ester chemistries.
By End-Use Industry
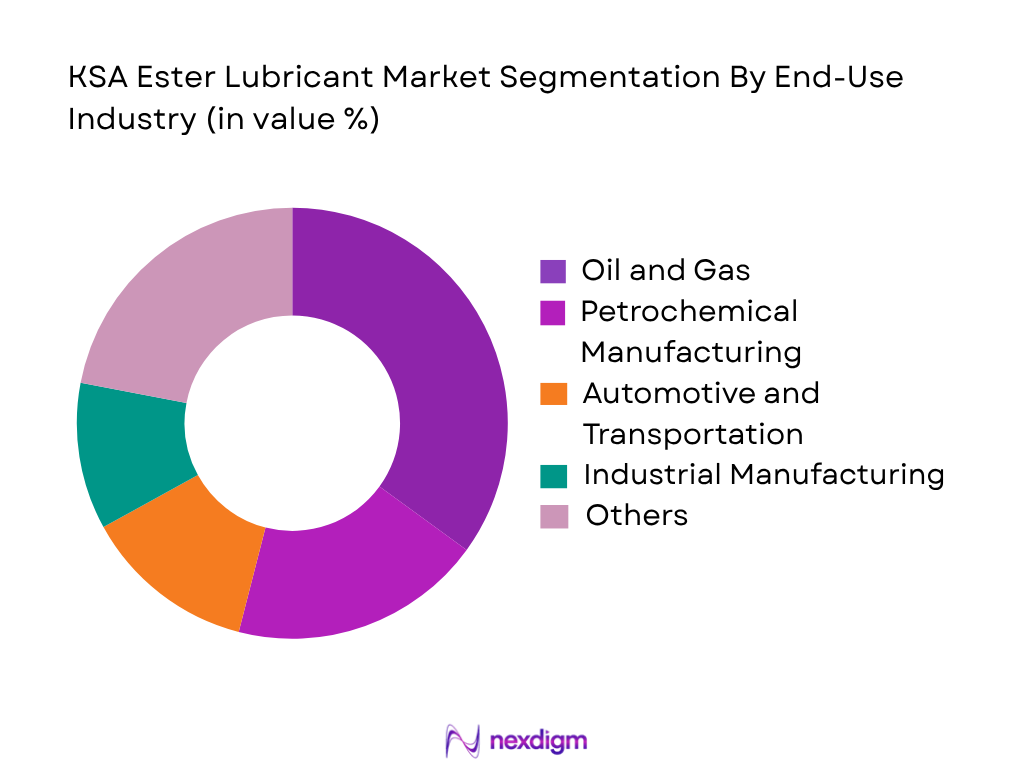
The KSA Ester Lubricant Market is segmented by end-use industry into oil and gas, petrochemical manufacturing, automotive and transportation, industrial manufacturing, aerospace and defense, power generation, marine and shipping, mining and mineral processing, food and beverage processing, and chemical manufacturing. Oil and gas represents the dominant sub-segment due to Saudi Arabia’s globally significant petroleum industry and extensive requirement for advanced lubrication systems in drilling equipment, compressors, turbines, pumps, and processing machinery. The country’s crude oil production capacity and large-scale refining infrastructure create consistent demand for specialty lubricants capable of operating under high pressure and temperature conditions. Petrochemical facilities in Jubail and Yanbu also contribute significantly through requirements for process equipment lubrication. Industrial manufacturing and power generation sectors further support market expansion as companies increasingly adopt synthetic lubricants to improve operational efficiency and reduce equipment downtime.
Competitive Landscape
The KSA Ester Lubricant Market includes global lubricant manufacturers, specialty chemical producers, and regional lubricant suppliers competing through advanced ester formulations, technical services, and industrial customer relationships. The competitive environment is influenced by companies supplying synthetic base stocks, specialty lubricants, and application-specific solutions for oil and gas, automotive, aerospace, and industrial sectors. Major players focus on expanding product portfolios, improving lubricant performance, and developing sustainable ester-based formulations.
| Company | Establishment Year | Headquarters | Ester Portfolio | Key Applications | Industry Focus | Distribution Network | Technology Capability | Regional Presence |
| Saudi Aramco Base Oils | 2017 | Saudi Arabia | ~ | ~ | ~ | ~ | ~ | ~ |
| ExxonMobil Corporation | 1999 | USA | ~ | ~ | ~ | ~ | ~ | ~ |
| BASF Corporation | 1865 | Germany | ~ | ~ | ~ | ~ | ~ | ~ |
| Croda International Plc | 1925 | UK | ~ | ~ | ~ | ~ | ~ | ~ |
| Fuchs SE | 1931 | Germany | ~ | ~ | ~ | ~ | ~ | ~ |
KSA Ester Lubricant Market Analysis
Growth Drivers
Expansion of Oil and Gas and Petrochemical Operations Supporting Ester Lubricant Consumption
The KSA Ester Lubricant Market is strongly supported by the country’s large-scale oil and gas ecosystem, where high-performance lubrication solutions are required for compressors, turbines, hydraulic systems, drilling equipment, and processing machinery. Saudi Arabia remained one of the largest global oil producers, with crude oil production reaching approximately 9 million barrels per day in 2024, creating sustained demand for advanced industrial lubrication systems across upstream and downstream operations. The country’s economy recorded a GDP of around USD 1.1 trillion in 2024, supported significantly by energy and industrial activities. The Eastern Province, including industrial centers such as Dammam, Jubail, and Ras Tanura, continues to generate demand for specialty lubricants due to the concentration of refineries, petrochemical plants, and heavy equipment operations. Ester lubricants provide advantages such as high thermal stability, reduced volatility, and improved oxidation resistance, making them suitable for continuous-duty industrial machinery. The expansion of petrochemical production capacity and industrial processing activities under Saudi Arabia’s economic diversification programs is increasing the requirement for efficient lubrication technologies that enhance equipment reliability and operational performance.
Growth of Industrial Manufacturing and Infrastructure Development Increasing Demand for High-Performance Lubricants
The KSA Ester Lubricant Market benefits from increasing industrial development, infrastructure expansion, and modernization of machinery across manufacturing sectors. Saudi Arabia’s non-oil economic activities continue to expand, supported by investments in manufacturing, transportation, construction, and industrial projects. The country’s industrial sector includes more than 10,000 registered factories, creating a broad requirement base for machinery lubricants, hydraulic fluids, compressor oils, and specialty industrial lubrication solutions. Manufacturing activities require lubricants capable of operating under high temperature, heavy load, and extended service conditions, supporting demand for ester-based formulations. The construction and infrastructure sectors also contribute to lubricant demand through extensive usage of heavy equipment such as excavators, cranes, and hydraulic machinery. Saudi Arabia’s population exceeded 35 million in 2024, supporting infrastructure development, logistics expansion, and transportation growth, which indirectly increases demand for advanced lubricant solutions. Ester lubricants are increasingly considered for applications where improved equipment efficiency, reduced maintenance frequency, and enhanced operating reliability are required, creating opportunities across industrial machinery, power generation, and transportation applications.
Market Challenges
Dependence on Imported Specialty Ester Raw Materials and Advanced Formulations
The KSA Ester Lubricant Market faces challenges due to dependence on imported specialty ester base stocks, additives, and advanced formulation technologies. Although Saudi Arabia has a strong petrochemical industry, domestic production of specialized ester lubricant components remains limited compared with conventional petroleum-based lubricant materials. The country imported approximately USD 23 billion worth of chemical products in 2023, highlighting the importance of international supply chains for specialty chemical requirements. Ester lubricant production requires specific alcohols, fatty acids, and chemical processing capabilities, which can create supply risks when global logistics conditions fluctuate. International transportation disruptions, raw material availability constraints, and currency movements can influence procurement timelines for lubricant manufacturers and distributors. Additionally, ester formulations require technical expertise to ensure compatibility with seals, additives, and equipment systems, increasing the complexity of adoption among industrial users. Companies operating in Saudi Arabia must manage supply chain reliability while maintaining product performance standards for critical applications such as oil and gas machinery, aerospace systems, and industrial equipment.
Competition from Conventional Lubricants and Technology Adoption Barriers
The KSA Ester Lubricant Market experiences competition from conventional mineral-based lubricants and other synthetic lubricant technologies due to differences in availability, familiarity, and application requirements. Mineral oils continue to be widely used across industrial and automotive sectors because of established supply networks and existing equipment compatibility. Ester lubricants generally provide superior performance characteristics, including higher thermal stability and improved biodegradability, but their adoption can be limited by higher formulation complexity and the need for technical validation. Saudi Arabia operates more than 70 million vehicles according to regional transportation estimates, creating a large lubricant consumption base where conventional products remain dominant. Industrial users may also require extensive testing before transitioning critical machinery from traditional lubricants to ester-based alternatives. The requirement for equipment-specific approvals, operator awareness, and maintenance procedure adjustments can slow adoption. Furthermore, some ester chemistries have limitations related to hydrolytic stability when exposed to moisture, requiring careful formulation selection for specific operating environments.
Market Opportunities
Increasing Adoption of Sustainable and Bio-Based Lubricant Technologies
The KSA Ester Lubricant Market has opportunities through rising demand for environmentally acceptable lubricant solutions across industrial applications. Ester-based lubricants offer advantages such as biodegradability, lower volatility, and improved environmental performance compared with conventional mineral oils, making them suitable for applications where sustainability requirements are increasing. Saudi Arabia’s environmental initiatives are encouraging industries to improve resource efficiency and adopt cleaner technologies. The country generated approximately 600 million tons of carbon dioxide emissions in 2023, increasing attention toward industrial efficiency and emissions reduction measures. Bio-based ester lubricants derived from renewable feedstocks can support industries seeking improved environmental performance while maintaining operational reliability. Applications including hydraulic fluids, marine lubricants, forestry equipment, and industrial machinery present opportunities for environmentally acceptable ester formulations. The development of sustainable industrial practices, combined with increasing awareness among manufacturers and operators, is creating demand for advanced lubricant technologies that balance performance requirements with environmental considerations.
Expansion of Advanced Industrial Applications and Equipment Modernization
The KSA Ester Lubricant Market presents opportunities through modernization of industrial equipment and increasing demand for specialized lubrication solutions in high-performance applications. Saudi Arabia continues to invest in industrial diversification, manufacturing development, and advanced infrastructure projects, increasing the requirement for reliable machinery operation. The country’s electricity generation capacity exceeded 80 GW in recent years, supporting demand for turbine, compressor, and power-generation lubrication systems. Ester lubricants are suitable for demanding applications requiring high-temperature stability, low evaporation rates, and extended operating life, including turbines, compressors, aerospace systems, and precision machinery. Growth in sectors such as petrochemicals, aviation, renewable energy, and advanced manufacturing creates opportunities for customized ester formulations. The expansion of industrial cities such as Jubail and Yanbu provides additional demand potential because these locations contain large concentrations of chemical processing and manufacturing facilities. As industries focus on reducing downtime and improving asset efficiency, the adoption of specialty ester lubricants is expected to increase across critical equipment applications.
Future Outlook
Over the next decade, the KSA Ester Lubricant Market is expected to witness continued development driven by industrial diversification, oil and gas equipment modernization, and increasing demand for high-performance lubricant technologies. The expansion of petrochemical facilities, manufacturing industries, and advanced mobility solutions will support adoption of synthetic ester formulations. Sustainability initiatives and demand for environmentally acceptable lubricants will further encourage development of bio-based ester technologies. Companies investing in customized lubricant solutions, technical support capabilities, and specialty ester formulations are expected to address evolving industrial requirements.
Major Players
- Saudi Aramco Base Oils
- ExxonMobil Corporation
- BASF Corporation
- Croda International Plc
- Emery Oleochemicals
- LANXESS Corporation
- The Lubrizol Corporation
- Shell Saudi Arabia
- Fuchs SE
- TotalEnergies Marketing Saudi Arabia
- Castrol Saudi Arabia
- Chevron Lubricants
- Afton Chemical Corporation
- Valvoline Inc.
- NYCO
Key Target Audience
- Oil and Gas Companies
- Petrochemical Manufacturers
- Automotive Manufacturers and Service Providers
- Industrial Machinery Manufacturers
- Aerospace and Defense Organizations
- Power Generation Companies
- Investments and Venture Capitalist Firms
- Government and Regulatory Bodies (Saudi Standards, Metrology and Quality Organization, Ministry of Environment, Water and Agriculture)
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves developing an ecosystem map covering major stakeholders within the KSA Ester Lubricant Market. This includes assessment of ester manufacturers, lubricant formulators, industrial users, raw material suppliers, and distribution networks. The research focuses on identifying critical market variables influencing demand, supply dynamics, application adoption, and technology development.
Step 2: Market Analysis and Construction
This phase involves compiling historical market information related to ester lubricant consumption, application demand, industrial usage patterns, and supply chain structure. Analysis includes evaluation of oil and gas demand, industrial equipment requirements, lubricant formulation trends, and regional consumption patterns to establish market understanding.
Step 3: Hypothesis Validation and Expert Consultation
Market assumptions are validated through discussions with industry participants including lubricant manufacturers, distributors, industrial operators, and technical specialists. These consultations provide insights into product performance requirements, customer preferences, application challenges, and future technology adoption.
Step 4: Research Synthesis and Final Output
The final phase combines primary and secondary research findings to develop a comprehensive assessment of the KSA Ester Lubricant Market. Data validation is performed through cross-verification of industry information, supply-side analysis, demand assessment, and competitive benchmarking.

- Executive Summary
- Research Methodology (Market Definition and Scope, KSA Ester Lubricant Market Classification, Ester Base Stock Mapping, Ester Chemistry Assessment, Ester Molecular Structure Assessment, Monoester and Diester Evaluation, Polyol Ester Assessment, Complex Ester Assessment, Trimellitate Ester Assessment, Synthetic and Bio-Based Ester Assessment, Viscosity Grade Mapping, Performance Property Assessment, Application-Level Demand Analysis, End-Use Industry Assessment, Lubricant Formulation Mapping, Base Oil Supply Assessment, Domestic Blending Assessment, Import and Export Trade Analysis, Raw Material Supply Assessment, Demand-Side Assessment, Supply-Side Assessment, Top-Down Market Sizing, Bottom-Up Market Sizing, Primary Industry Interviews, Data Triangulation, Forecasting Framework, Market Share Validation, Limitations and Future Conclusions)

- Definition and Scope
- KSA Ester Lubricant Industry Evolution and Development of Synthetic Base Oil Technology, High-Performance Lubricant Formulation, Oil and Gas Lubrication, Petrochemical Industry Lubricants, Automotive Lubricants, Industrial Fluid Applications and Bio-Based Lubricant Technologies
- Ester Lubricant Value Chain Analysis
- Ester Lubricant Supply Chain Analysis
- Fatty Acid and Alcohol Feedstock Suppliers, Petrochemical Feedstock Suppliers, Ester Base Stock Manufacturers, Specialty Ester Producers, Lubricant Additive Manufacturers, Lubricant Blenders, Industrial Lubricant Manufacturers, Automotive Lubricant Suppliers, Oilfield Lubricant Suppliers, Aerospace Lubricant Suppliers, Distributors, Industrial OEMs and End-Use Industries
- Ester Lubricant Integration Across Automotive Engine Oils, Transmission Fluids, Gear Lubricants, Hydraulic Fluids, Compressor Oils, Turbine Lubricants, Metalworking Fluids, Greases, Aerospace Lubricants, Marine Lubricants, Oil and Gas Equipment Lubricants and Environmentally Acceptable Lubricants

- Growth Drivers (Expansion of Oil and Gas Operations, Growth of Petrochemical Manufacturing, Demand for High-Performance Synthetic Lubricants, Increasing Industrial Equipment Deployment, High-Temperature Lubrication Requirements, Aerospace Maintenance Activities, Automotive Fleet Expansion, Demand for Equipment Reliability Improvement, Adoption of Environmentally Acceptable Lubricants)
- Market Challenges (Dependence on Imported Specialty Ester Feedstocks, High Manufacturing and Formulation Complexity, Competition from Mineral and Synthetic Hydrocarbon Lubricants, Harsh Desert Operating Conditions, Limited Domestic Ester Production Capability, Technical Qualification Requirements, Lubricant Compatibility Issues, Raw Material Supply Volatility, Limited Awareness Among Small Industrial Users)
- Market Opportunities (Oil and Gas Specialty Ester Lubricants, Bio-Based Ester Expansion, Renewable Lubricant Adoption, Aerospace and Aviation Lubricants, High-Temperature Industrial Lubricants, Environmentally Acceptable Hydraulic Fluids, Advanced Automotive Lubricant Solutions, Sustainable Industrial Lubrication, Specialty Ester Formulation Development)
- Market Trends (Shift Toward Synthetic Base Stocks, Sustainable Lubricant Development, Advanced Ester Formulations, High-Temperature Performance Enhancement, Low-Volatility Lubricant Technologies, Oilfield Specialty Lubricants, Longer Drain Interval Lubricants, High-Efficiency Industrial Lubrication, Ester-PAO Blended Lubricants)
- Government Regulations and Standards (Saudi Standards Metrology and Quality Organization Requirements, Saudi Aramco Lubricant Specifications, Ministry of Environment Water and Agriculture Requirements, Industrial Chemical Safety Regulations, Environmental Protection Standards, ISO Lubricant Standards, ASTM Lubricant Testing Standards, API Lubricant Standards, OEM Lubricant Qualification Standards)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Competition Ecosystem

- By Market Value (2020-2025)
- By Market Volume (2020-2025)
- By Ester Base Stock Consumption Volume (2020-2025)
- By Synthetic Ester Consumption Volume (2020-2025)
- By Bio-Based Ester Consumption Volume (2020-2025)
- By Monoester Consumption Volume (2020-2025)
- By Diester Consumption Volume (2020-2025)
- By Polyol Ester Consumption Volume (2020-2025)
- By Domestic Lubricant Blending Volume (2020-2025)
- By Import Volume of Ester Lubricant Raw Materials (2020-2025)
- By Average Selling Price (2020-2025)

- By Ester Type (In Value %)
Monoesters
Diesters
Polyol Esters
Complex Esters
Trimellitate Esters
Phosphate Esters
Neopolyol Esters
Other Specialty Esters - By Base Stock Origin (In Value %)
Petrochemical-Based Esters
Oleochemical-Based Esters
Bio-Based Esters
Renewable Feedstock-Based Esters
Blended Ester Base Stocks - By Lubricant Application (In Value %)
Engine Oils
Transmission and Gear Lubricants
Hydraulic Fluids
Compressor Lubricants
Turbine Lubricants
Metalworking Fluids
Greases
Aerospace Lubricants
Marine Lubricants
Refrigeration Lubricants - By End-Use Industry (In Value %)
Oil and Gas
Petrochemical Manufacturing
Automotive and Transportation
Industrial Manufacturing
Aerospace and Defense
Power Generation
Marine and Shipping
Mining and Mineral Processing
Food and Beverage Processing
Chemical and Pharmaceutical Manufacturing - By Equipment Type (In Value %)
Heavy-Duty Equipment
Rotating Equipment
Gas Turbines
Compressors
Hydraulic Systems
Industrial Gear Systems
Automotive Engines
Marine Engines
Oilfield Equipment
Processing Machinery - By Region (In Value %)
Central Region
Eastern Province
Western Region
Northern Region
Southern Region

- Market Share of Major Players (By KSA Revenue, Ester Base Stock Sales Volume, Ester Chemistry Portfolio, Production Capacity, Synthetic Ester Portfolio, Bio-Based Ester Portfolio, Oil and Gas Application Exposure, Industrial Application Coverage, Automotive Application Coverage, Distribution Network Coverage, Regional Presence, OEM Customer Coverage, Technical Service Capability)
- Cross Comparison Parameters (Ester Lubricant Revenue, Ester Chemistry Portfolio Breadth, Polyol Ester Technology Coverage, Oil and Gas Lubricant Capability, Industrial Application Coverage, Synthetic Ester Production Capability, Bio-Based Ester Portfolio Breadth, KSA Distribution Network Reach)
- SWOT Analysis of Major Players
- Competitive Positioning Matrix
- Ester Base Stock Product Portfolio and Application Benchmarking
- Synthetic Ester Formulation and Performance Assessment
- Oil and Gas Ester Lubricant Technology Assessment
- Automotive and Transportation Ester Lubricant Technology Assessment
- Industrial Ester Lubricant and Metalworking Fluid Assessment
- Bio-Based and Environmentally Acceptable Ester Technology Assessment
- Major Companies
Saudi Aramco Base Oils
ExxonMobil Corporation
BASF Corporation
Croda International Plc
Emery Oleochemicals
LANXESS Corporation
The Lubrizol Corporation
Shell Saudi Arabia
Fuchs Lubricants Saudi Arabia
TotalEnergies Marketing Saudi Arabia
Castrol Saudi Arabia
Chevron Lubricants
Afton Chemical Corporation
Valvoline Inc.
NYCO

- Oil and Gas Operator Ester Lubricant Requirement Assessment
- Petrochemical Plant Lubrication Requirement Analysis
- Automotive OEM Ester Lubricant Requirement Assessment
- Industrial Machinery Lubricant Procurement Analysis
- Power Generation Equipment Lubrication Assessment
- Aerospace Maintenance Lubricant Requirement Analysis
- Marine Equipment Lubricant Procurement Assessment
- Mining Equipment Lubrication Requirement Analysis
- Food Processing Lubricant Procurement Assessment
- Construction Equipment Lubrication Analysis
- Compressor and Turbine Lubricant Requirement Assessment
- Lubricant Blender Ester Base Stock Procurement Analysis
- Industrial OEM Ester Lubricant Qualification Assessment

- By Market Value (2026-2035)
- By Market Volume (2026-2035)
- By Ester Base Stock Consumption Volume (2026-2035)
- By Synthetic Ester Consumption Volume (2026-2035)
- By Bio-Based Ester Consumption Volume (2026-2035)
- By Monoester Consumption Volume (2026-2035)
- By Diester Consumption Volume (2026-2035)
- By Polyol Ester Consumption Volume (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
