
 Download PDF
Market Overview
The KSA Mining Drill Bits Market is supported by the Kingdom’s accelerating mineral exploration and mine-development activity. Saudi Arabia recorded SAR 770 million in exploration expenditure and SAR 230 million in drilling expenditure, compared with SAR 152 million in drilling expenditure previously reported for the preceding period. The Kingdom also has 933 exploration locations, comprising 691 gold-related locations and 242 base-metal locations. Gold production reached 16,293 kg, while copper concentrate production reached 74,000 tonnes, creating recurring requirements for exploration, production and replacement drilling tools.
Mining-drill-bit demand is concentrated around Saudi Arabia’s major mineralized belts and mining regions, particularly areas associated with the Arabian Shield and established gold, copper and zinc operations. The Ministry announced exploration opportunities covering more than 940 square kilometers across sites containing gold, copper, zinc, lead and silver, while another exploration opportunity round covered 1,000 square kilometers. The Jabal Sayid and Al-Hajjar mineralized belts alone cover 4,788 square kilometers and contain gold, copper and zinc, supporting sustained requirements for hard-rock drilling, exploration tooling and production bits.
Market Segmentation
By Drill Bit Type
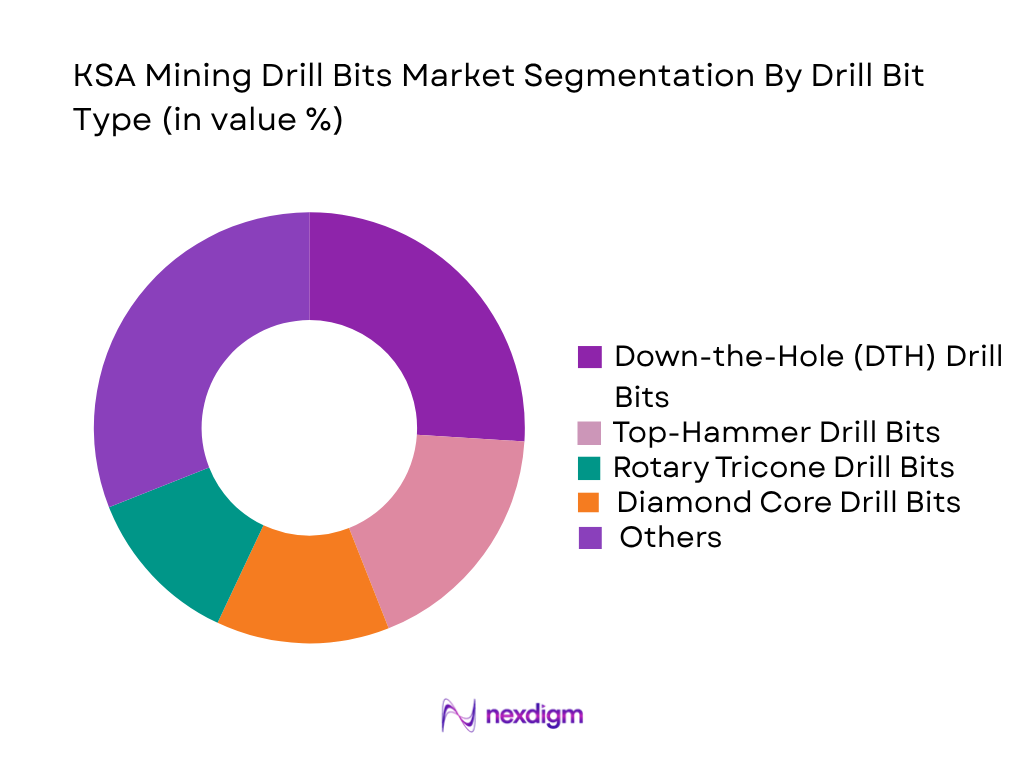
The KSA Mining Drill Bits Market is segmented by drill bit type into Down-the-Hole (DTH) drill bits, tricone drill bits, rotary drill bits, diamond core drill bits, PDC drill bits, carbide button bits, roller-cone drill bits, reverse-circulation drill bits and top-hammer drill bits. DTH drill bits represent a leading category because of their suitability for hard-rock surface drilling, blast-hole drilling, exploration and production applications. Saudi Arabia’s expanding drilling activity provides a broad application base for DTH tooling, particularly where high penetration, hole accuracy and reliable flushing are required. Government data indicates that drilling expenditure reached SAR 230 million, while the Kingdom recorded 933 exploration locations across gold and base-metal targets. Gold production of 16,293 kg and copper concentrate production of 74,000 tonnes further demonstrate the operational base requiring drilling consumables. Diamond-core tooling remains important for geological exploration, while tricone and rotary bits are relevant to larger production and blasting operations. The segmentation therefore reflects differences in rock formation, drilling depth, hole diameter, penetration requirements, bit life and drilling method rather than a single technology being applicable across all Saudi mining environments.
By Mining Application
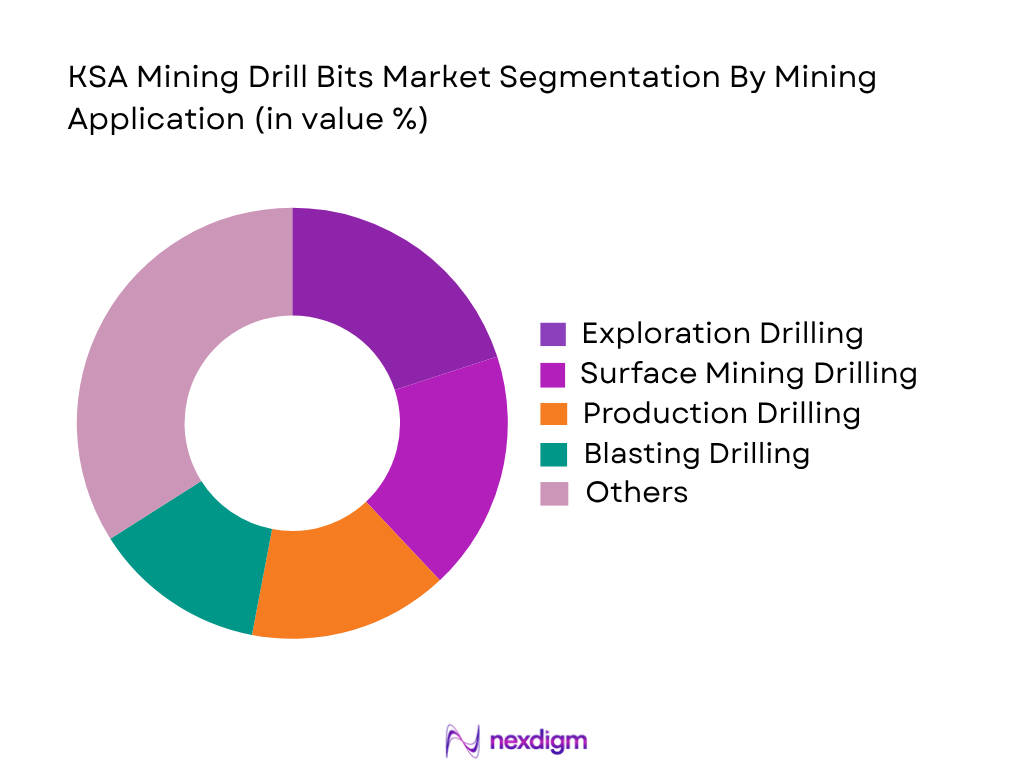
The KSA Mining Drill Bits Market is segmented by mining application into surface mining drilling, underground mining drilling, exploration drilling, production drilling, blasting drilling, grade-control drilling, resource-definition drilling, mine-development drilling, quarry drilling and geotechnical and geological drilling. Exploration drilling represents a strategically important application because Saudi Arabia is actively expanding geological investigation and licensing activity for gold, copper, zinc, silver and other minerals. The Kingdom recorded 933 exploration locations, including 691 locations for gold and associated minerals and 242 locations for base metals. Exploration expenditure reached SAR 770 million, with drilling accounting for SAR 230 million, directly establishing a measurable activity base for exploration drilling consumables. Production drilling is also supported by operating mines, including the Mansourah-Massarah gold operation and Jabal Sayid copper operation. Surface and blasting applications remain relevant because Saudi Arabia produces substantial quantities of minerals and construction materials, including 51 million tonnes of hydraulic cement, 5.5 million tonnes of metallurgical-grade bauxite and 10 million tonnes of phosphate rock.
Competitive Landscape
The KSA Mining Drill Bits Market comprises global mining-equipment and drilling-tool manufacturers supplying DTH, rotary, tricone, diamond and related drilling technologies through direct operations, distributors, equipment partnerships and aftermarket networks. Competitive differentiation is primarily associated with bit design, penetration performance, wear resistance, compatibility with drilling rigs, technical support and replacement availability. The market is closely connected to Saudi Arabia’s expanding exploration ecosystem: the Ministry reported SAR 230 million in drilling expenditure and 933 exploration locations, while six exploration opportunities announced in 2024 covered more than 940 square kilometers.
| Company | Establishment Year | Headquarters | Core Drill Bit Portfolio | DTH Capability | Exploration Tooling | Aftermarket Support | Mining Application Coverage | KSA Presence |
| Epiroc | 2018 | Stockholm, Sweden | ~ | ~ | ~ | ~ | ~ | ~ |
| Sandvik Mining and Rock Solutions | 2012* | Sandviken, Sweden | ~ | ~ | ~ | ~ | ~ | ~ |
| Caterpillar | 1925 | Irving, Texas, USA | ~ | ~ | ~ | ~ | ~ | ~ |
| Boart Longyear | 1890 | Salt Lake City, Utah, USA | ~ | ~ | ~ | ~ | ~ | ~ |
| Mincon Group | 1977 | Shannon, Ireland | ~ | ~ | ~ | ~ | ~ | ~ |
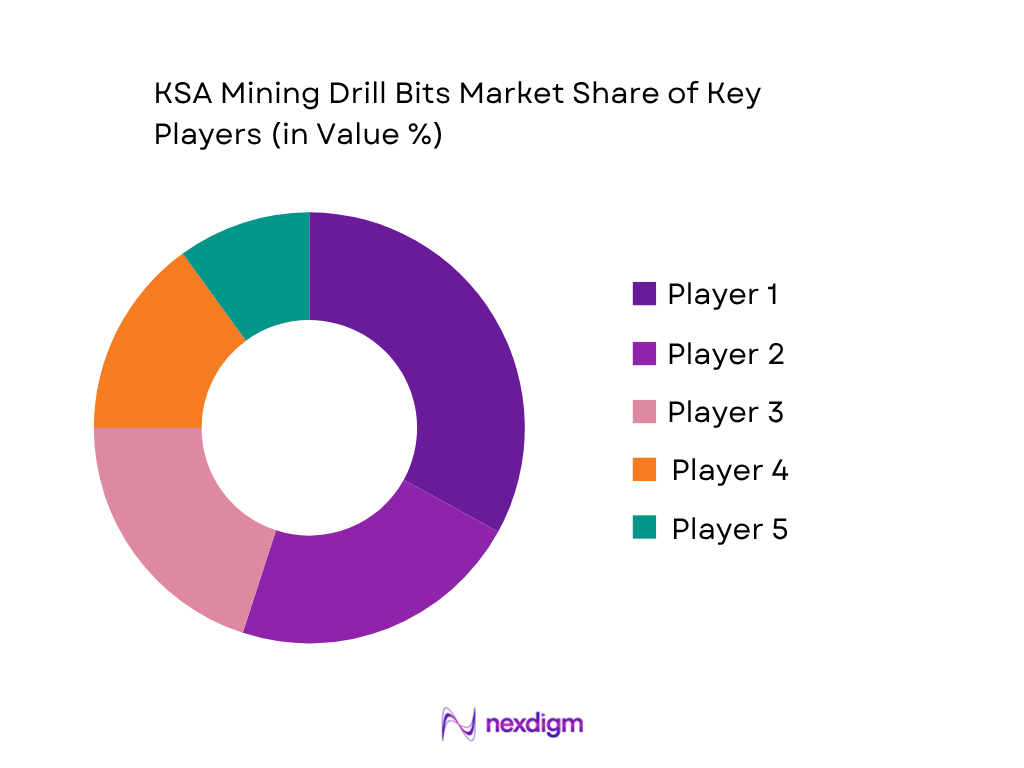
KSA Mining Drill Bits Market Analysis
Growth Drivers
Expansion of Mineral Exploration and Drilling Activity
The KSA Mining Drill Bits Market is being supported by the rapid expansion of mineral exploration and drilling activity across the Kingdom. Total mineral exploration spending reached SAR 1.05 billion in 2024, compared with SAR 501 million in 2023, while expenditure specifically allocated to drilling increased from SAR 152 million to SAR 230 million. The country has 933 exploration locations, including 691 locations associated with gold and related minerals and 242 locations associated with base metals such as copper and zinc. These figures directly expand the operating base for DTH, diamond-core, reverse-circulation and rotary drill bits because exploration programs require repeated drilling across prospective formations. The country produced 16,293 kg of mined gold, 74,000 tonnes of copper concentrate measured by copper content, and 10 million tonnes of phosphate rock in 2024. The scale of mineral exploration and production activity increases requirements for penetration tools, replacement bits and application-specific drilling consumables. Government exploration initiatives, geological mapping and licensing programs therefore provide a structural demand foundation for mining drill-bit suppliers serving Saudi Arabia. Continued exploration of gold and base-metal prospects is also expected to increase the number of drilling campaigns requiring consumable tooling. New exploration licenses can create additional requirements for geological drilling before deposits progress toward resource definition and commercial evaluation. This creates a recurring demand cycle extending from initial exploration through feasibility studies, mine development and production drilling.
Growth of Mining Production and Large-Scale Industrial Projects
The KSA Mining Drill Bits Market is benefiting from the expansion of mineral production and associated industrial development, which increases requirements for production drilling, blast-hole drilling, quarry drilling and mine-development activities. Saudi Arabia produced 5.5 million tonnes of metallurgical-grade bauxite, 1.9 million tonnes of alumina, 745,000 tonnes of primary aluminum, 6.9 million tonnes of direct-reduced iron and 51 million tonnes of hydraulic cement in 2024. Gold production reached 16,293 kg, increasing from 13,476 kg in 2023, while copper concentrate production reached 74,000 tonnes of contained copper, compared with 72,000 tonnes previously. The mining and quarrying sector contributed 0.4% of national GDP, while construction contributed 7.7%, illustrating the connection between mineral extraction, construction materials and industrial activity. The Kingdom’s nominal GDP was approximately USD 1.25 trillion in 2024. Continued development of mining, metallurgy, construction and infrastructure creates drilling requirements across surface mines, quarries and exploration sites. These conditions support recurring consumption of DTH, tricone, rotary, carbide and other specialized drill bits. Increasing production activity can also raise the frequency of blast-hole drilling and equipment utilization, directly influencing bit replacement requirements. Expansion of mineral-processing facilities can further encourage development of upstream mining operations and associated drilling capacity. As operators seek higher productivity, demand can increasingly shift toward longer-life bits, optimized cutting structures and tooling designed for specific geological conditions.
Market Challenges
Dependence on Specialized Imported Drilling Technologies and Supply-Chain Requirements
The KSA Mining Drill Bits Market faces supply-chain challenges because advanced drilling tools frequently require specialized manufacturing capabilities, engineered carbide components, precision machining and application-specific technical support. Saudi Arabia’s overall goods imports reached approximately USD 233 billion in 2024, compared with USD 207 billion in 2023, demonstrating the scale of the Kingdom’s dependence on international supply networks for industrial products and equipment. Imports of base metals and related articles reached USD 22 billion, while imports of precious stones and metals reached USD 10 billion. Mining drill-bit suppliers must therefore maintain reliable logistics for tooling, replacement components and technical equipment serving geographically dispersed mine sites. The challenge is particularly relevant to high-performance DTH, diamond-core and specialized rotary products where specifications can vary according to rock hardness, drilling diameter and rig configuration. Delays in international shipping, inventory planning and specialized replacement-tool availability can affect drilling continuity. As Saudi exploration programs expand, suppliers need localized inventory, technical service capabilities and responsive aftermarket networks to minimize operational interruptions. Maintaining sufficient inventories of different shank configurations, carbide grades and bit diameters can also increase logistical complexity for distributors and mining contractors. Remote mining locations may require additional inventory buffers to prevent downtime caused by replacement-tool shortages. Suppliers therefore face increasing pressure to establish efficient regional warehousing, technical support and rapid replacement systems capable of supporting continuous drilling operations.
Complexity of Hard-Rock Drilling Conditions and Bit Wear Management
The KSA Mining Drill Bits Market faces operational challenges associated with variable geological formations, high rock hardness, drilling depth, hole diameter and the requirement for consistent penetration performance. Saudi Arabia’s exploration ecosystem includes extensive gold, copper, zinc and polymetallic mineralization across the Arabian Shield, creating differing requirements for diamond-core, DTH, rotary and reverse-circulation tooling. The country has 933 exploration locations, including 242 base-metal locations, demonstrating the geographical and geological diversity of drilling activity. Production data further illustrates the range of applications, with Saudi Arabia producing 16,293 kg of gold, 74,000 tonnes of contained copper in concentrates, 5.5 million tonnes of metallurgical bauxite and 10 million tonnes of phosphate rock in 2024. Each commodity and geological environment can require different bit configurations, carbide grades, button profiles and drilling parameters. Excessive wear can reduce penetration rates and increase drilling interruptions, while inappropriate bit selection can increase replacement frequency and reduce equipment utilization. Consequently, mining contractors must balance penetration performance, bit life, flushing efficiency and hole quality. Suppliers with application-specific engineering and field support capabilities can address these operational requirements across Saudi Arabia’s diverse mining environments. High-temperature and abrasive formations can accelerate wear on cutting structures and carbide buttons, increasing the importance of correct bit selection. Differences in drilling depth, formation hardness and water or air-flushing conditions can also affect operating performance. Consequently, manufacturers must provide technically differentiated products rather than relying on standardized drill-bit configurations across all mining applications.
Market Opportunities
Expansion of Exploration Licensing and Untapped Mineral Resources
The KSA Mining Drill Bits Market presents an opportunity through the Kingdom’s expanding exploration pipeline and development of previously underexplored mineral areas. Mineral exploration spending reached SAR 1.05 billion in 2024, compared with SAR 501 million in 2023, while drilling expenditure reached SAR 230 million compared with SAR 152 million previously. The country has 933 exploration locations, consisting of 691 gold-related locations and 242 base-metal locations. Preliminary assessments indicate mineral potential of approximately 67 million ounces of gold, 3.87 million tonnes of copper and 5.24 million tonnes of zinc, creating a substantial exploration base for drilling contractors and tooling suppliers. Committed exploration expenditure across eight tender rounds reached SAR 1.2 billion, while foreign or consortium bidders represented 66% of participants in those tender rounds. This international participation can increase demand for internationally compatible drilling technologies and specialized consumables. The opportunity extends beyond initial exploration because successful discoveries can progress toward resource definition, feasibility drilling, mine development and production. Drill-bit suppliers can therefore address multiple stages of the mining lifecycle through DTH, diamond-core, reverse-circulation, rotary and specialized geological drilling products. Exploration expansion also creates opportunities for suppliers offering complete tooling programs rather than individual drill-bit products. Manufacturers can combine bit selection, drilling optimization, field testing and replacement planning to support exploration contractors across different geological formations. As exploration areas move through successive project stages, suppliers may develop longer-term relationships with operators and drilling contractors, creating recurring aftermarket demand.
Technology Upgrades, Digital Drilling and High-Performance Tooling
The KSA Mining Drill Bits Market offers opportunities for advanced tooling as Saudi mining operations increasingly emphasize drilling productivity, equipment utilization and operational efficiency. Drilling expenditure reached SAR 230 million in 2024, while total exploration expenditure reached SAR 1.05 billion, demonstrating a substantial base of drilling-intensive activity. Saudi Arabia also recorded 16,293 kg of gold production, 74,000 tonnes of contained copper production, 10 million tonnes of phosphate-rock production and 5.5 million tonnes of metallurgical-grade bauxite production during the same period. These activities create requirements for drill bits capable of maintaining performance across different formations and drilling applications. Suppliers can develop opportunities through optimized carbide grades, advanced button geometries, application-specific DTH configurations, diamond-core technologies, condition monitoring and drilling-performance analytics. Digital drilling systems can support real-time assessment of penetration, vibration, torque and bit condition, helping contractors determine when tooling should be changed or operating parameters adjusted. Saudi Arabia’s national nominal GDP reached approximately USD 1.25 trillion in 2024, while construction represented 7.7% of GDP. Mining-tool suppliers can therefore pursue integrated equipment-and-consumables strategies combining drill bits, technical services, digital monitoring and localized aftermarket support. Automated drilling equipment can further increase the importance of consistent bit performance because automated systems depend on predictable drilling parameters and tooling behavior. Data-based bit selection can help contractors compare penetration performance, operating hours and wear patterns across different formations. This creates an opportunity for suppliers to differentiate through engineering services, digital diagnostics, application-specific tooling and integrated aftermarket programs rather than competing solely on individual drill-bit specifications.
Future Outlook
The KSA Mining Drill Bits Market is positioned around the expansion of mineral exploration, mine development and drilling-intensive extraction activities. Saudi Arabia is using mining as part of its broader economic diversification strategy, while government programs continue to introduce exploration areas and investment opportunities. The Kingdom’s mineral exploration ecosystem already includes 933 identified exploration locations, and drilling expenditure has reached SAR 230 million. Exploration licensing activity covering areas exceeding 1,000 square kilometers and mineralized belts containing gold, copper and zinc provides an expanding operational base for drilling contractors and tooling suppliers.
Future demand is expected to increasingly emphasize high-penetration DTH bits, diamond-core exploration tooling, wear-resistant carbide configurations, longer operating life and application-specific bit designs. Digital drilling optimization, automated rigs and condition-based replacement can further influence purchasing decisions as mining operators seek greater drilling productivity and reduced downtime.
Major Players
- Epiroc Saudi Arabia
- Sandvik Mining and Rock Solutions Saudi Arabia
- Caterpillar Saudi Arabia
- Boart Longyear
- Mincon Group plc
- Furukawa Rock Drill Co., Ltd.
- Komatsu Middle East
- Robit Plc
- Rockmore International
- Halco Rock Tools
- Mitsubishi Materials Corporation
- Kennametal Inc.
- Center Rock Inc.
- DATC Group
- Drill Corp Saudi
Key Target Audience
- Mining Companies and Mine Operators
- Mineral Exploration and Geological Drilling Contractors
- Mining Equipment Manufacturers and Distributors
- Investments and Venture Capitalist Firms
- Government and Regulatory Bodies (Ministry of Industry and Mineral Resources, Saudi Geological Survey, Ministry of Investment)
- Quarrying and Construction-Material Producers
- Drilling Equipment and Mining Aftermarket Suppliers
- Mining Technology and Automation Solution Providers
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves mapping the Saudi mining-drilling ecosystem across mineral producers, exploration companies, drilling contractors, equipment manufacturers, distributors and aftermarket suppliers. Key variables include drill-meter activity, exploration expenditure, mine production, drilling methods, bit consumption, replacement cycles, rock formation, hole diameter and application-specific tooling requirements.
Step 2: Market Analysis and Construction
Historical market information is compiled through bottom-up assessment of mining activity, exploration programs, drilling expenditure, operating mines and drilling applications. Production volumes for gold, copper, phosphate, bauxite and other relevant minerals are assessed alongside exploration-license activity to establish the operational base supporting drill-bit consumption.
Step 3: Hypothesis Validation and Expert Consultation
Market hypotheses are validated through consultations with mining companies, drilling contractors, equipment distributors and drilling-tool specialists. Discussions focus on bit selection, penetration rates, wear patterns, replacement frequency, preferred manufacturers, equipment compatibility, procurement practices and aftermarket requirements across Saudi mining applications.
Step 4: Research Synthesis and Final Output
The final stage integrates supply-side and demand-side findings into a structured market model covering drill-bit types, mining applications, mineral commodities and geographic demand centers. Government mining statistics and company-level operational information are cross-checked to improve consistency before deriving market estimates and future scenarios.

- Executive Summary
- Research Methodology (Market Definition and Scope, KSA Mining Drill Bits Market Classification, Drill Bit Technology Mapping, Rock Drilling Application Assessment, Down-the-Hole (DTH) Drill Bit Evaluation, Tricone Drill Bit Assessment, Rotary Drill Bit Analysis, Diamond Core Drill Bit Evaluation, PDC Drill Bit Assessment, Carbide Button Bit Analysis, Roller-Cone Drill Bit Evaluation, Reverse-Circulation Drill Bit Assessment, Drill String Compatibility Analysis, Drill Bit Material and Carbide Grade Assessment, Rock Formation and Drilling Condition Mapping, Penetration Rate Assessment, Bit Life and Wear Analysis, Drilling Meterage Assessment, Exploration Drilling Evaluation, Production Drilling Assessment, Blasting Drilling Analysis, Quarry Drilling Assessment, Mining Contractor Demand Assessment, Supply-Side Assessment, Demand-Side Assessment, Primary Industry Interviews, Data Triangulation, Forecasting Framework)

- Definition and Scope
- KSA Mining Drill Bits Industry Evolution and Development of Modern Rock Drilling Practices, Mineral Exploration Expansion, Gold Mining Development, Copper and Zinc Mining Expansion, Phosphate Mining Development, Bauxite and Alumina Production, Underground Mining Advancement, Surface Mining Development
- Mining Drill Bits Value Chain Analysis
- Mining Drill Bits Supply Chain Analysis
- Carbide and Tungsten Material Suppliers, Steel and Alloy Suppliers, Drill Bit Manufacturers, DTH Tool Manufacturers, Tricone Bit Manufacturers, Diamond Core Tooling Suppliers, Drilling Rig Manufacturers, Drilling Equipment Distributors, Mining Equipment Dealers, Exploration Drilling Contractors, Production Drilling Contractors, Mining Companies, Quarry Operators

- Growth Drivers (Expansion of Mineral Exploration, Development of Gold and Base-Metal Mines, Growth of Phosphate and Bauxite Mining, Vision 2030 Mining Diversification, Expansion of Mining Investments, Increasing Hard-Rock Drilling Requirements, Development of Strategic Minerals, Growth of Exploration Drilling)
- Market Challenges (Fluctuation in Mining Activity, Complex Arabian Shield Geology, Dependence on Imported Drilling Technologies, High Wear in Hard-Rock Formations, Drill-Bit Replacement Requirements, Specialized Technical Expertise Requirements, Remote Mine Logistics, Equipment Compatibility Constraints, Supply-Chain Lead-Time Risks, Environmental and Mining Compliance Requirements)
- Market Opportunities (Expansion of Mineral Exploration Programs, Development of New Gold and Copper Deposits, Critical Mineral Exploration, Advanced DTH Technologies, High-Performance Diamond Core Bits, Automated Drilling Systems, Digital Drill-Bit Performance Monitoring, Local Mining Equipment Supply Chains, Advanced Carbide and Wear-Resistant Technologies, Expansion of Mining Contractor Services)
- Market Trends (Shift Toward High-Penetration Drill Bits, Increasing DTH Adoption, Digital Drilling Optimization, Automated Drilling Equipment, Increasing Exploration Drilling, Hard-Rock Tooling Development, Extended Bit-Life Technologies, Condition-Based Bit Replacement, Integrated Drill-Rig and Bit Systems, Increasing Demand for Specialized Exploration Tools)
- Government Regulations and Standards (Saudi Mining Investment Law, Ministry of Industry and Mineral Resources Mining Licensing Framework, Exploration Licensing Requirements, Mining Investment Enabling Program, Saudi Geological Survey Requirements, Environmental Compliance Requirements, Mine Rehabilitation Requirements, Occupational Health and Safety Standards, Explosives and Blasting Regulations, Local Content Requirements)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Competition Ecosystem

- By Market Value (2020-2025)
- By Volume Consumption (2020-2025)
- By Average Selling Price (2020-2025)
- By Drill Bit Consumption Volume (2020-2025)
- By DTH Drill Bit Consumption Volume (2020-2025)
- By Tricone Drill Bit Consumption Volume (2020-2025)
- By Diamond Core Drill Bit Consumption Volume (2020-2025)
- By Rotary Drill Bit Consumption Volume (2020-2025)
- By Exploration Drilling Consumption Volume (2020-2025)
- By Production and Blasting Drilling Consumption Volume (2020-2025)

- By Drill Bit Type (In Value %)
Down-the-Hole (DTH) Drill Bits
Tricone Drill Bits
Rotary Drill Bits
Diamond Core Drill Bits
PDC Drill Bits
Carbide Button Bits
Roller-Cone Drill Bits
Reverse-Circulation Drill Bits
Top-Hammer Drill Bits - By Drilling Method (In Value %)
DTH Drilling
Rotary Drilling
Rotary-Blasthole Drilling
Top-Hammer Drilling
Diamond Core Drilling
Reverse-Circulation Drilling
Air-Core Drilling
Percussion Drilling - By Mining Application (In Value %)
Surface Mining Drilling
Underground Mining Drilling
Exploration Drilling
Production Drilling
Blasting Drilling
Grade-Control Drilling
Resource-Definition Drilling
Mine-Development Drilling
Quarry Drilling
Geotechnical and Geological Drilling - By Mineral Commodity (In Value %)
Gold Mining
Copper Mining
Zinc Mining
Phosphate Mining
Bauxite Mining
Iron Ore Mining
Industrial Minerals Mining
Rare Earth and Critical Minerals Exploration - By End-User Type (In Value %)
Mining Companies
Mineral Exploration Companies
Mining Drilling Contractors
Quarrying Companies
Construction Material Producers
Government-Owned Mining Enterprises
Private Mining Operators
Geological Survey and Exploration Contractors - By Region (In Value %)
Riyadh Region
Makkah Region
Madinah Region
Eastern Province
Tabuk Region
Asir Region
Najran Region
Jazan Region
Hail Region
Al-Qassim Region

- Market Share of Major Players (By KSA Revenue, Drill Bit Product Portfolio, DTH Technology Coverage, Rotary Drilling Capability, Diamond Core Tooling Coverage, Mining Application Coverage, Exploration Drilling Capability, Production Drilling Capability, Manufacturing Capacity, Distribution Network, Aftermarket Service Coverage, Technical Support Capability, Mining Contractor Relationships, Regional Presence)
- Cross Comparison Parameters (Drill Bit Portfolio Breadth, DTH Bit Technology Capability, Tricone and Roller-Cone Technology Coverage, Diamond Core Bit Capability, Hard-Rock Drilling Performance, Exploration Tooling Capability, Aftermarket and Technical Service Reach, KSA Mining Customer Coverage)
- SWOT Analysis of Major Players
- Competitive Positioning Matrix
- Drill Bit Technology and Mining Application Benchmarking
- DTH and Rotary Drilling Technology Assessment
- Exploration and Diamond Core Drilling Technology Assessment
- Gold, Copper and Base-Metal Drilling Application Assessment
- Drill Bit Wear, Penetration and Productivity Assessment
- Mining Contractor and Aftermarket Service Ecosystem Assessment
- Detailed Profiles of Major Companies
Epiroc Saudi Arabia
Sandvik Mining and Rock Solutions Saudi Arabia
Caterpillar Saudi Arabia
Boart Longyear
Mincon Group plc
Furukawa Rock Drill Co., Ltd.
Komatsu Middle East
Robit Plc
Rockmore International
Halco Rock Tools
Mitsubishi Materials Corporation
Kennametal Inc.
Center Rock Inc.
DATC Group
Drill Corp Saudi

- Gold Mining Drilling Requirement Assessment
- Copper and Zinc Mining Drilling Demand Analysis
- Phosphate Mining Drilling Requirement Assessment
- Bauxite Mining Drilling Application Evaluation
- Mineral Exploration Contractor Demand Analysis
- Underground Mining Drilling Requirement Assessment
- Surface Mining and Blasting Requirement Analysis
- Quarry Drilling Demand Assessment
- Grade-Control Drilling Requirement Evaluation
- Resource-Definition Drilling Assessment
- Mining Equipment Distributor Procurement Analysis
- Drill Bit Replacement and Aftermarket Demand Assessment
- Drill Bit Performance and Bit-Life Preference Analysis
- Technical Service and Field-Support Requirement Assessment

- By Market Value (2026-2035)
- By Volume Consumption (2026-2035)
- By Average Selling Price (2026-2035)
- By Drill Bit Consumption Volume (2026-2035)
- By DTH Drill Bit Consumption Volume (2026-2035)
- By Tricone Drill Bit Consumption Volume (2026-2035)
- By Diamond Core Drill Bit Consumption Volume (2026-2035)
- By Rotary Drill Bit Consumption Volume (2026-2035)
- By Exploration Drilling Consumption Volume (2026-2035)
- By Production and Blasting Drilling Consumption Volume (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
