
 Download PDF
Market Overview
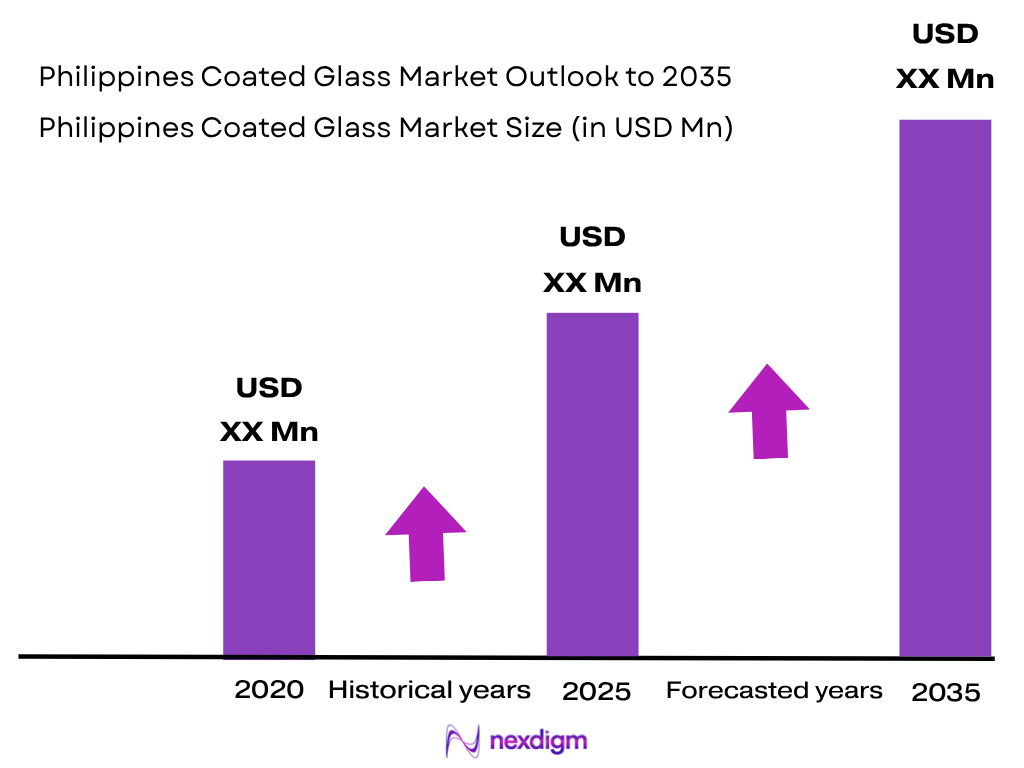
The Philippines coated glass market is valued at approximately USD ~420 million in 2024, supported by increasing demand for energy-efficient architectural glazing, solar control solutions, and advanced façade systems across commercial, residential, hospitality, and infrastructure developments. The market expansion is driven by rapid urbanization, construction activity, green building requirements, and rising demand for thermal performance solutions in tropical climatic conditions. According to the World Bank, the Philippines recorded a GDP of approximately USD 461 billion in 2024, reflecting strong economic activity supporting construction and real estate development. The Philippine Statistics Authority reported that the construction sector remained a key contributor to economic expansion, supported by infrastructure and private building investments. The adoption of coated glass is increasing as developers seek materials that improve energy efficiency, reduce cooling loads, and comply with sustainable building standards.
The Philippines coated glass market is primarily concentrated in Metro Manila, Cebu, and Calabarzon due to their high concentration of commercial buildings, residential developments, industrial facilities, and infrastructure projects. Metro Manila dominates demand because of extensive high-rise condominium construction, business districts, shopping malls, and corporate developments. Cebu represents a major growth center due to tourism infrastructure, hospitality projects, and commercial expansion. Calabarzon benefits from industrial parks, manufacturing facilities, and residential developments driven by proximity to Metro Manila. According to the Philippine Statistics Authority, the country’s population exceeded 115 million people in 2024, supporting continued urban development and housing demand. The Department of Public Works and Highways recorded continued infrastructure investment activity, strengthening demand for architectural glass applications across transportation, commercial, and public infrastructure projects.
Market Segmentation
By Product Type
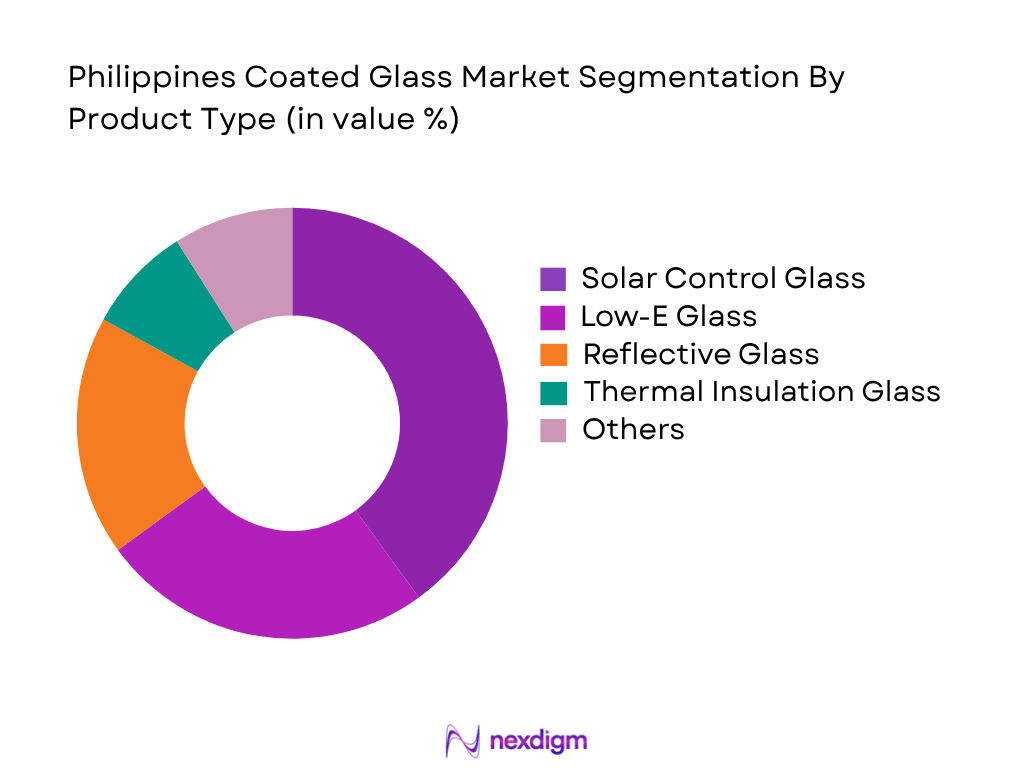
The Philippines coated glass market is segmented by product type into Solar Control Glass, Low-E Glass, Reflective Glass, Thermal Insulation Glass, Anti-Reflective Glass, Self-Cleaning Glass, and Decorative Coated Glass. Solar Control Glass holds the dominant market position due to the country’s tropical climate, high solar radiation exposure, and increasing requirement for reducing indoor heat gain in commercial and residential buildings. Developers of office towers, shopping malls, and condominiums increasingly use solar control coated glass to improve occupant comfort and reduce dependence on cooling systems. Low-E glass is gaining adoption due to rising awareness of energy-efficient buildings and sustainable construction practices. Reflective glass remains important in commercial façades due to its aesthetic appearance and solar performance characteristics.
By Application
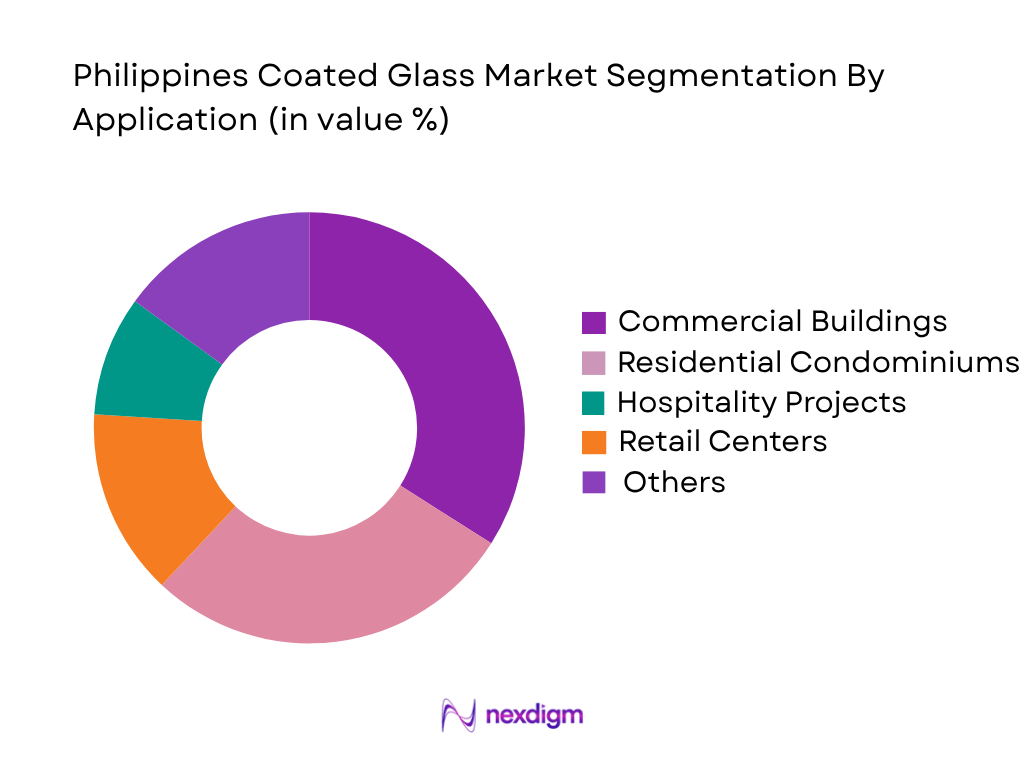
The Philippines coated glass market is segmented by application into Commercial Buildings, Residential Condominiums, Hospitality Projects, Retail Centers, Healthcare Facilities, Industrial Buildings, Transportation Infrastructure, and Solar Energy Projects. Commercial buildings represent the largest application segment due to extensive office construction, business district expansion, and demand for modern façade systems. Metro Manila’s business districts require advanced glazing solutions for office towers and mixed-use developments. Residential condominiums are also a major demand contributor due to increasing urban housing requirements and vertical development. Hospitality projects are expanding because of tourism growth and investment in hotels and resorts. Coated glass adoption is increasing across these applications because of its ability to provide thermal control, architectural aesthetics, and improved building performance.
Competitive Landscape
The Philippines coated glass market consists of international glass manufacturers, regional suppliers, and local processing companies. Competition is driven by product performance, coating technology capability, import supply networks, fabrication capacity, and relationships with developers, architects, and façade contractors. Global players maintain strong positions through advanced Low-E and solar control technologies, while domestic processors support customization, fabrication, and project execution requirements.
| Company | Establishment Year | Headquarters | Product Portfolio | Coating Technology | Philippines Presence | Processing Capability | Application Focus | Distribution Network |
| Saint-Gobain | 1665 | France | ~ | ~ | ~ | ~ | ~ | ~ |
| AGC Glass | 1907 | Japan | ~ | ~ | ~ | ~ | ~ | ~ |
| Guardian Glass | 1932 | USA | ~ | ~ | ~ | ~ | ~ | ~ |
| NSG Group (Pilkington) | 1918 | Japan | ~ | ~ | ~ | ~ | ~ | ~ |
| Xinyi Glass | 1988 | China | ~ | ~ | ~ | ~ | ~ | ~ |
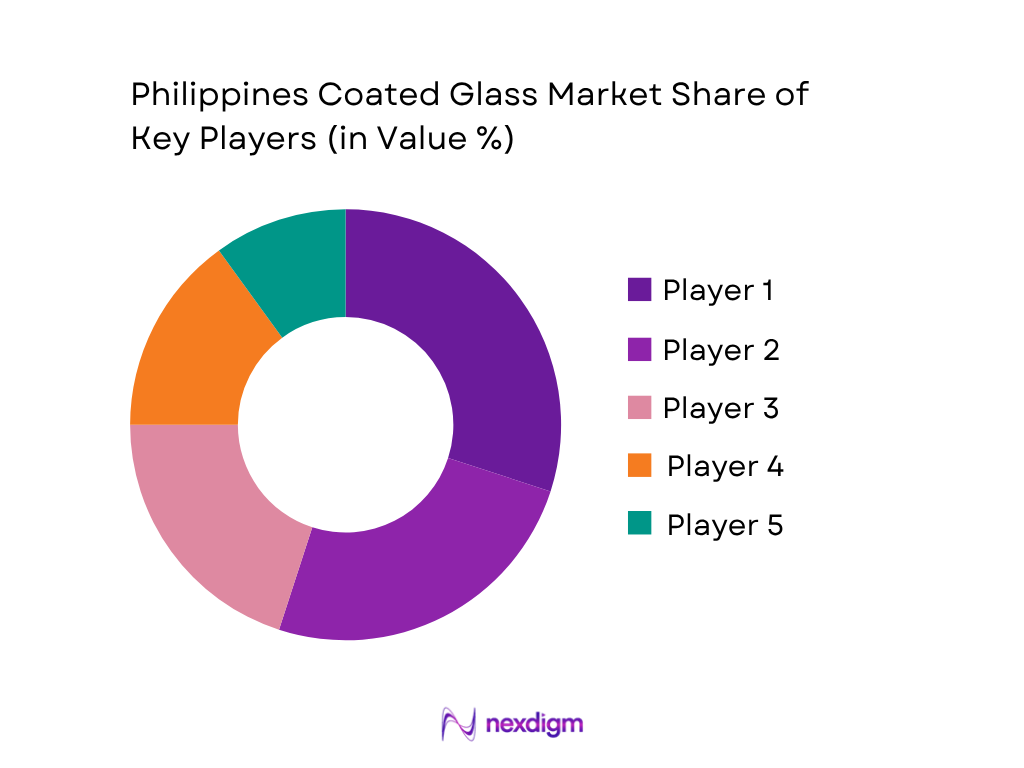
Philippines Coated Glass Market Analysis
Growth Drivers
Expansion of Commercial Real Estate, High-Rise Construction and Infrastructure Development
The expansion of commercial buildings, residential condominiums, hospitality assets, and infrastructure projects is strengthening demand for coated glass solutions in the Philippines, particularly for applications requiring solar control, thermal insulation, and improved façade performance. The country’s construction ecosystem remains a key contributor to coated glass demand, supported by economic activity and urban development. According to the World Bank, the Philippines recorded a GDP of approximately USD 461 billion in 2024, supported by services, industry, and construction-related activities. The Philippine Statistics Authority reported that the construction sector continued to contribute significantly to national economic output, driven by private building projects and government infrastructure programs. Metro Manila, Cebu, and Calabarzon remain major demand centers due to concentrated commercial developments, business districts, industrial parks, and residential projects. The National Economic and Development Authority highlighted continued infrastructure investment under national development programs, supporting demand for advanced construction materials. These developments increase the requirement for coated glass products such as solar control glass and Low-E glass, as developers prioritize energy-efficient façades, occupant comfort, and compliance with modern building performance standards.
Growing Adoption of Energy-Efficient Buildings and Sustainable Glazing Solutions
Increasing focus on energy conservation and sustainable construction practices is driving adoption of coated glass technologies across commercial and premium residential developments in the Philippines. The tropical climate creates significant cooling requirements, encouraging developers to use solar control glass and Low-E glass to reduce heat gain and improve building efficiency. According to the International Energy Agency, buildings account for a significant share of global energy consumption, increasing attention toward efficient building envelopes and advanced glazing systems. In the Philippines, the Energy Efficiency and Conservation Act has strengthened awareness regarding energy-saving technologies across commercial and industrial facilities. The World Bank reported that the Philippines’ urban population exceeded 50 million people in 2024, increasing demand for modern buildings, offices, and residential infrastructure requiring advanced materials. The Philippine Green Building Code and sustainability initiatives have encouraged developers to integrate energy-efficient construction solutions. Coated glass manufacturers benefit from this shift as architects and developers increasingly specify performance-oriented glazing systems for office towers, shopping malls, hotels, hospitals, and mixed-use developments requiring improved thermal control and reduced environmental impact.
Market Challenges
High Dependence on Imported Coated Glass and Limited Domestic Advanced Manufacturing Capability
The Philippines coated glass market faces challenges due to limited domestic production of advanced coated glass products and dependence on international suppliers for specialized solutions such as Low-E glass, solar control glass, and high-performance façade glass. Most advanced coating technologies require significant investments in magnetron sputtering equipment, specialized processing facilities, and technical expertise, limiting local manufacturing expansion. According to the Philippine Statistics Authority, the country’s manufacturing sector remained an important economic contributor, but specialized glass manufacturing capacity remains limited compared with other Asian economies. The World Bank reported that the Philippines imported significant volumes of manufactured goods to support industrial and construction activities, reflecting continued dependence on external supply chains. This import dependency exposes the market to logistics disruptions, foreign exchange fluctuations, and international supply constraints. Additionally, project developers often rely on global glass manufacturers for premium architectural applications due to established product certifications and performance standards. Developing local coated glass production capabilities requires investment in advanced technology, skilled workforce development, and consistent demand from large-scale construction projects.
Limited Awareness and Technical Adoption Barriers Among Small and Medium Construction Projects
The adoption of coated glass in the Philippines is constrained by limited awareness among smaller developers, contractors, and building owners regarding long-term energy savings and performance benefits compared with conventional glass products. Although coated glass provides advantages in solar heat reduction, thermal insulation, and improved building comfort, higher technical requirements related to specification, installation, and maintenance can restrict adoption outside premium projects. According to the Philippine Statistics Authority, the country had more than 1.1 million registered establishments in 2024, with a large portion consisting of small and medium enterprises involved in construction and related activities. Many smaller projects continue to prioritize initial construction costs rather than lifecycle building performance. The Department of Energy has emphasized the importance of energy efficiency measures across commercial and industrial sectors, but implementation varies depending on project scale and developer capability. Additionally, proper coated glass installation requires trained façade contractors and technical coordination between architects, engineers, and suppliers. These factors create barriers for wider penetration of advanced glazing solutions in smaller commercial, residential, and regional construction projects.
Market Opportunities
Growth of Green Buildings, Sustainable Construction and Energy-Efficient Retrofit Projects
The increasing focus on sustainable buildings presents significant opportunities for coated glass adoption in the Philippines, particularly through green building developments, commercial retrofits, and energy-efficient construction initiatives. Developers are increasingly incorporating materials that improve building performance, reduce cooling requirements, and support sustainability objectives. The Philippine Statistics Authority reported that the country’s population exceeded 115 million people in 2024, increasing demand for urban infrastructure, housing, and commercial facilities. The World Bank reported continued economic expansion supported by services, infrastructure, and private investment activity, creating opportunities for modern construction materials. The Philippines Green Building Council and government energy efficiency initiatives have encouraged adoption of environmentally responsible building practices. Existing commercial buildings also represent an opportunity for coated glass retrofit applications, particularly office towers, shopping malls, and hospitality properties seeking improved energy performance. Solar control glass and Low-E glass solutions can support modernization of existing structures by improving indoor comfort and reducing cooling dependency. This creates opportunities for manufacturers, processors, and façade specialists offering customized coated glass solutions for sustainable building projects.
Expansion of Local Glass Processing, Renewable Energy Applications and Advanced Architectural Solutions
Development of local glass processing capabilities and increasing demand for specialized glass applications create growth opportunities for the Philippines coated glass market. The expansion of construction, renewable energy, and infrastructure sectors is increasing demand for processed glass products with improved performance characteristics. According to the Department of Energy Philippines, renewable energy development continues to be a national priority, supporting demand for specialized glass applications in solar energy projects. The Philippines recorded renewable energy capacity expansion as part of its transition toward cleaner energy sources, creating potential opportunities for solar-related glass technologies. The World Bank reported that the Philippines maintained strong investment activity supported by infrastructure and private-sector development. Growth in high-rise buildings, airports, commercial complexes, and industrial facilities creates demand for advanced architectural glazing systems. Establishing stronger domestic processing networks can improve supply availability, reduce dependency on imported finished products, and enable customized solutions for tropical climate requirements. Opportunities exist for companies investing in glass fabrication, coating partnerships, façade engineering capabilities, and technology-driven glazing solutions supporting the country’s evolving construction ecosystem.
Future Outlook
The Philippines coated glass market is expected to experience steady growth during the forecast period, supported by urbanization, infrastructure expansion, green building adoption, and increasing demand for energy-efficient construction materials. Growth will be driven by rising use of solar control glass, Low-E glazing systems, premium façade solutions, and sustainable building technologies. The market is expected to register a CAGR of approximately ~7% during 2026-2035 due to continued construction activity and increasing adoption of advanced glazing solutions.
Major Players
- Saint-Gobain
- AGC Glass
- Guardian Glass
- NSG Group (Pilkington)
- Şişecam
- Vitro Architectural Glass
- Xinyi Glass
- Kibing Group
- Central Glass
- Taiwan Glass
- Asahi India Glass
- Emirates Glass
- Republic Glass Holdings Corporation
- Philippine Glass Processing Specialists
- Euroglass Philippines
Key Target Audience
- Architectural Glass Manufacturers and Fabricators
- Real Estate Developers and Construction Companies
- Façade Contractors and Building Envelope Specialists
- Investments and Venture Capitalist Firms (Philippine Investment Alliance for Infrastructure, Ayala Corporation Investment Holdings)
- Government and Regulatory Bodies (Department of Public Works and Highways, Department of Trade and Industry, Department of Energy Philippines, Philippine Green Building Council)
- Renewable Energy Developers and Solar Project Companies
- Construction Material Importers and Distributors
- Glass Processing Equipment and Technology Providers
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves developing an ecosystem map covering all major stakeholders operating within the Philippines coated glass market. This includes manufacturers, importers, processors, construction companies, developers, façade contractors, regulatory bodies, and end-use industries. Secondary research is conducted using government databases, industry publications, company reports, and construction project information to identify important market variables.
Step 2: Market Analysis and Construction
This phase involves analyzing historical demand patterns, product consumption trends, application distribution, import dependency, and supply chain structures. Market calculations are developed through bottom-up assessment of manufacturer activities, product volumes, processing capabilities, and project requirements. Demand-side evaluation includes analysis of commercial construction, residential developments, hospitality projects, and infrastructure investments.
Step 3: Hypothesis Validation and Expert Consultation
Market assumptions are validated through discussions with industry participants including glass manufacturers, processors, developers, architects, contractors, and distributors. These consultations provide operational insights regarding product preferences, technology adoption, procurement practices, and future demand trends within the Philippines coated glass ecosystem.
Step 4: Research Synthesis and Final Output
The final stage integrates primary and secondary research findings through data validation and triangulation. Information from supply-side assessment, demand analysis, regulatory review, and industry consultations is combined to develop a comprehensive market assessment covering market structure, segmentation, competition, and future growth opportunities.

- Executive Summary
- Research Methodology (Market Definition and Scope, Philippines Coated Glass Market Classification, Architectural Glass Demand Assessment, Solar Control Glass Consumption Mapping, Low-E Glass Adoption Assessment, Tropical Climate Glazing Requirement Analysis, Commercial Building Façade Glass Demand Assessment, Residential Condominium Glass Consumption Mapping, Infrastructure Development Glass Requirement Analysis, Automotive Glass Coating Demand Assessment, Renewable Energy Glass Application Assessment, Domestic Glass Processing Capacity Assessment, Coated Glass Import Dependency Analysis, Magnetron Sputtering and Pyrolytic Coating Technology Assessment)

- Definition and Scope
- Market Evolution and Industry Development
- Coated Glass Value Chain Analysis
- Coated Glass Supply Chain Analysis
- Coated Glass Application Ecosystem
- Market Demand Drivers and Industry Dynamics
- Architectural Glass Technology and Product Innovation Landscape
- Construction and Infrastructure Development Impact Assessment
- Competitive Landscape and Industry Participant Analysis

- Growth Drivers (Metro Manila High-Rise Construction Expansion, Philippine Green Building Adoption, Increasing Solar Heat Gain Reduction Requirement, Commercial Office Development, Residential Condominium Construction Growth, Hospitality Infrastructure Expansion, Infrastructure Modernization Projects, Energy Efficiency Requirements, Premium Architectural Façade Development)
- Market Challenges (High Dependence on Imported Coated Glass Products, Limited Domestic Advanced Coating Manufacturing Capacity, High Investment Requirement for Coating Facilities, Technical Specification Complexity, Limited Awareness Among Small Developers, International Supply Chain Dependence, Skilled Installation Requirements, Project-Based Construction Demand)
- Market Opportunities (Domestic Glass Processing Expansion, Green Building Certification Growth, Low-E Glass Adoption in Premium Developments, Energy Efficient Retrofit Solutions, Smart Glass Integration, Renewable Energy Glass Applications, Sustainable Construction Material Demand, Local Coated Glass Manufacturing Investment)
- Market Trends (Solar Control Glass Adoption, Low-E Glass Market Penetration, Sustainable Building Materials, High Performance Façade Systems, Smart Glass Integration, Double Glazed Unit Expansion, Large Format Architectural Glass Usage, Automated Glass Processing, Energy Efficient Building Design, Premium Residential Glazing)
- Regulatory and Standards Landscape (Philippine Green Building Code Requirements, Department of Public Works and Highways Building Regulations, Department of Trade and Industry Product Standards, Energy Efficiency and Conservation Act Requirements, National Building Code of the Philippines Compliance, Fire Safety Glass Regulations, Construction Material Quality Standards, Environmental Sustainability Requirements)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Competition Ecosystem

- By Market Value (2020-2025)
- By Coated Glass Consumption Volume (2020-2025)
- By Coated Glass Consumption Area (Million Sq. Meters) (2020-2025)
- By Architectural Coated Glass Consumption Volume (2020-2025)
- By Solar Control Glass Consumption Volume (2020-2025)
- By Low-E Glass Consumption Volume (2020-2025)
- By Reflective Glass Consumption Volume (2020-2025)
- By Insulated Glass Unit Compatible Coated Glass Consumption Volume (2020-2025)
- By Domestic Coated Glass Processing Volume (2020-2025)
- By Coated Glass Import Value (2020-2025)
- By Average Selling Price (2020-2025)

- By Coating Technology (In Value %)
Magnetron Sputtered Vacuum Coated Glass
Soft-Coated Low-E Glass
Hard-Coated Pyrolytic Glass
Online Coated Glass
Offline Coated Glass
Single Silver Low-E Coated Glass
Double Silver Low-E Coated Glass
Triple Silver Low-E Coated Glass
Solar Control Coating Technology
Reflective Coating Technology - By Product Type (In Value %)
Low-E Glass
Solar Control Glass
Reflective Glass
Anti-Reflective Glass
Self-Cleaning Glass
Thermal Insulation Glass
Decorative Coated Glass
Tinted Coated Glass
Safety Coated Glass
High Performance Architectural Glass - By Glass Configuration (In Value %)
Single Glazed Coated Glass
Double Glazed Insulated Glass Units
Triple Glazed Insulated Glass Units
Laminated Coated Glass
Tempered Coated Glass
Heat Strengthened Coated Glass
Curved Coated Glass
Large Format Coated Glass - By Application (In Value %)
Commercial Buildings
Residential Condominiums
Hospitality and Tourism Projects
Shopping Malls and Retail Centers
Healthcare Facilities
Educational Institutions
Government Buildings
Industrial Facilities
Airports and Transportation Infrastructure
Solar Energy Projects
Automotive Glass Applications - By End-Use Industry (In Value %)
Construction and Real Estate
Commercial Infrastructure
Residential Construction
Hospitality Sector
Retail Infrastructure
Healthcare Infrastructure
Industrial Buildings
Renewable Energy Sector
Automotive Industry
Transportation Infrastructure - By Distribution Channel (In Value %)
Direct Project Supply
Glass Fabricators and Processors
Façade Contractors
Architectural Glass Suppliers
Construction Material Distributors
OEM Supply Channels
Specialized Glass Importers and Trading Companies - By Region (In Value %)
National Capital Region
Central Luzon
Calabarzon
Central Visayas
Western Visayas
Northern Mindanao
Davao Region

- Market Share of Major Players (By Philippines Revenue, Coated Glass Sales Volume, Architectural Glass Sales Volume, Low-E Glass Sales Volume, Solar Control Glass Sales Volume, Import Supply Volume, Processing Capacity, Project Portfolio, End-Use Industry Coverage, Distribution Network Reach)
- Cross Comparison Parameters (Philippines Coated Glass Revenue, Low-E and Solar Control Glass Portfolio Breadth, Imported Glass Supply Network Strength, Local Glass Processing and Fabrication Capability, Tropical Climate Solar Control Performance Capability, High-Rise Façade Project Exposure, Green Building Specification Support Capability, Technical Consultation and Installation Support Network)
- SWOT Analysis of Major Players
- Competitive Positioning Matrix
- Coated Glass Product Portfolio Benchmarking
- Architectural Glass Performance and Energy Efficiency Benchmarking
- Coated Glass Pricing and Category Benchmarking
- Detailed Profiles of Major Companies
Saint-Gobain
AGC Glass
Guardian Glass
NSG Group (Pilkington)
Şişecam
Vitro Architectural Glass
Xinyi Glass
Kibing Group
Central Glass
Taiwan Glass
Asahi India Glass
Emirates Glass
Philippine Glass Processing Specialists
Republic Glass Holdings Corporation
Euroglass Philippines

- Metro Manila Commercial Developer Coated Glass Procurement Assessment
- High-Rise Condominium Developer Glass Specification Analysis
- Shopping Mall Architectural Glass Requirement Assessment
- Hospitality Sector Premium Glazing Demand Analysis
- Green Building Project Glass Requirement Assessment
- Government Infrastructure Glass Procurement Assessment
- Façade Contractor Coated Glass Installation Requirement Analysis
- Industrial Facility Thermal Insulation Glass Demand Assessment
- Automotive Glass Manufacturer Coated Glass Requirement Analysis
- Solar Energy Project Glass Procurement Assessment

- By Market Value (2026-2035)
- By Coated Glass Consumption Volume (2026-2035)
- By Coated Glass Consumption Area (Million Sq. Meters) (2026-2035)
- By Architectural Coated Glass Consumption Volume (2026-2035)
- By Solar Control Glass Consumption Volume (2026-2035)
- By Low-E Glass Consumption Volume (2026-2035)
- By Reflective Glass Consumption Volume (2026-2035)
- By Insulated Glass Unit Compatible Coated Glass Consumption Volume (2026-2035)
- By Domestic Coated Glass Processing Volume (2026-2035)
- By Coated Glass Import Value (2026-2035)
- By Average Selling Price (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
