
 Download PDF
Market Overview
The Philippines Compact Construction Equipment Market is valued at USD ~ billion in 2024, compared with USD ~ billion in 2023, supported by expanding construction activity, infrastructure development, urbanization, and increasing mechanization across project sites. Demand is driven by the need for equipment that can operate efficiently in confined areas while performing excavation, loading, grading, material handling, trenching, and site-preparation activities. Compact machines also provide contractors with greater equipment flexibility through interchangeable attachments, while rental availability improves access for small and medium-sized contractors. Infrastructure construction, residential development, commercial projects, utility installation, road rehabilitation, and public works continue to create recurring requirements for compact machinery. Increasing emphasis on project productivity, reduced manual labor requirements, transportability, and equipment utilization further supports market development. The market is also influenced by replacement demand as contractors and rental fleets modernize older machinery with newer equipment incorporating improved hydraulic systems, telematics, fuel efficiency, operator-assistance functions, and lower-emission powertrains.
The Philippines Compact Construction Equipment Market is concentrated around major construction and infrastructure centers, particularly Metro Manila, CALABARZON, Central Luzon, Cebu, and Davao. Metro Manila generates demand from high-density commercial, residential, transportation, utility, and redevelopment projects where compact equipment is advantageous because of restricted workspaces and congested urban conditions. CALABARZON and Central Luzon benefit from industrial parks, manufacturing facilities, logistics infrastructure, residential developments, and road connectivity projects. Cebu functions as a major construction and commercial center in the Visayas, while Davao serves as an important development hub in Mindanao. Equipment requirements vary across these locations according to construction intensity, project scale, terrain, road conditions, utility requirements, and availability of equipment dealerships and rental fleets. Regional infrastructure expansion is therefore supporting broader adoption beyond the capital region.
Market Segmentation
By Equipment Type
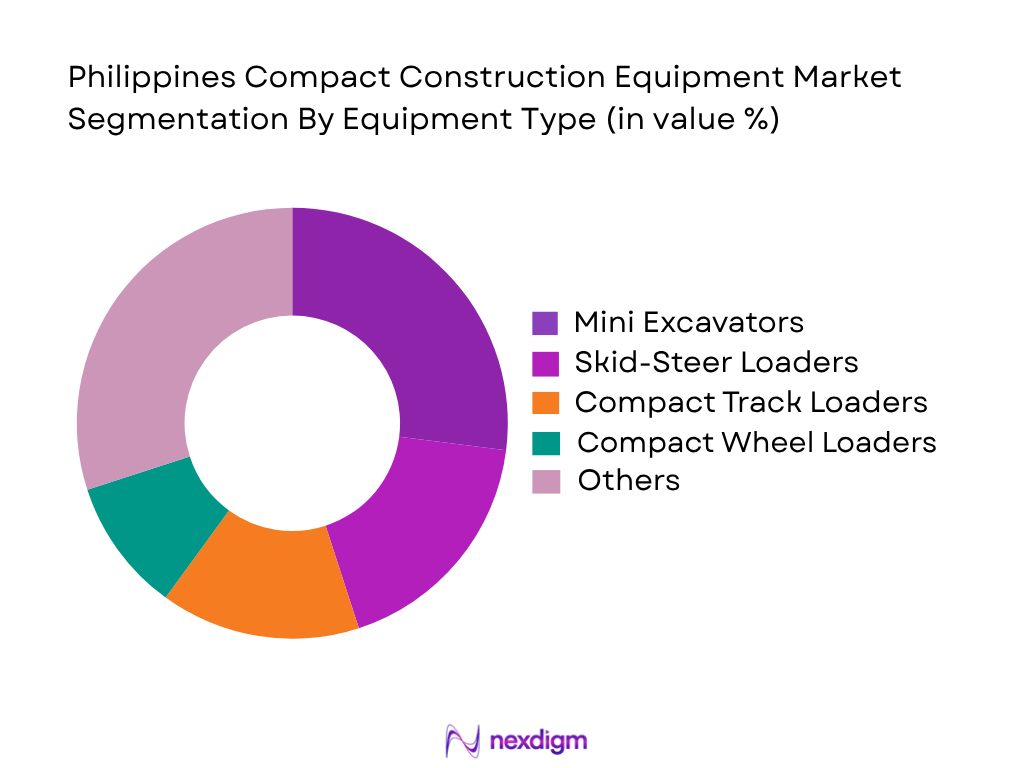
The Philippines Compact Construction Equipment Market is segmented by equipment type into mini excavators, skid-steer loaders, compact track loaders, compact wheel loaders, compact backhoe loaders, mini loaders, compact rollers, and small articulated loaders. Mini excavators represent the leading segment in the report framework because their compact dimensions, maneuverability, digging capability, and attachment compatibility make them suitable for residential construction, utility installation, drainage, landscaping, road maintenance, and foundation preparation. Their ability to operate in confined areas provides an advantage in urban and infrastructure environments where conventional excavators may have access limitations. Skid-steer loaders and compact track loaders also maintain substantial demand because their attachment flexibility enables excavation support, grading, loading, demolition, sweeping, and material-handling activities. Compact wheel loaders are relevant to construction logistics and material movement, while compact rollers support road and surface-compaction applications. Rental companies further support demand by purchasing versatile equipment that can be deployed across multiple contractor requirements.
By Application
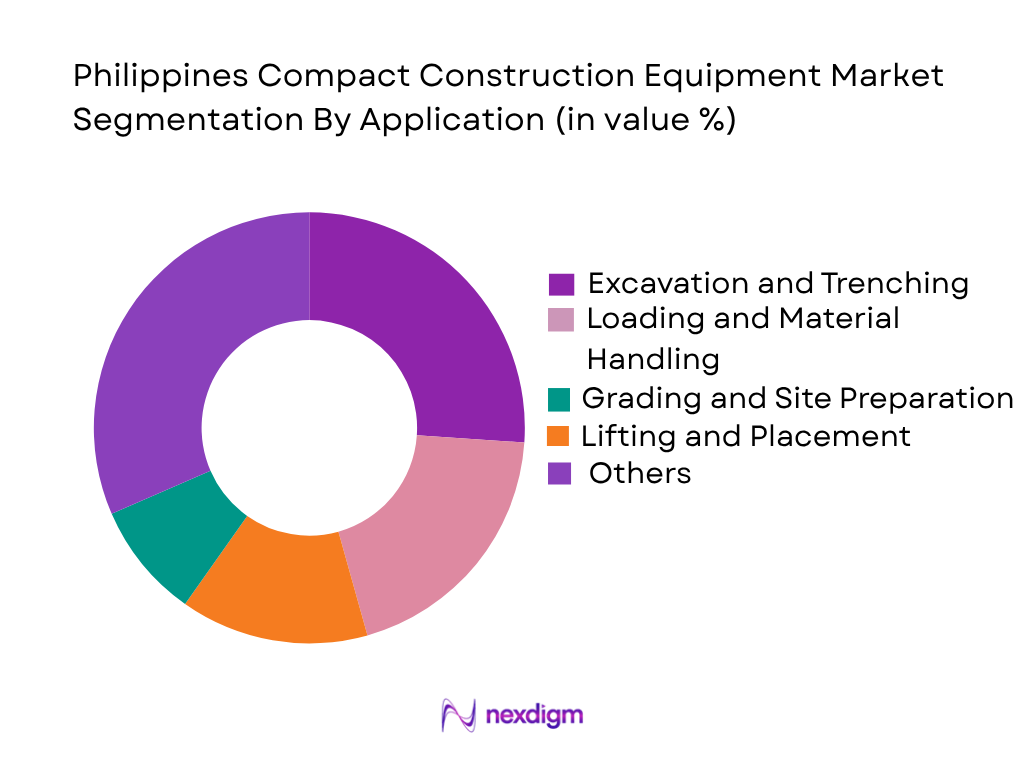
The Philippines Compact Construction Equipment Market is segmented by application into excavation and trenching, loading and material handling, grading and site preparation, lifting and placement, demolition, landscaping and grounds development, compaction, road construction and maintenance, utility installation and maintenance, and agricultural and land development. Excavation and trenching represent the leading application in the report framework because construction foundations, drainage, underground utilities, telecommunications infrastructure, and site preparation require equipment capable of operating within relatively restricted work areas. Mini excavators are particularly relevant because they combine digging performance with transportability and attachment flexibility. Loading and material handling represents another important application because compact loaders can move construction materials while supporting grading, site cleaning, landscaping, and demolition activities. Road construction and maintenance create requirements for compact rollers and loaders, while utility projects require maneuverable machinery for water, electricity, drainage, and telecommunications installations. The ability to deploy one machine across multiple applications through attachments further improves equipment utilization.
Competitive Landscape
The Philippines Compact Construction Equipment Market comprises international construction-equipment manufacturers supported by authorized distributors, dealers, rental companies, and equipment-service providers. Competition is influenced by product breadth, equipment reliability, hydraulic performance, attachment compatibility, financing availability, dealer coverage, spare-parts accessibility, maintenance capabilities, and technology integration. Established OEMs compete across mini excavators, compact loaders, skid-steer loaders, track loaders, wheel loaders, backhoe loaders, and compact rollers, while Chinese manufacturers increasingly participate through competitive equipment offerings. Dealer relationships are particularly important because contractors require equipment demonstrations, parts availability, preventive maintenance, field service, operator support, and financing assistance. Rental companies also influence competitive dynamics by purchasing versatile equipment suitable for multiple applications and project sizes.
| Company | Establishment Year | Headquarters | Mini Excavator Portfolio | Compact Loader Portfolio | Dealer Network | Attachment Compatibility | Telematics Capability | Aftermarket Support |
| Caterpillar Inc. | 1925 | Irving, Texas, USA | ~ | ~ | ~ | ~ | ~ | ~ |
| Komatsu Ltd. | 1921 | Tokyo, Japan | ~ | ~ | ~ | ~ | ~ | ~ |
| Hitachi Construction Machinery | 1949 | Tokyo, Japan | ~ | ~ | ~ | ~ | ~ | ~ |
| JCB | 1945 | Rocester, UK | ~ | ~ | ~ | ~ | ~ | ~ |
| Kubota Corporation | 1890 | Osaka, Japan | ~ | ~ | ~ | ~ | ~ | ~ |
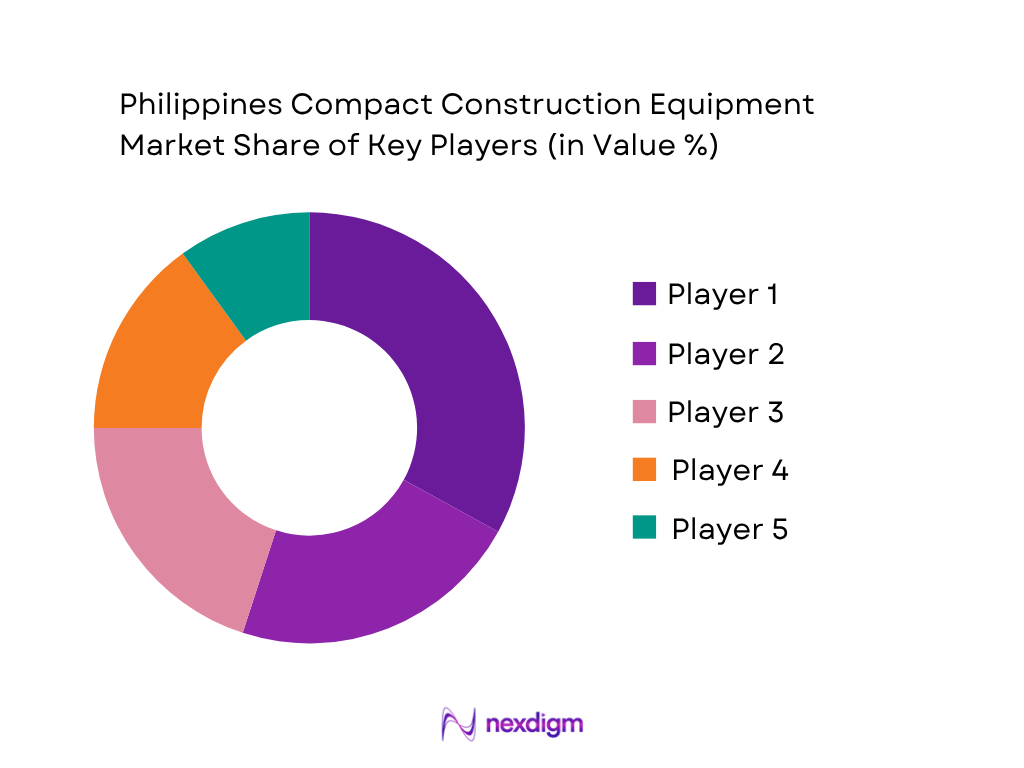
Philippines Compact Construction Equipment Market Analysis
Growth Drivers
Expansion of Construction and Infrastructure Activity
The Philippines Compact Construction Equipment Market is supported by strong construction activity across residential, commercial, infrastructure, utility, and public-sector projects. The Philippine Statistics Authority reported that the total value of construction covered by approved building permits reached PHP 563.89 billion in 2024, compared with PHP 515.30 billion in 2023. The number of approved construction permits also increased from 171,268 to 180,341, while reported construction floor area reached 42.84 million sq. m. Construction was among the country’s fastest-growing major industries, expanding by 10.3 in 2024, while overall Philippine GDP increased by 5.7. These conditions support equipment requirements for excavation, trenching, loading, grading, site preparation, demolition, road works, and material handling. Compact equipment is particularly relevant to projects where contractors require maneuverability around buildings, utilities, roads, and other existing structures. The construction pipeline also creates replacement and fleet-expansion requirements as contractors and rental operators seek equipment capable of serving multiple project categories. Residential construction value reached PHP 248.65 billion, while non-residential construction value reached PHP 250.86 billion, creating demand across several compact-equipment applications.
Urbanization and Increasing Requirement for Compact Machinery
Urbanization is creating market-specific demand for compact construction equipment because infrastructure development increasingly takes place around established communities, transportation corridors, utilities, commercial districts, and residential areas. The 2024 Census of Population recorded 112.73 million people in the Philippines, including 62.22 million residents living in urban barangays. The urban population increased by 3.29 million from 2020, while CALABARZON exceeded a 70 urbanization level, highlighting the concentration of construction activity around major economic corridors. Metro Manila recorded a population of 14.00 million, providing a substantial base for redevelopment, utility maintenance, transport infrastructure, commercial construction, and residential projects. Compact excavators, loaders, and rollers can operate in restricted work zones where transportation access, road width, existing structures, and surrounding activities constrain larger equipment. Construction activity also remains geographically diversified: Central Visayas recorded economic growth of 7.3 in 2024, Central Luzon 6.5, and Davao Region 6.3, compared with national GDP growth of 5.7. This combination of urban population concentration and regional economic expansion supports recurring requirements for maneuverable machinery across excavation, site preparation, utility installation, landscaping, road maintenance, and building construction.
Market Challenges
Dependence on Imported Equipment and Components
The Philippines Compact Construction Equipment Market faces supply-side constraints because a substantial portion of specialized construction machinery, engines, hydraulic components, electronic systems, attachments, and replacement parts is sourced through international manufacturers and distributors. This creates exposure to international logistics conditions, foreign-exchange movements, import lead times, and availability of spare parts. The broader Philippine economy recorded 5.7 GDP growth in 2024, while gross capital formation expanded by 7.7, indicating continued investment activity but also sustained requirements for imported capital equipment. The country’s construction sector expanded by 10.3 in the same period, increasing the importance of timely equipment availability for contractors. Approved building permits reached 180,341 in 2024, compared with 171,268 in 2023, creating a larger operating environment for machinery and aftermarket services. Import dependence can become particularly challenging for contractors operating outside Metro Manila because specialized parts, trained technicians, and equipment support may be concentrated around major commercial centers. Compact equipment also requires model-specific hydraulic, electronic, engine, track, and attachment components, making substitution more difficult when original parts are unavailable. These conditions can influence fleet utilization and maintenance planning across geographically dispersed construction projects.
Financing and Contractor Capital-Expenditure Constraints
Financing conditions can constrain compact construction equipment procurement because contractors must balance machinery investment against project cash flows, utilization levels, and broader construction expenditure. The Philippine economy recorded 5.7 GDP growth in 2024, while household final consumption expenditure increased by 4.9 and gross capital formation increased by 7.7, indicating continued economic and investment activity. At the same time, the construction sector expanded by 10.3, generating equipment requirements across multiple project categories. Approved construction permits increased to 180,341 in 2024 from 171,268 in 2023, but project activity is distributed across residential, commercial, infrastructure, utility, and other construction segments. Residential construction value reached PHP 248.65 billion, while non-residential construction value reached PHP 250.86 billion, illustrating the breadth of capital requirements faced by contractors. Smaller contractors may therefore evaluate purchasing against rental alternatives, particularly when equipment utilization is uncertain between projects. Equipment financing decisions can also be affected by imported-machine exposure, parts availability, maintenance requirements, and the need to match machine capacity with individual project workloads. Consequently, rental fleets and equipment dealers remain important channels for improving access to compact machinery without requiring every contractor to maintain a complete owned fleet.
Market Opportunities
Expansion of Utility, Urban Development and Regional Construction Applications
The Philippines Compact Construction Equipment Market has opportunities to expand through utility installation, urban redevelopment, residential construction, road maintenance, telecommunications infrastructure, drainage, and regional development projects. The country recorded 180,341 approved building permits in 2024, compared with 171,268 in 2023, while construction value increased to PHP 563.89 billion from PHP 515.30 billion. Construction floor area reached 42.84 million sq. m., creating a broad operating base for excavation, loading, grading, compaction, and material-handling equipment. Urban demand is reinforced by 62.22 million people living in urban barangays, while the National Capital Region recorded 14.00 million residents. Regional economic activity also provides opportunities outside the capital: Central Visayas expanded by 7.3, Central Luzon by 6.5, and Davao Region by 6.3 in 2024. These conditions create opportunities for compact machinery designed for narrow work zones, short-duration projects, utility corridors, residential sites, and maintenance activities. Mini excavators, compact loaders, skid-steer loaders, and compact rollers can address multiple requirements through attachment compatibility and transportability, allowing rental operators and contractors to deploy fewer machines across a broader range of projects.
Fleet Modernization and Technology-Enabled Equipment Adoption
Fleet modernization presents an opportunity for the Philippines Compact Construction Equipment Market as contractors and rental operators replace older machinery with equipment offering improved productivity, hydraulic performance, monitoring capabilities, and operating efficiency. The construction sector expanded by 10.3 in 2024, while gross capital formation increased by 7.7, indicating sustained investment activity across the economy. Approved construction activity also increased, with the number of permits reaching 180,341 and total construction value reaching PHP 563.89 billion. The construction industry had 2,512 formal-sector establishments in the latest 2024 Annual Survey of Philippine Business and Industry results, including 1,091 establishments engaged in construction of buildings, 389 in electrical, plumbing and other construction installation activities, and 363 in construction of roads and railways. This diversified contractor base creates opportunities for equipment suppliers to provide machines matched to different operating requirements. Telematics, preventive-maintenance monitoring, attachment systems, operator-assistance technologies, improved hydraulic controls, and alternative powertrain configurations can become increasingly relevant as users focus on equipment utilization and lifecycle management. Rental companies can also support modernization by introducing newer machines into contractor fleets, allowing multiple construction businesses to access updated equipment without maintaining every machine category themselves.
Future Outlook
The Philippines Compact Construction Equipment Market is expected to experience continued development through infrastructure expansion, urban construction, utility modernization, equipment rental activity, and increasing construction mechanization. Demand is likely to remain focused on machines that provide maneuverability, transportability, attachment flexibility, and productivity in confined construction environments. Mini excavators, compact loaders, and compact track loaders are positioned to benefit from diverse applications across infrastructure, residential, commercial, utility, landscaping, and public works projects. Technology adoption is also expected to increase as contractors seek improved fleet utilization, preventive maintenance, equipment monitoring, fuel efficiency, and operator productivity. Electric and lower-emission compact equipment may gradually gain relevance as manufacturers expand alternative powertrain offerings and construction sites place greater emphasis on environmental performance.
Major Players
- Caterpillar Inc.
- Komatsu Ltd.
- Hitachi Construction Machinery
- Kobelco Construction Machinery
- Volvo Construction Equipment
- JCB
- Hyundai Construction Equipment
- SANY Group
- XCMG Group
- Zoomlion Heavy Industry Science & Technology
- LiuGong Machinery
- Kubota Corporation
- Yanmar Compact Equipment
- Takeuchi Manufacturing
- Bobcat Company
Key Target Audience
- Construction Equipment Manufacturers and OEMs
- Construction Equipment Dealers and Distributors
- Equipment Rental and Fleet Management Companies
- Construction Contractors and Infrastructure Developers
- Investments and Venture Capitalist Firms
- Government and Regulatory Bodies (Department of Public Works and Highways, Department of Trade and Industry, Department of Transportation)
- Construction Equipment Financing and Leasing Providers
- Industrial Equipment and Heavy Machinery Importers
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves constructing an ecosystem map covering equipment manufacturers, importers, distributors, dealers, rental companies, contractors, infrastructure developers, and end users within the Philippines Compact Construction Equipment Market. The assessment identifies equipment categories, operating-weight classes, applications, sales channels, and regional demand factors influencing market development.
Step 2: Market Analysis and Construction
This phase involves compiling historical market information covering equipment sales, installed equipment base, replacement demand, rental fleet procurement, application utilization, and distribution activity. Top-down and bottom-up approaches are applied to evaluate equipment demand across construction, infrastructure, utilities, landscaping, agriculture, and public works applications.
Step 3: Hypothesis Validation and Expert Consultation
Market hypotheses are developed and validated through consultations with equipment manufacturers, distributors, dealers, rental companies, contractors, and other industry participants. Discussions focus on equipment utilization, product preferences, application requirements, procurement decisions, aftermarket services, attachment demand, and technology adoption.
Step 4: Research Synthesis and Final Output
The final phase integrates secondary research, industry interviews, company-level information, equipment-category analysis, and demand-side assessments. Data are triangulated across multiple sources to validate market estimates, segmentation structures, competitive positioning, equipment adoption patterns, and the outlook for the Philippines Compact Construction Equipment Market.

- Executive Summary
- Research Methodology (Market Definition and Scope, Philippines Compact Construction Equipment Market Classification, Equipment Category Mapping, Mini Excavator Assessment, Skid-Steer Loader Evaluation, Compact Track Loader Analysis, Compact Wheel Loader Assessment, Compact Backhoe Loader Evaluation, Mini Loader Assessment, Compact Roller Evaluation, Small Articulated Loader Assessment, Operating Weight Classification, Engine Power Assessment, Rated Operating Capacity Analysis, Hydraulic Flow Assessment, Attachment Compatibility Assessment, Equipment Productivity Analysis, Rental Fleet Assessment, Equipment Utilization Analysis, Dealer Network Mapping, Aftermarket and Service Assessment, Domestic Assembly Assessment, Import Dependency Assessment, Supply-Side Assessment, Demand-Side Assessment, Top-Down Market Sizing, Bottom-Up Market Sizing, Primary Industry Interviews, Data Triangulation, Forecasting Framework)

- Definition and Scope
- Philippines Compact Construction Equipment Industry Evolution and Development of Mini Excavators, Skid-Steer Loaders, Compact Track Loaders, Compact Wheel Loaders, Compact Backhoe Loaders, Mini Loaders, Compact Rollers, Small Articulated Loaders, Zero-Tail-Swing Excavators, High-Flow Hydraulic Equipment, Attachment-Based Compact Machines, Telematics-Enabled Equipment, Operator-Assistance Technologies, Battery-Electric Compact Equipment, Advanced Compact Construction Equipment Technologies
- Compact Construction Equipment Value Chain Analysis
- Compact Construction Equipment Supply Chain Analysis
- Engine and Powertrain Suppliers, Hydraulic Component Manufacturers, Track and Tire Suppliers, Steel and Structural Component Suppliers, Battery and Electric Powertrain Suppliers, Attachment Manufacturers, Compact Construction Equipment OEMs, Equipment Importers, Authorized Equipment Dealers, Independent Equipment Dealers, Equipment Rental Companies, Equipment Financing Providers, Used Equipment Dealers, Auction Platforms, General Contractors, Specialty Contractors, Infrastructure Contractors, Utility Contractors, Landscaping Contractors, Agricultural Contractors, Local Government Units, Industrial End Users

- Growth Drivers (Infrastructure Development, Road and Highway Construction, Urban Construction Activity, Utility and Telecommunications Expansion, Residential Development, Equipment Rental Expansion, Mechanization of Construction Activities, Increasing Demand for Maneuverable Equipment)
- Market Challenges (High Equipment Import Dependence, Equipment Financing Constraints, Foreign Exchange Exposure, Limited Local Manufacturing Capacity, Skilled Operator Shortages, Aftermarket Parts Availability, Dealer Service Coverage Gaps, Used Equipment Competition, Tropical Operating Conditions)
- Market Opportunities (Infrastructure Modernization, Metro Manila and Urban Utility Projects, Road Rehabilitation, Telecommunications and Fiber Deployment, Flood-Control and Drainage Projects, Rental Fleet Expansion, Compact Equipment Attachments, Electric Compact Equipment, Telematics and Fleet Management, Agricultural Mechanization)
- Market Trends (Mini Excavator Adoption, Attachment-Based Equipment Utilization, Compact Track Loader Adoption, Rental-Oriented Procurement, Telematics Integration, Fuel-Efficient Equipment, Electric Compact Machinery, Zero-Tail-Swing Equipment, Remote Monitoring, Preventive Maintenance, Operator-Assistance Systems)
- Government Regulations and Standards (Department of Public Works and Highways Equipment Requirements, Occupational Safety and Health Standards, Philippine National Standards for Construction Equipment, Environmental Compliance Requirements, Emission Standards for Mobile Sources, Department of Transportation Infrastructure Requirements, Local Government Construction Requirements, Equipment Safety and Operator Certification Requirements)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Competition Ecosystem

- By Market Value (2020-2025)
- By New Equipment Unit Sales (2020-2025)
- By Installed Equipment Base (2020-2025)
- By Average Selling Price per Equipment Unit (2020-2025)
- By Mini Excavator Unit Sales (2020-2025)
- By Skid-Steer Loader Unit Sales (2020-2025)
- By Compact Track Loader Unit Sales (2020-2025)
- By Compact Wheel Loader Unit Sales (2020-2025)
- By Compact Backhoe Loader Unit Sales (2020-2025)
- By Rental Fleet Equipment Purchases (2020-2025)

- By Equipment Type (In Value %)
Mini Excavators
Skid-Steer Loaders
Compact Track Loaders
Compact Wheel Loaders
Compact Backhoe Loaders
Mini Loaders
Compact Rollers
Small Articulated Loaders - By Application (In Value %)
Excavation and Trenching
Loading and Material Handling
Grading and Site Preparation
Lifting and Placement
Demolition
Landscaping and Grounds Development
Compaction
Road Construction and Maintenance
Utility Installation and Maintenance
Agricultural and Land Development - By End-Use Industry (In Value %)
Residential Construction
Commercial Construction
Infrastructure and Civil Construction
Road and Highway Construction
Utility and Telecommunications Construction
Industrial Construction
Mining and Quarrying
Agriculture and Land Development
Landscaping and Grounds Maintenance
Government and Public Works
Equipment Rental - By Sales Channel (In Value %)
OEM-Authorized Dealers
Independent Equipment Dealers
Direct and Fleet Sales
Equipment Rental Companies
Used Equipment Dealers
Equipment Auctions
Digital Equipment Marketplaces - By Operating Weight (In Value %)
Below 1.5 Tons
1.5–3 Tons
3–5 Tons
5–7 Tons
Above 7 Tons - By Region (In Value %)
National Capital Region
Central Luzon
CALABARZON
Central Visayas
Western Visayas
Northern Mindanao
Davao Region
Ilocos Region
Cagayan Valley
Rest of Philippines

- Market Share of Major Players (By Philippines Revenue, Compact Equipment Unit Sales, Mini Excavator Portfolio, Skid-Steer Loader Portfolio, Compact Track Loader Portfolio, Manufacturing and Import Capacity, Dealer Network Coverage, Rental Fleet Presence, Attachment Portfolio, Telematics Capability, Electric Equipment Capability, Aftermarket Support, Installed Equipment Base)
- Cross Comparison Parameters (Rated Operating Capacity and Lift Performance, Auxiliary Hydraulic Flow and Attachment Compatibility, Equipment Operating Weight Range, Maximum Digging Depth, Compact Equipment Portfolio Breadth, Telematics and Fleet Management Capability, Dealer and Service Network Coverage, Aftermarket Parts and Lifecycle Support)
- SWOT Analysis of Major Players
- Competitive Positioning Matrix
- Compact Construction Equipment Technology and Application Benchmarking
- Hydraulic System and Attachment Compatibility Assessment
- Equipment Productivity and Operational Performance Assessment
- Equipment Rental and Fleet Utilization Assessment
- Philippines Equipment Import, Dealer and Distribution Assessment
- Major Companies
Caterpillar Inc.
Komatsu Ltd.
Hitachi Construction Machinery Co., Ltd.
Kobelco Construction Machinery Co., Ltd.
Volvo Construction Equipment
JCB
Hyundai Construction Equipment
SANY Group
XCMG Group
Zoomlion Heavy Industry Science & Technology Co., Ltd.
LiuGong Machinery
Kubota Corporation
Yanmar Compact Equipment
Takeuchi Manufacturing
Bobcat Company

- General Contractor Equipment Requirement Assessment
- Specialty Contractor Equipment Demand Analysis
- Residential Construction Equipment Requirement Assessment
- Infrastructure Contractor Application Assessment
- Road Construction Equipment Requirement Assessment
- Utility and Telecommunications Contractor Assessment
- Landscaping Contractor Application Assessment
- Rental Fleet Procurement Assessment
- Local Government Unit Equipment Assessment
- Agricultural Contractor Equipment Assessment
- Equipment Performance Requirement Assessment (Operating Weight, Rated Operating Capacity, Digging Depth, Breakout Force, Auxiliary Hydraulic Flow, Lift Height, Transportability, Fuel Efficiency)

- By Market Value (2026-2035)
- By New Equipment Unit Sales (2026-2035)
- By Installed Equipment Base (2026-2035)
- By Average Selling Price per Equipment Unit (2026-2035)
- By Mini Excavator Unit Sales (2026-2035)
- By Skid-Steer Loader Unit Sales (2026-2035)
- By Compact Track Loader Unit Sales (2026-2035)
- By Compact Wheel Loader Unit Sales (2026-2035)
- By Electric Compact Equipment Unit Sales (2026-2035)
- By Rental Fleet Equipment Purchases (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
