
 Download PDF
Market Overview
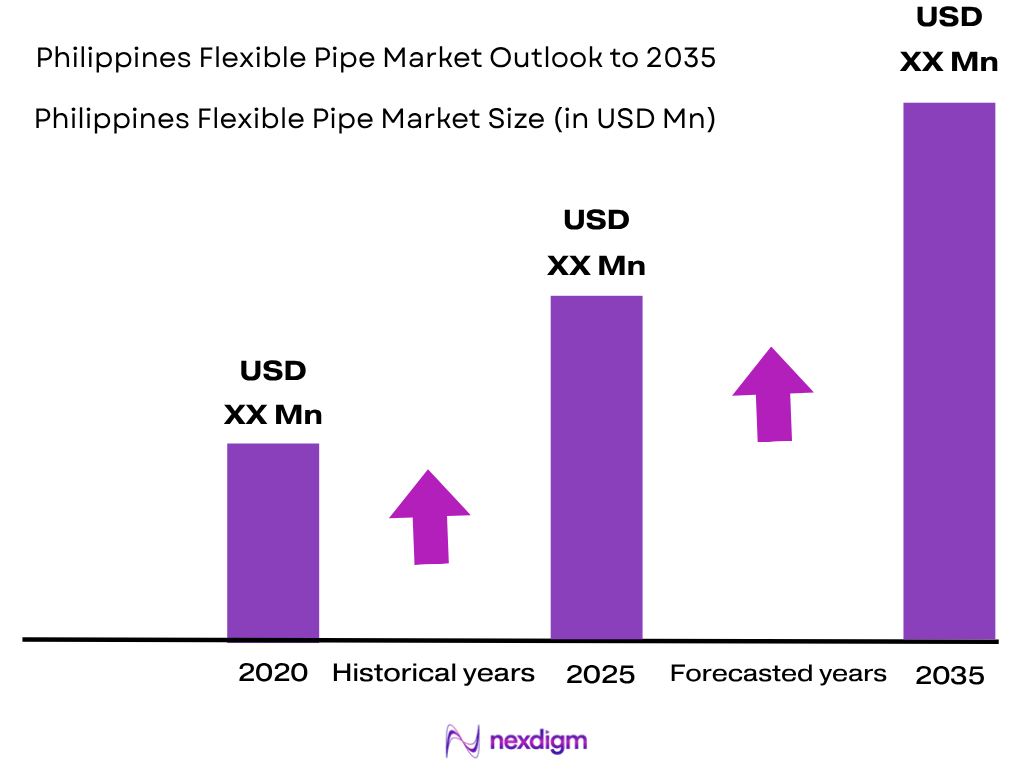
The Philippines Flexible Pipe Market is valued at ~USD XX million based on industry demand from offshore oil and gas operations, marine infrastructure, and industrial fluid transportation applications. The market is driven by requirements for corrosion-resistant and lightweight pipeline solutions, particularly for offshore production systems, subsea connections, and aging infrastructure replacement. Flexible pipes are increasingly used where conventional rigid pipelines face installation limitations due to seabed complexity, vessel movement, and harsh marine operating environments.
The Philippines flexible pipe ecosystem is concentrated around major industrial and maritime hubs including Metro Manila, Batangas, Subic Bay, Cebu, and Palawan due to their proximity to energy infrastructure, shipyards, ports, and offshore activities. Batangas and Palawan are important due to oil and gas operations, while Subic and Cebu support marine engineering and shipbuilding activities. The country’s extensive coastline and dependence on maritime transportation create demand for flexible pipeline systems across offshore, marine, and industrial applications.
Market Segmentation
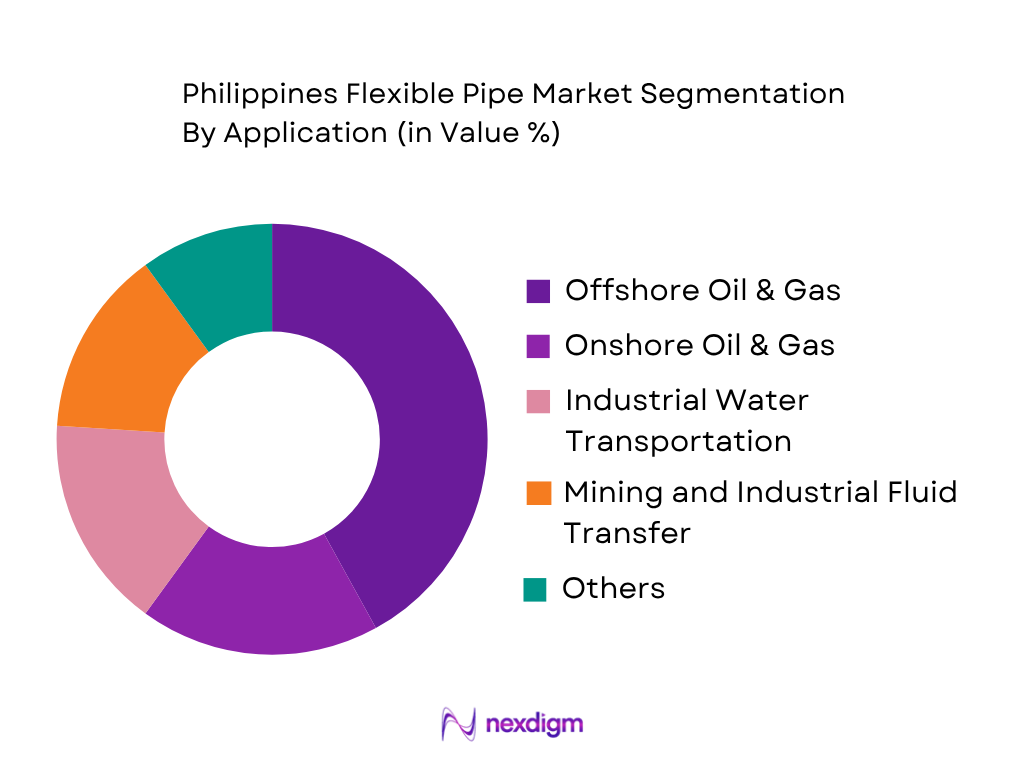
By Application Type
The Philippines Flexible Pipe Market is segmented by application type into offshore oil and gas, onshore oil and gas, industrial water transportation, mining and industrial fluid transfer, and renewable energy infrastructure. Offshore oil and gas represents the dominant application segment due to the country’s offshore energy exploration activities and requirement for flexible risers, flowlines, and subsea connection systems. Flexible pipes are preferred in offshore applications because they accommodate dynamic movement, reduce installation complexity, and provide corrosion resistance in marine environments. The presence of offshore assets such as the Malampaya gas infrastructure and increasing focus on domestic energy security supports demand for advanced pipeline solutions. Marine engineering capabilities around Batangas and Palawan further support offshore pipeline maintenance and deployment activities.
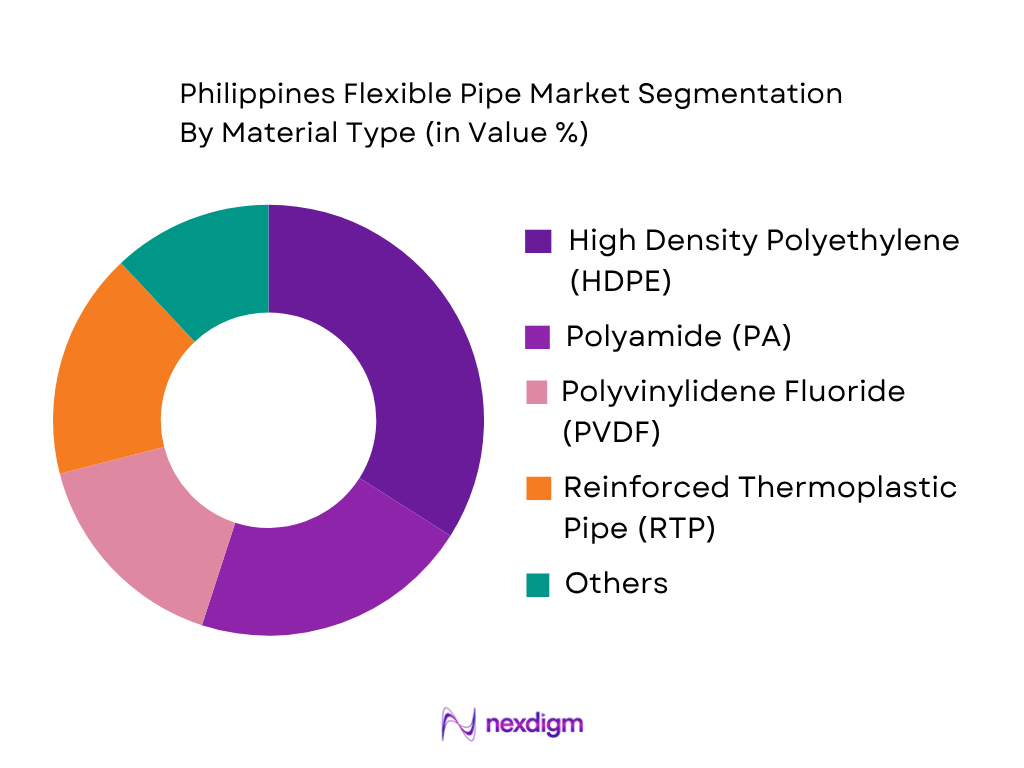
By Material Type
The Philippines Flexible Pipe Market is segmented by material type into HDPE, PA, PVDF, reinforced thermoplastic pipe, and composite flexible pipe. HDPE holds the leading position due to its corrosion resistance, lightweight structure, and suitability for industrial water transportation and low-to-medium pressure applications. The material is widely used because of its durability in marine environments and compatibility with various fluid transfer systems. Reinforced thermoplastic pipes and composite flexible pipes are gaining adoption in offshore and high-performance applications due to their improved pressure handling capability and resistance against aggressive operating conditions. Advanced materials such as PA and PVDF are increasingly relevant for offshore applications requiring chemical resistance, temperature stability, and long operational life.
Competitive Landscape
The Philippines Flexible Pipe Market is characterized by the presence of international technology providers and offshore engineering companies supplying advanced flexible pipeline solutions. The market remains dependent on global manufacturers due to limited domestic production capabilities for high-performance flexible pipes. Companies compete based on offshore qualification capabilities, subsea technology expertise, composite material development, engineering support, and regional supply chain networks.
| Company | Establishment Year | Headquarters | Flexible Pipe Portfolio | Offshore Capability | Material Technology | Key Application | Regional Presence | Engineering Support |
| TechnipFMC | 2017 | United Kingdom | ~ | ~ | ~ | ~ | ~ | ~ |
| Baker Hughes | 2017 | United States | ~ | ~ | ~ | ~ | ~ | ~ |
| NOV | 1862 | United States | ~ | ~ | ~ | ~ | ~ | ~ |
| Aker Solutions | 2020 | Norway | ~ | ~ | ~ | ~ | ~ | ~ |
| Magma Global | 2003 | United Kingdom | ~ | ~ | ~ | ~ | ~ | ~ |
Philippines Flexible Pipe Market Analysis
Growth Drivers
Expansion of Offshore Oil and Gas Activities
The expansion of offshore oil and gas activities in the Philippines is supporting demand for flexible pipe systems used in subsea flowlines, risers, and offshore production infrastructure. The country’s energy strategy continues to emphasize domestic hydrocarbon exploration to reduce dependence on imported energy. The Department of Energy reported that the Philippines recorded total oil production of approximately 5.8 million barrels and natural gas production of around 100 billion cubic feet in recent years, highlighting continued reliance on offshore assets such as the Malampaya gas field. The Malampaya offshore gas facility, located approximately 80 kilometers northwest of Palawan, remains a critical component of the country’s electricity supply infrastructure. Flexible pipes are increasingly relevant for offshore operations because they provide corrosion resistance, dynamic movement capability, and easier installation in complex marine environments. The Philippine Statistics Authority reported that the country’s economy generated PHP 24.32 trillion in gross domestic product at current prices, reflecting continued industrial activity requiring reliable energy infrastructure. Additionally, the World Bank reported that the Philippines’ population exceeded 115 million, increasing long-term electricity demand and supporting investments in offshore energy systems. These factors contribute to the requirement for advanced flexible pipeline technologies for offshore exploration, maintenance, and production applications.
Increasing Marine Infrastructure Development
The Philippines’ extensive maritime geography and expanding marine infrastructure sector are creating demand for flexible pipe solutions across offshore engineering, ports, shipyards, and industrial fluid transportation applications. The country consists of more than 7,600 islands, creating significant requirements for marine-based infrastructure development and subsea connectivity solutions. The Philippine Ports Authority reported handling more than 250 million metric tons of cargo volume annually, reflecting continuous maritime activity that requires improved offshore and coastal infrastructure. Flexible pipes support marine applications by offering resistance against corrosion, reduced installation complexity, and adaptability to underwater conditions. The Philippine shipbuilding industry, supported by facilities in Subic Bay, Batangas, and Cebu, continues to contribute to offshore engineering capabilities and marine equipment requirements. According to government economic data, the Philippines recorded infrastructure spending exceeding PHP 1 trillion, supporting transportation, industrial, and maritime development projects. Increasing investments in ports, coastal facilities, and marine energy systems are expected to strengthen demand for flexible pipeline technologies. These systems are particularly suitable for applications requiring rapid deployment, reduced maintenance requirements, and improved operational reliability in offshore and coastal environments.
Market Challenges
High Dependence on Imported Flexible Pipe Technologies
The Philippines Flexible Pipe Market faces challenges due to limited domestic manufacturing capabilities for advanced offshore-grade flexible pipe systems, resulting in dependence on international suppliers. High-performance flexible pipes require specialized manufacturing technologies involving multiple polymer layers, reinforcement structures, and advanced testing procedures that are currently concentrated among global technology providers. The Philippine Statistics Authority reported that the country imported machinery and industrial equipment worth billions of US dollars, reflecting continued dependence on imported industrial technologies. Offshore operators generally rely on qualified international suppliers because flexible risers and flowlines require compliance with strict offshore engineering standards. The country’s manufacturing sector contributes significantly to economic activity, with the Philippine Statistics Authority reporting manufacturing output exceeding PHP 4 trillion in recent economic assessments; however, production capabilities remain concentrated in conventional industrial products rather than advanced subsea pipeline systems. Limited local production capacity increases procurement lead times and creates dependency on foreign technology providers for offshore projects. Developing domestic assembly, testing, and maintenance capabilities remains a challenge for expanding flexible pipe adoption across offshore energy and industrial applications.
Complex Offshore Qualification Requirements
Flexible pipe deployment in Philippine offshore environments is affected by strict qualification requirements related to pressure resistance, temperature conditions, fatigue performance, and marine durability. Offshore pipeline systems must undergo extensive engineering validation because failures can result in operational disruptions and environmental risks. The Philippines operates offshore energy infrastructure in marine environments characterized by deep waters, seismic activity, and challenging weather conditions. The Philippine Institute of Volcanology and Seismology identifies the country as one of the world’s most active seismic regions, creating additional engineering considerations for offshore infrastructure development. Flexible pipes require advanced testing for dynamic loading, chemical resistance, and long-term performance before installation. The Department of Energy continues to emphasize safety standards for upstream energy operations, requiring operators to comply with technical and environmental regulations. The World Bank reported that the Philippines remains highly exposed to climate-related risks, increasing the importance of resilient infrastructure systems. These factors increase project complexity and require specialized engineering expertise, offshore qualification processes, and imported technical support for flexible pipe installation and maintenance activities.
Market Opportunities
Offshore Gas Field Development
Offshore gas field development presents opportunities for flexible pipe adoption as the Philippines continues efforts to strengthen domestic energy security. The Malampaya gas field remains a key offshore energy asset, with continued maintenance and extension activities requiring reliable subsea infrastructure solutions. The Department of Energy has identified natural gas as an important transition fuel supporting electricity generation while renewable energy capacity expands. The Philippines recorded natural gas production of approximately 100 billion cubic feet annually, demonstrating the continued importance of offshore gas infrastructure. Flexible pipes provide advantages in offshore gas applications due to their ability to handle dynamic conditions, reduce installation challenges, and withstand marine corrosion. The country’s electricity demand continues to rise alongside economic expansion, with the World Bank reporting Philippine GDP growth supported by industrial activity and infrastructure development. Future offshore exploration activities in areas such as the West Philippine Sea and other offshore basins may create additional requirements for subsea pipeline systems. These developments provide opportunities for flexible pipe suppliers, offshore engineering companies, and local service providers to participate in future energy infrastructure projects.
LNG Terminal Infrastructure Expansion
Expansion of LNG infrastructure creates opportunities for flexible pipe applications in gas transportation, marine terminals, and offshore energy facilities. The Philippines has been developing LNG import infrastructure to support energy security following declining domestic gas availability from existing offshore resources. The Department of Energy has approved multiple LNG-related projects aimed at improving gas supply reliability for power generation facilities. The country’s electricity consumption continues increasing, with the International Energy Agency reporting rising electricity demand across Southeast Asian economies, including the Philippines. Flexible pipes can support LNG-related marine applications including offshore connections, floating storage and regasification units, and associated fluid transfer systems. The Philippines recorded foreign direct investment inflows of more than USD 8 billion according to economic authorities, supporting continued infrastructure investment across energy sectors. LNG infrastructure development requires specialized marine pipeline systems capable of operating under demanding offshore conditions. Increasing investment in gas import terminals, floating LNG solutions, and marine energy infrastructure provides growth opportunities for flexible pipe technologies and associated engineering services within the Philippine energy sector.
Future Outlook
Over the next decade, the Philippines Flexible Pipe Market is expected to experience increasing adoption driven by offshore energy development, marine infrastructure modernization, and demand for corrosion-resistant pipeline systems. Growth in LNG infrastructure, industrial water transportation, and renewable energy applications will create additional opportunities for flexible pipe technologies. The market will increasingly focus on advanced composite materials, reinforced thermoplastic pipes, and locally supported engineering capabilities to reduce dependence on imported solutions.
Major Players
- TechnipFMC
- Baker Hughes
- NOV
- Aker Solutions
- Magma Global
- Prysmian Group
- Nexans
- Shawcor
- Airborne Oil & Gas
- Subsea 7
- Saipem
- McDermott International
- Trelleborg
- ContiTech
- Pipelife
Key Target Audience
- Offshore Oil and Gas Operators
- LNG Infrastructure Developers
- Marine Engineering and Shipbuilding Companies
- EPC Contractors and Offshore Installation Companies
- Industrial Water Infrastructure Operators
- Mining and Mineral Processing Companies
- Investments and Venture Capitalist Firms (Energy Infrastructure Investment Funds, Industrial Technology Investment Firms)
- Government and Regulatory Bodies (Department of Energy Philippines, Maritime Industry Authority, Philippine Ports Authority)
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves developing a comprehensive ecosystem map covering offshore operators, pipeline technology providers, marine engineering companies, EPC contractors, and industrial users. Secondary research is conducted to identify market drivers, application requirements, technology developments, and supply chain structures influencing the Philippines Flexible Pipe Market.
Step 2: Market Analysis and Construction
Historical market information is analysed through application-based demand assessment, material technology evaluation, import dependency analysis, and industry infrastructure mapping. The study evaluates offshore projects, industrial applications, pipeline replacement requirements, and technology adoption patterns to construct market estimates.
Step 3: Hypothesis Validation and Expert Consultation
Market assumptions are validated through discussions with industry participants including offshore engineering companies, pipeline suppliers, and industrial users. These consultations provide insights into procurement behaviour, technology preferences, operational challenges, and future infrastructure requirements.
Step 4: Research Synthesis and Final Output
The final stage combines primary and secondary research findings to validate market intelligence. Data from supply-side assessment, demand-side analysis, and industry interviews are integrated to provide a comprehensive view of market opportunities, competitive positioning, and future development trends.

- Executive Summary
- Research Methodology (Market Definitions and Assumptions, Flexible Pipe Market Classification, Offshore and Subsea Pipeline Demand Assessment, Oil and Gas Infrastructure Assessment, Marine and Shipyard Application Mapping, Industrial Fluid Transfer Assessment, Material Technology Assessment, Reinforced Thermoplastic Pipe Evaluation, Composite Flexible Pipe Technology Assessment, Demand-Side Analysis, Supply-Side Analysis, Primary Industry Interviews, Data Triangulation, Forecasting Framework, Market Limitation Assessment)

- Definition and Scope
- Philippines Flexible Pipe Industry Evolution
- Flexible Pipe Technology Evolution
- Philippines Flexible Pipe Value Chain Analysis
- Philippines Flexible Pipe Supply Chain Analysis

- Growth Drivers (Expansion of Offshore Oil and Gas Activities, Malampaya Gas Field Maintenance Requirements, Increasing Marine Infrastructure Development, Growth of LNG Infrastructure, Rising Offshore Engineering Activities, Aging Pipeline Replacement Requirements, Industrial Water Infrastructure Expansion, Demand for Lightweight Corrosion Resistant Pipeline Systems)
- Market Challenges (High Dependence on Imported Flexible Pipe Technologies, Limited Domestic Manufacturing Capability, Complex Offshore Qualification Requirements, High Installation Costs, Dependence on Advanced Polymer Materials, Competition from Steel Pipeline Systems, Limited Local Testing and Certification Infrastructure, Technical Challenges in High Pressure Offshore Applications)
- Market Opportunities (Offshore Gas Field Development, LNG Terminal Infrastructure Expansion, Reinforced Thermoplastic Pipe Adoption, Marine Pipeline Rehabilitation Projects, Offshore Renewable Energy Infrastructure, Hydrogen Transportation Infrastructure, Carbon Capture and Storage Infrastructure, Domestic Flexible Pipe Assembly and Service Capability Development)
- Market Trends (Increasing Use of Composite Flexible Pipes, Offshore Asset Life Extension Programs, Digital Pipeline Monitoring Adoption, Advanced Polymer Material Development, Corrosion Resistant Pipeline Solutions, Modular Offshore Infrastructure, Flexible Pipe Application in LNG Systems, Regional Offshore Engineering Partnerships)
- Government Regulations and Standards (Department of Energy Philippines Offshore Energy Regulations, Philippine National Standards for Industrial Equipment, Environmental Compliance Certificate Requirements, Maritime Industry Authority Regulations, Philippine Ports Authority Infrastructure Standards, Occupational Safety and Health Requirements, Offshore Environmental Protection Regulations)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Competition Ecosystem

- By Market Value
- By Flexible Pipe Consumption Volume
- By Offshore Oil and Gas Flexible Pipe Consumption Volume
- By Marine and Shipyard Flexible Pipe Consumption Volume
- By Industrial Fluid Transfer Flexible Pipe Consumption Volume

- By Application Type (In Value %)
Offshore Oil and Gas Production
Subsea Flowlines
Dynamic Risers
Static Risers
Well Jumpers
Onshore Oil and Gas Transportation
Refinery and Petrochemical Fluid Transfer
Marine and Shipyard Applications
FPSO and Floating Production Support
Industrial Water Transportation - By Material Type (In Value %)
High Density Polyethylene (HDPE)
Polyamide (PA)
Polyvinylidene Fluoride (PVDF)
Reinforced Thermoplastic Pipe (RTP)
Composite Flexible Pipe
Steel Reinforced Flexible Pipe
Fiber Reinforced Composite Pipe - By Product Configuration (In Value %)
Unbonded Flexible Pipes
Bonded Flexible Pipes
Thermoplastic Composite Pipes
Reinforced Hose Systems
Flexible Risers
Flexible Jumpers - By Pressure Rating (In Value %)
Low Pressure Flexible Pipes
Medium Pressure Flexible Pipes
High Pressure Flexible Pipes
High Pressure High Temperature (HPHT) Flexible Pipes
Ultra High Pressure Offshore Flexible Pipes - By End-Use Industry (In Value %)
Oil and Gas Exploration and Production
LNG and Energy Infrastructure
Marine and Shipbuilding
Petrochemical Processing
Industrial Manufacturing
Mining and Mineral Processing
Water and Wastewater Infrastructure
Renewable Energy Infrastructure - By Region (In Value %)
National Capital Region
Central Luzon
Calabarzon
Visayas
Cebu Marine Industrial Cluster
Mindanao

- Market Share of Major Players (By Revenue, Flexible Pipe Sales Volume, Offshore Application Exposure, Material Technology, End-Use Industry Coverage, Regional Supply Capability)
- Cross Comparison Parameters (Flexible Pipe Product Portfolio Breadth, Offshore Riser and Flowline Capability, Reinforced Thermoplastic Pipe Technology Capability, Composite Material Engineering Expertise, Southeast Asian Supply Chain Reach, Offshore Installation and Engineering Support Capability, High Pressure High Temperature Application Capability, Marine and Industrial Customer Base)
- SWOT Analysis of Major Players
- Detailed Profiles of Major Companies
TechnipFMC
Nexans
NOV
Prysmian Group
Magma Global
Shawcor
Airborne Oil & Gas
Baker Hughes
Subsea 7
Saipem
McDermott International
Aker Solutions
Pipelife
ContiTech
Trelleborg

- Offshore Oil and Gas Operator Pipeline Requirement Assessment
- Malampaya Gas Infrastructure Flexible Pipe Demand Analysis
- LNG Import Terminal Flexible Pipe Requirement Assessment
- Marine Shipyard Flexible Pipeline Application Analysis
- EPC Contractor Flexible Pipe Procurement Assessment
- Industrial Manufacturing Fluid Transfer Requirement Analysis
- Mining Industry Slurry Pipeline Requirement Assessment
- Water Infrastructure Operator Pipeline Modernization Assessment
- Renewable Energy Developer Flexible Cable Protection Requirement Assessment

- By Market Value (2026-2035)
- By Flexible Pipe Consumption Volume (2026-2035)
- By Offshore Oil and Gas Flexible Pipe Consumption Volume (2026-2035)
- By Marine and Shipyard Flexible Pipe Consumption Volume (2026-2035)
- By Industrial Fluid Transfer Flexible Pipe Consumption Volume (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
