
 Download PDF
Market Overview
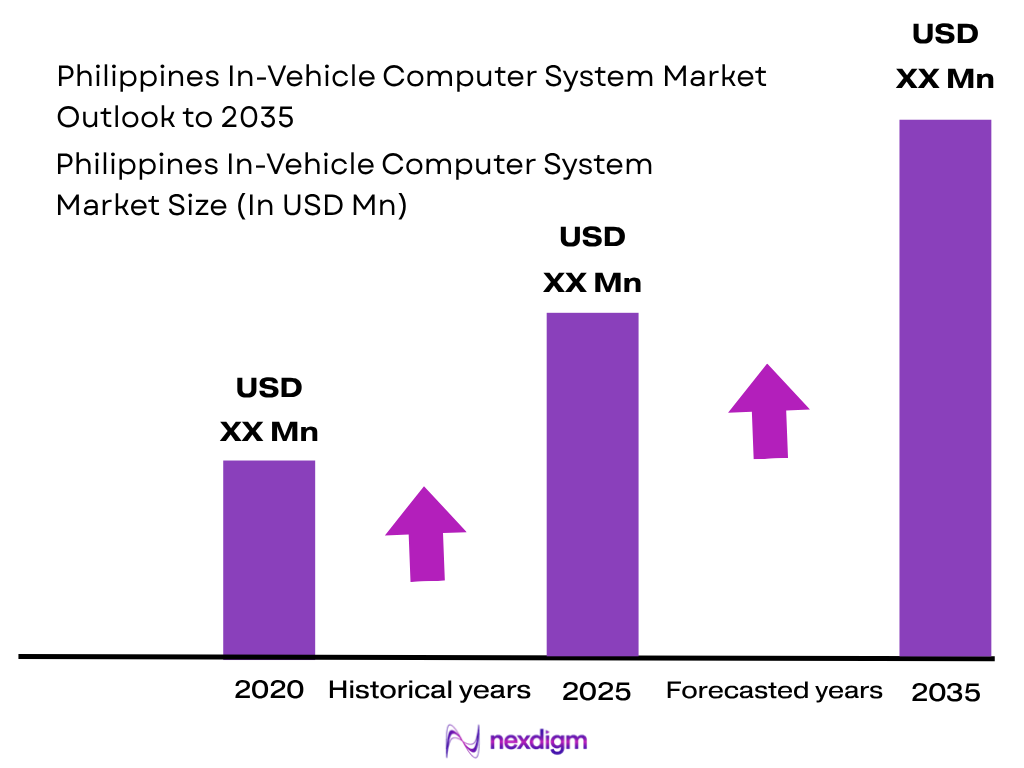
The Philippines In-Vehicle Computer System Market is valued at USD ~0.X billion in 2024 and is expected to expand at a CAGR of ~XX% during 2026-2035. The market growth is supported by increasing vehicle connectivity adoption, rising integration of digital cockpit solutions, telematics platforms, infotainment computing systems, and advanced driver assistance system (ADAS) technologies. The Philippines automotive sector recorded 467,369 vehicle sales in 2024, reflecting increasing demand for vehicles equipped with advanced electronic systems. The country had 14.56 million registered vehicles in 2024, creating a broad installed base for connected vehicle computing technologies.
The Philippines In-Vehicle Computer System Market is primarily concentrated in Metro Manila, Cebu, and Davao due to higher vehicle ownership, urban mobility requirements, automotive dealership presence, and technology infrastructure development. Metro Manila dominates due to its concentration of premium vehicles, fleet operators, transportation companies, and smart mobility initiatives. Cebu and Davao are emerging automotive technology hubs due to economic expansion and increasing adoption of connected transportation solutions. The Philippines connected mobility ecosystem is supported by increasing EV adoption, with registered electric vehicles increasing from 1,359 units in 2023 to 6,697 units in 2024, encouraging demand for advanced vehicle computing platforms.
Market Segmentation
By System Type
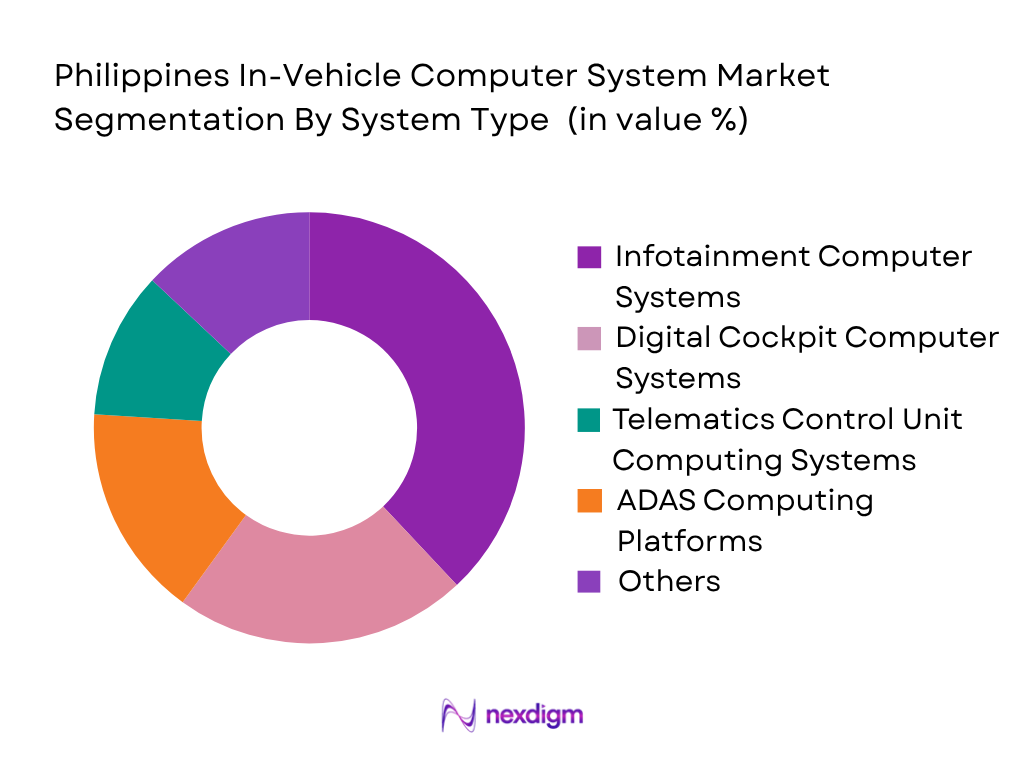
The Philippines In-Vehicle Computer System Market is segmented by system type into infotainment computer systems, digital cockpit computer systems, telematics control units, ADAS computing platforms, vehicle gateway computers, and centralized vehicle computing systems. Infotainment computer systems represent the dominant segment due to widespread consumer preference for connected entertainment, navigation, smartphone integration, voice assistance, and digital display systems. Automotive manufacturers increasingly integrate infotainment computing platforms as standard features across passenger vehicles to improve user experience and vehicle connectivity. The growth of connected car technologies, IoT-based vehicle applications, and cloud-linked automotive services is increasing demand for higher-performance infotainment processors. The expanding adoption of digital dashboards and connected features in imported vehicles is further supporting this segment in the Philippines automotive market.
By Vehicle Type
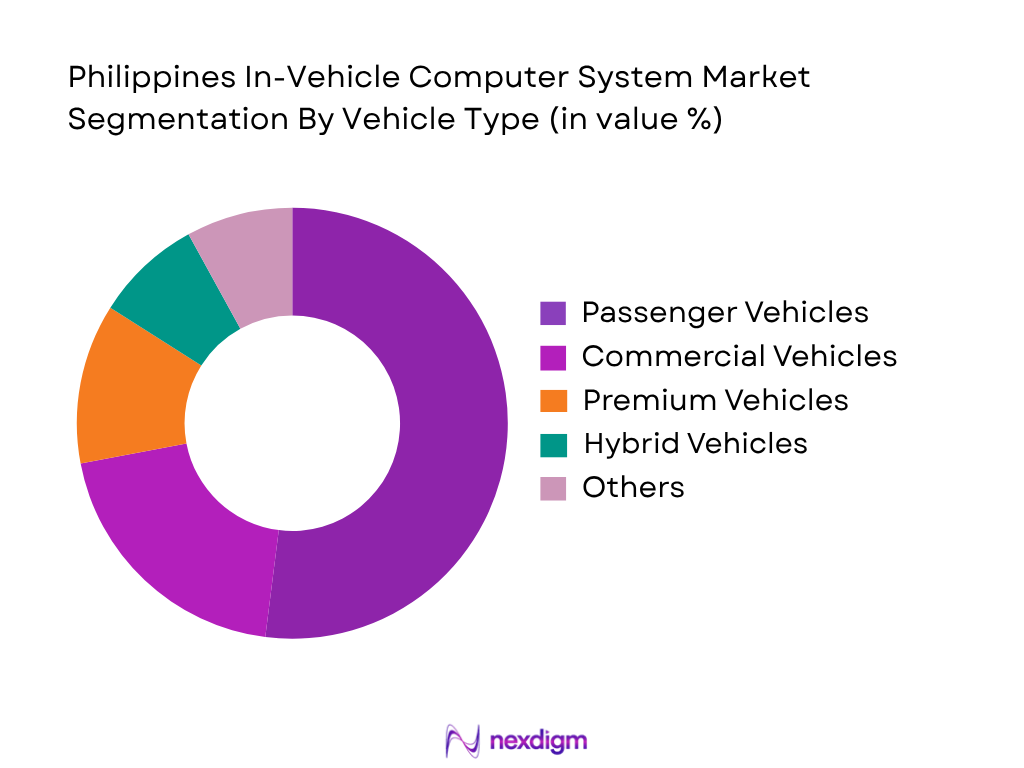
The Philippines In-Vehicle Computer System Market is segmented by vehicle type into passenger cars, premium vehicles, electric vehicles, hybrid vehicles, commercial vehicles, public utility vehicles, and fleet vehicles. Passenger vehicles dominate the market due to higher vehicle sales volumes, increasing consumer demand for advanced automotive features, and growing availability of connected vehicle models. Passenger vehicles accounted for the majority of Philippine automotive sales, with passenger cars representing approximately 88% of industry sales in 2024 according to automotive industry data. The increasing adoption of SUVs, MPVs, and premium vehicles is supporting demand for digital cockpit systems, navigation platforms, and integrated computing solutions. Electric and hybrid vehicles are also becoming important growth segments as they require advanced computing systems for battery management, connectivity, and vehicle control functions.
Competitive Landscape
The Philippines In-Vehicle Computer System Market includes global automotive electronics suppliers, semiconductor companies, vehicle technology providers, and automotive manufacturers. Companies such as Bosch, Continental, Harman, Denso, Qualcomm, LG Electronics, and Panasonic compete through digital cockpit systems, vehicle computing platforms, connectivity solutions, and ADAS technologies. The market is influenced by increasing partnerships between automotive OEMs and technology providers to integrate connected vehicle platforms, centralized computing architectures, and software-based automotive solutions. Japanese automotive manufacturers continue to maintain a strong presence in the Philippines automotive sector, while global technology companies are expanding their automotive electronics capabilities.
| Company | Establishment Year | Headquarters | Major Product Portfolio | Vehicle Computing Capability | Connectivity Technology | ADAS Technology Focus | OEM Integration Capability | Software Platform Capability |
| Bosch Mobility | 1886 | Germany | ~ | ~ | ~ | ~ | ~ | ~ |
| Continental AG | 1871 | Germany | ~ | ~ | ~ | ~ | ~ | ~ |
| Harman International | 1980 | USA | ~ | ~ | ~ | ~ | ~ | ~ |
| Denso Corporation | 1949 | Japan | ~ | ~ | ~ | ~ | ~ | ~ |
| Qualcomm Technologies | 1985 | USA | ~ | ~ | ~ | ~ | ~ | ~ |
Philippines In-Vehicle Computer System Market Analysis
Growth Drivers
Increasing Vehicle Connectivity and Digital Transportation Infrastructure Development
The Philippines In-Vehicle Computer System Market is supported by the rapid expansion of digital connectivity infrastructure, increasing vehicle electrification initiatives, and growing integration of connected automotive technologies. The country’s expanding digital ecosystem is enabling higher adoption of infotainment computing systems, telematics control units, navigation platforms, and cloud-connected vehicle solutions. According to the World Bank, the Philippines recorded a population of approximately 115.8 million people in 2024, creating a large transportation demand base supporting connected mobility solutions. The country’s gross domestic product reached approximately USD 461 billion in 2024, reflecting continued economic activity supporting automotive technology investments. The International Telecommunication Union reported that internet usage in the Philippines exceeded 85 million users in 2024, strengthening the foundation for connected vehicle applications that rely on mobile networks, cloud platforms, and real-time data exchange. Increasing adoption of smartphones, digital services, and online mobility platforms is encouraging automotive manufacturers to integrate advanced in-vehicle computing systems. These systems enable navigation, vehicle diagnostics, entertainment, driver assistance, and connectivity functions, making them essential components of next-generation vehicles. The expansion of urban mobility requirements in Metro Manila, Cebu, and Davao is further increasing demand for intelligent transportation technologies.
Expansion of Electric Vehicle Adoption and Advanced Automotive Electronics Integration
The Philippines transition toward electric mobility is accelerating demand for advanced in-vehicle computer systems required for battery management, connectivity, energy optimization, and intelligent vehicle control. Government support through the Electric Vehicle Industry Development Act (EVIDA) is encouraging EV ecosystem development and increasing interest among manufacturers, fleet operators, and consumers. According to the Philippine Statistics Authority, registered electric vehicles increased from 1,359 units in 2023 to 6,697 units in 2024, indicating accelerating adoption of electrified transportation technologies. The country’s renewable energy capacity reached approximately 9.7 gigawatts of installed renewable power capacity in 2024, according to the Department of Energy, supporting long-term electrification objectives. The World Bank reported that urban population concentration continues increasing, with approximately 48 million people living in urban areas in 2024, creating demand for efficient and technology-enabled transportation systems. Electric and hybrid vehicles require significantly more computing capability compared with conventional vehicles due to dependence on electronic control units, battery monitoring systems, and software-based vehicle functions. Increasing deployment of EV platforms, smart mobility solutions, and connected vehicle technologies is encouraging automotive manufacturers and suppliers to integrate advanced computing architectures across passenger and commercial vehicles.
Market Challenges
High Dependence on Imported Automotive Electronics and Semiconductor Components
The Philippines In-Vehicle Computer System Market faces challenges due to limited domestic production capabilities for advanced automotive semiconductors, processors, and electronic computing components. Most vehicle computing hardware, including automotive-grade chips, memory modules, connectivity controllers, and processing units, is sourced from international suppliers, increasing exposure to global supply chain disruptions. According to the Philippine Statistics Authority, the country recorded merchandise imports exceeding USD 137 billion in 2024, highlighting the economy’s dependence on imported technology products and industrial components. The World Bank reported that manufacturing contributed approximately 17% of Philippine GDP in 2024, but domestic production remains concentrated in electronics assembly rather than advanced automotive computing component manufacturing. In-vehicle computer systems require highly reliable processors capable of operating under automotive temperature, safety, and cybersecurity standards, making localization difficult. Dependence on imported technologies increases procurement complexity for automotive OEMs, distributors, and technology integrators. Exchange rate fluctuations, international logistics disruptions, and semiconductor availability issues can affect deployment timelines for advanced vehicle electronics. The limited presence of domestic automotive software and hardware development ecosystems further increases reliance on global technology suppliers for next-generation vehicle computing solutions.
Cybersecurity Risks and Complexity of Automotive Software Integration
The increasing complexity of connected vehicle architectures creates challenges related to cybersecurity, software compatibility, and system integration within the Philippines In-Vehicle Computer System Market. Modern vehicles integrate multiple computing domains, including infotainment, telematics, ADAS, navigation, and vehicle control systems, requiring secure communication between hardware and software platforms. According to the Department of Information and Communications Technology, the Philippines continues strengthening national cybersecurity capabilities as digital services expand across industries. The country recorded approximately 85 million internet users in 2024, according to international digital connectivity indicators, increasing the importance of protecting connected platforms from cybersecurity threats. Automotive computing systems collect and process vehicle location data, driver information, diagnostic information, and connectivity data, requiring advanced encryption and cybersecurity frameworks. The implementation of over-the-air software updates, cloud-based vehicle services, and AI-powered driving functions creates additional complexity for manufacturers and technology providers. Limited availability of specialized automotive software engineering capabilities within the local market can slow development and deployment of advanced vehicle computing solutions. Companies operating in the Philippines must invest in cybersecurity frameworks, software validation processes, and technology partnerships to ensure reliable implementation of connected automotive systems.
Market Opportunities
Development of Smart Mobility Platforms and Connected Fleet Management Solutions
The Philippines In-Vehicle Computer System Market has significant opportunities through expansion of smart mobility platforms, fleet digitization, and connected transportation solutions. Increasing demand for logistics efficiency, public transportation modernization, and real-time vehicle monitoring is creating opportunities for telematics computers, vehicle gateway systems, and cloud-connected automotive platforms. The Department of Transportation continues implementing transportation modernization programs aimed at improving mobility efficiency and digital integration across transportation networks. The Philippines logistics sector continues expanding alongside economic growth, supported by the country’s GDP of approximately USD 461 billion in 2024, according to the World Bank. Fleet operators are increasingly adopting digital tracking, predictive maintenance, route optimization, and driver monitoring technologies that require advanced in-vehicle computing capabilities. The country’s road transportation system supports millions of commercial and passenger vehicles, creating a large opportunity for aftermarket and OEM-installed computing solutions. Growth in e-commerce activity, urban logistics demand, and public transportation modernization will encourage adoption of connected vehicle technologies. Advanced in-vehicle computers capable of processing real-time vehicle data, supporting communication networks, and integrating cloud services are expected to become increasingly important for mobility operators.
Expansion of Electric Vehicle Ecosystem and Software-Defined Vehicle Technologies
The Philippines shift toward electric mobility and software-defined vehicle architectures provides opportunities for suppliers of advanced automotive computing systems. Electric vehicles require centralized computing platforms capable of managing battery systems, charging information, energy efficiency, connectivity, and autonomous driving features. The Electric Vehicle Industry Development Act provides a framework supporting EV adoption, manufacturing development, and infrastructure expansion within the country. According to the Department of Energy, the Philippines continues increasing investments in clean energy development, with renewable energy capacity reaching 9.7 gigawatts in 2024, supporting broader electrification objectives. The growth of EV adoption, combined with increasing consumer demand for connected features, creates opportunities for automotive computing suppliers offering digital cockpit systems, AI processors, and vehicle software platforms. The country’s growing electronics manufacturing base also provides potential opportunities for automotive technology integration and component localization. Increasing adoption of centralized vehicle computers, advanced driver assistance systems, and over-the-air software updates will create demand for high-performance computing solutions. Automotive manufacturers and technology providers can leverage the Philippines’ expanding digital ecosystem to develop connected and intelligent vehicle platforms for domestic and regional markets.
Future Outlook
Over the next decade, the Philippines In-Vehicle Computer System Market is expected to demonstrate significant expansion driven by increasing vehicle connectivity, electrification initiatives, digital transformation of transportation systems, and growing adoption of advanced automotive electronics. The transition toward software-defined vehicles, smart mobility platforms, and AI-enabled vehicle functions will accelerate demand for centralized computing architectures. Increasing electric vehicle adoption, supported by government initiatives such as the Electric Vehicle Industry Development Act (EVIDA), will further encourage integration of battery management computing, connectivity platforms, and intelligent vehicle systems.
The market is expected to benefit from increasing deployment of telematics solutions among logistics operators, public transportation providers, and commercial fleets. Rising demand for real-time vehicle monitoring, navigation systems, predictive maintenance, and driver assistance technologies will encourage manufacturers and technology providers to develop advanced computing platforms. The expansion of connected vehicle infrastructure across major urban centers including Metro Manila, Cebu, and Davao will create opportunities for automotive electronics suppliers, semiconductor companies, and software solution providers.
Major Players
- Bosch Mobility – Automotive Computing Platforms, Telematics Systems and Advanced Vehicle Electronics Solutions
- Continental AG – Digital Cockpit Systems, Vehicle Computers and Connected Mobility Platforms
- Harman International – Infotainment Computing Systems, Smart Cockpit Solutions and Connected Vehicle Technologies
- Denso Corporation – Automotive Electronics, Vehicle Control Systems and Embedded Computing Solutions
- LG Electronics Vehicle Component Solutions – Digital Cockpit Platforms, Infotainment Systems and Automotive Software Solutions
- Panasonic Automotive Systems – Vehicle Information Systems, Connectivity Platforms and Automotive Computing Solutions
- Aptiv PLC – Central Vehicle Computing Platforms, ADAS Computing Systems and Mobility Technologies
- Valeo SE – Smart Cockpit Systems, Vehicle Electronics and Driver Assistance Computing Solutions
- ZF Friedrichshafen AG – Autonomous Driving Computers, Vehicle Control Systems and Automotive Software Platforms
- Visteon Corporation – Digital Instrument Clusters, Cockpit Computing Systems and Vehicle Electronics Platforms
- NXP Semiconductors – Automotive Processors, Microcontrollers and Secure Vehicle Computing Solutions
- Qualcomm Technologies – Automotive AI Platforms, Snapdragon Cockpit Systems and 5G Vehicle Connectivity Solutions
- Renesas Electronics Corporation – Automotive Semiconductor Solutions, Microcontrollers and Embedded Computing Platforms
- Ficosa International – Telematics Control Units, Connectivity Systems and Vehicle Electronics Solutions
- BYD Company Limited – Electric Vehicle Computing Platforms, Smart Cockpit Systems and New Energy Vehicle Electronics
Key Target Audience
- Automotive Original Equipment Manufacturers (OEMs)
- Automotive Tier-1 and Tier-2 Electronics Suppliers
- Electric Vehicle Manufacturers and Battery Technology Companies
- Fleet Management Companies and Transportation Operators
- Automotive Software and Connected Vehicle Solution Providers
- Investments and Venture Capitalist Firms (Automotive Technology Investment Funds, Mobility Technology Investors, Electric Vehicle Investment Firms)
- Government and Regulatory Bodies (Department of Transportation, Land Transportation Office, Department of Energy, Board of Investments Philippines)
- Automotive Dealership Groups and Vehicle Distribution Companies
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves developing a comprehensive ecosystem map covering automotive manufacturers, technology suppliers, semiconductor providers, connectivity companies, fleet operators, and regulatory stakeholders operating within the Philippines In-Vehicle Computer System Market. This stage includes extensive secondary research through automotive databases, government transportation statistics, industry publications, and technology adoption assessments to identify critical market variables such as vehicle electronics penetration, connected vehicle adoption, EV integration, and computing architecture development.
Step 2: Market Analysis and Construction
This phase focuses on analysing historical market performance, vehicle deployment trends, automotive electronics adoption, and technology integration patterns within the Philippines automotive ecosystem. The analysis evaluates installation volumes of infotainment computers, telematics units, digital cockpit systems, ADAS computing platforms, and centralized vehicle computers. Demand-side and supply-side assessments are conducted to understand OEM requirements, consumer preferences, fleet operator adoption, and technology supplier capabilities.
Step 3: Hypothesis Validation and Expert Consultation
Market assumptions and growth hypotheses are validated through structured discussions with automotive industry stakeholders, technology suppliers, vehicle distributors, and mobility solution providers. Expert consultations focus on understanding current and future adoption trends related to connected vehicles, electric mobility, autonomous driving technologies, cybersecurity requirements, and software-defined vehicle architectures. These insights support validation of market dynamics and technology adoption scenarios.
Step 4: Research Synthesis and Final Output
The final stage integrates findings from primary and secondary research to develop a comprehensive assessment of the Philippines In-Vehicle Computer System Market. Data obtained from automotive manufacturers, electronics suppliers, government transportation agencies, and mobility companies is analyzed to validate market trends. The final output provides insights into market structure, competitive landscape, technology evolution, segmentation, and future opportunities for industry stakeholders.

- Executive Summary
- Research Methodology (Market Definition and Scope, Philippines In-Vehicle Computer System Classification, Automotive Computing Architecture Assessment, Connected Vehicle Ecosystem Mapping, Digital Cockpit System Evaluation, Advanced Driver Assistance System Computing Analysis, Telematics Control Unit Assessment, Vehicle Gateway Computing Architecture Mapping, Electric Vehicle Computing Platform Analysis, Automotive Semiconductor Integration Assessment, Hardware and Software Component Taxonomy, OEM and Tier Supplier Ecosystem Mapping)

- Definition and Scope
- Philippines In-Vehicle Computer System Industry Evolution and Development of Connected Mobility and Smart Transportation Ecosystem
- Automotive Computing Architecture, Hardware Configuration and Software Integration Structure
- Philippines In-Vehicle Computer System Value Chain Analysis
- Philippines In-Vehicle Computer System Supply Chain Analysis
- Infotainment Computer, Digital Cockpit Computer, Telematics Computer, ADAS Computer, Vehicle Gateway Computer and Central Computing Platform Ecosystem Analysis
- Vehicle Computing System Integration Assessment Across Passenger Vehicles, Commercial Vehicles, Electric Vehicles and Fleet Transportation Platforms

- Growth Drivers (Increasing Vehicle Connectivity Adoption, Expansion of Electric Vehicle Ecosystem, Rising Demand for Digital Cockpit Technologies, Growth of Fleet Management Solutions, Increasing Automotive Electronics Integration, Development of Smart Transportation Infrastructure, Rising Demand for Advanced Driver Assistance Systems)
- Market Challenges (High Dependence on Imported Automotive Electronics Components, Limited Domestic Semiconductor Manufacturing Capability, High Technology Integration Complexity, Cybersecurity Risks in Connected Vehicles, Limited Local Automotive Software Development Ecosystem, Cost Sensitivity Among Vehicle Buyers)
- Market Opportunities (Expansion of Connected Public Transportation Systems, Growth of Electric Vehicle Manufacturing and Adoption, Development of Smart City Mobility Solutions, Increasing Demand for Vehicle Telematics Platforms, Expansion of Automotive Software Services, Increasing Adoption of AI-Based Vehicle Computing Systems)
- Market Trends (Adoption of Software Defined Vehicles, Growth of Centralized Vehicle Computing Architecture, Increasing Use of Artificial Intelligence in Automotive Systems, Expansion of Connected Fleet Platforms, Development of Smart Cockpit Solutions, Increasing Over-The-Air Software Updates, Growth of Vehicle Data Analytics Platforms)
- Government Regulations and Standards (Department of Transportation Smart Mobility Initiatives, Land Transportation Office Vehicle Technology Regulations, Electric Vehicle Industry Development Act Framework, Data Privacy Regulations, Automotive Safety Standards, Telecommunications Connectivity Regulations)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Competition Ecosystem

- By Market Value (2020-2025)
- By In-Vehicle Computer System Installation Volume (2020-2025)
- By Passenger Vehicle In-Vehicle Computer System Deployment Volume (2020-2025)
- By Commercial Vehicle In-Vehicle Computer System Deployment Volume (2020-2025)
- By Electric Vehicle Computing Platform Deployment Volume (2020-2025)
- By Connected Vehicle Computing System Deployment Volume (2020-2025)
- By Fleet Telematics Computing System Deployment Volume (2020-2025)
- By Aftermarket In-Vehicle Computer System Upgrade Volume (2020-2025)

- By System Type (In Value %)
Infotainment Computer Systems
Digital Cockpit Computer Systems
Telematics Control Unit Computing Systems
Advanced Driver Assistance System Computing Platforms
Vehicle Gateway Computer Systems
Central Vehicle Computing Platforms
Instrument Cluster Computing Systems
Rear Seat Entertainment Computing Systems - By Vehicle Type (In Value %)
Passenger Cars
Premium Passenger Vehicles
Electric Passenger Vehicles
Hybrid Vehicles
Light Commercial Vehicles
Heavy Commercial Vehicles
Public Utility Vehicles
Buses and Fleet Vehicles
Special Purpose Vehicles - By Propulsion Type (In Value %)
Internal Combustion Engine Vehicles
Gasoline Vehicles
Diesel Vehicles
Hybrid Electric Vehicles
Plug-in Hybrid Electric Vehicles
Battery Electric Vehicles
Fuel Cell Electric Vehicles - By Component Type (In Value %)
Automotive Processor and Semiconductor Units
Memory and Storage Modules
Display Processing Units
Connectivity Modules
Sensor Processing Modules
Software Platforms and Operating Systems
Cybersecurity and Data Management Systems
Artificial Intelligence Computing Modules - By Application Type (In Value %)
Vehicle Infotainment Applications
Digital Cockpit Applications
Navigation and Connected Services
ADAS Computing Applications
Vehicle Diagnostics and Monitoring Systems
Fleet Management and Telematics Applications
Vehicle-to-Everything Communication Systems
Autonomous Driving Computing Applications - By Connectivity Technology (In Value %)
4G LTE Connected Vehicle Systems
5G Automotive Computing Systems
Bluetooth and Wi-Fi Enabled Vehicle Systems
Vehicle-to-Vehicle Communication Systems
Vehicle-to-Infrastructure Communication Systems
Cloud Connected Vehicle Platforms - By Sales Channel (In Value %)
Automotive OEM Integration
Tier-1 Automotive Electronics Suppliers
Automotive Technology Solution Providers
Fleet Management Solution Providers
Independent Automotive Electronics Installers
Online Automotive Electronics Platforms - By Region (In Value %)
Metro Manila
CALABARZON Automotive Manufacturing Cluster
Central Luzon Automotive Industrial Region
Cebu Automotive Distribution Hub
Davao Mobility and Transportation Region
Northern Luzon Commercial Vehicle Market

- Market Share of Major Players (By Revenue, System Type, Vehicle Segment, Propulsion Type, OEM Integration Contracts, Computing Platform Deployment, Connectivity Technology Adoption, Customer Base Distribution)
- Cross Comparison Parameters (Automotive Computing Platform Portfolio Breadth, Digital Cockpit Technology Capability, ADAS Computing Performance, Connected Vehicle Platform Integration Capability, Automotive Semiconductor and Processor Integration Expertise, Software Development and Over-The-Air Update Capability, OEM and Tier-1 Supply Network Coverage, Cybersecurity and Data Protection Technology Capability)
- SWOT Analysis of Major Players
- Pricing and Product Category Benchmarking
- Detailed Profiles of Major Companies
Bosch Mobility – Automotive Computing Platforms, Telematics Systems and Vehicle Electronics Solutions
Continental AG – Digital Cockpit Systems, Vehicle Computers and Connected Mobility Platforms
Harman International – Infotainment Computers, Smart Cockpit Solutions and Connected Vehicle Systems
Denso Corporation – Automotive Electronics, Computing Modules and Connectivity Platforms
LG Electronics Vehicle Component Solutions – Digital Cockpit Platforms and Automotive Computing Systems
Panasonic Automotive Systems – Vehicle Infotainment Computers and Connected Mobility Solutions
Aptiv PLC – Central Vehicle Computing Platforms and Advanced Mobility Technologies
Valeo SE – Smart Cockpit Systems, ADAS Computing and Vehicle Electronics Solutions
ZF Friedrichshafen AG – Autonomous Driving Computers and Vehicle Computing Architecture
Visteon Corporation – Digital Cockpit Computing Systems and Automotive Electronics Platforms
NXP Semiconductors – Automotive Processors, Microcontrollers and Vehicle Computing Solutions
Qualcomm Technologies – Automotive Cockpit Platforms and Connected Vehicle Computing Technologies
Renesas Electronics Corporation – Automotive Semiconductor Solutions and Computing Platforms
Ficosa International – Telematics Systems and Vehicle Connectivity Solutions
VinFast – Electric Vehicle Computing Platforms and Smart Vehicle Architecture Solutions

- End User Segmentation Assessment
- Passenger Vehicle Manufacturer Analysis
- Electric Vehicle Manufacturer Analysis
- Commercial Vehicle Manufacturer Analysis
- Public Utility Vehicle Operator Analysis
- Fleet Operator and Logistics Company Analysis
- Automotive Tier-1 Supplier Analysis
- Connected Vehicle Service Provider Analysis
- Automotive Aftermarket Electronics Installer Analysis

- By Market Value (2026-2035)
- By In-Vehicle Computer System Installation Volume (2026-2035)
- By Passenger Vehicle In-Vehicle Computer System Deployment Volume (2026-2035)
- By Commercial Vehicle In-Vehicle Computer System Deployment Volume (2026-2035)
- By Electric Vehicle Computing Platform Deployment Volume (2026-2035)
- By Connected Vehicle Computing System Deployment Volume (2026-2035)
- By Advanced Driver Assistance Computing System Deployment Volume (2026-2035)
- By Fleet Telematics Computing System Deployment Volume (2026-2035)
- By Aftermarket In-Vehicle Computer System Upgrade Volume (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
