
 Download PDF
Market Overview
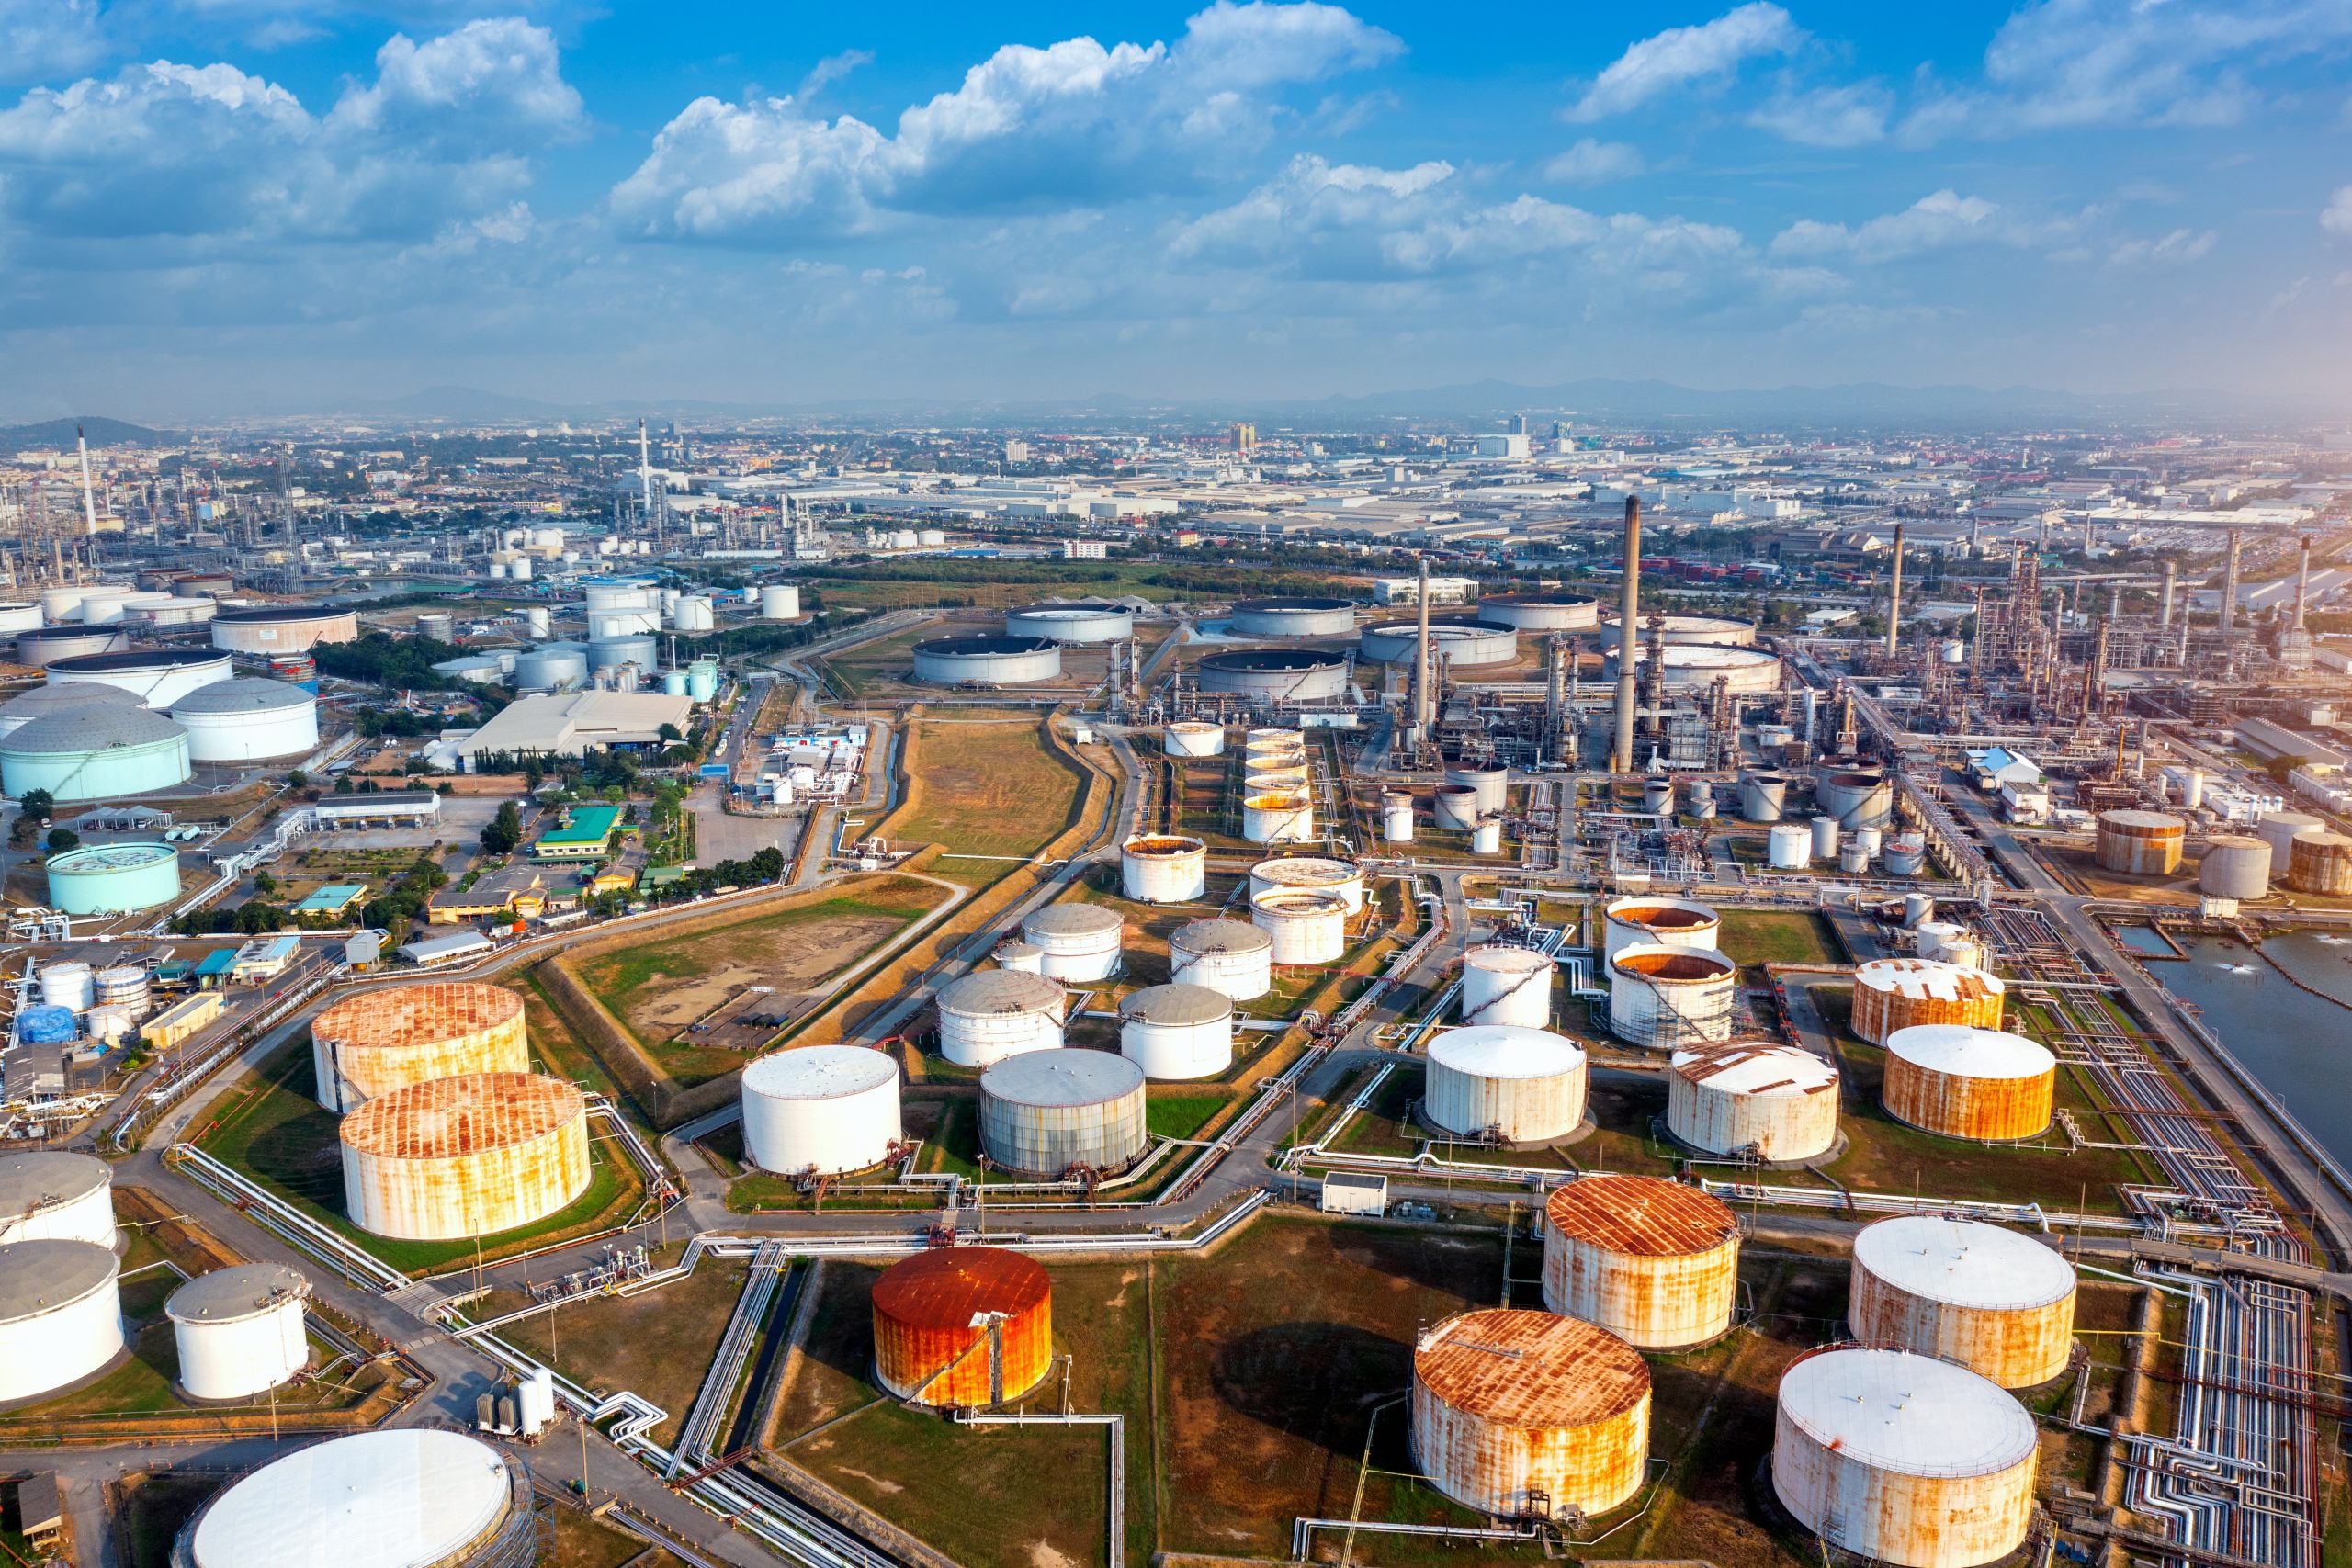
The Philippines LNG infrastructure market is currently valued at USD 2.45 billion in 2025, expanding at an 8.4% CAGR through 2035 as the nation pivots toward cleaner energy alternatives to mitigate the depletion of the Malampaya gas field. Strategic industrial hubs such as Batangas City serve as the epicenter of this expansion, hosting critical floating storage and regasification unit terminals that act as the gateway for imported liquefied natural gas. Concurrently, Bataan has emerged as a secondary nexus for investment, facilitating integrated power plant projects that consolidate downstream distribution capabilities. A significant demand-side driver is the rapid electrification of the Luzon grid, necessitated by the increasing energy intensity of local manufacturing sectors, while a prominent supply-side trend involves the aggressive expansion of import capacity through private-public partnerships designed to stabilize energy pricing. Regulatory oversight is governed by the Philippine Department of Energy under the Philippine Energy Plan 2023-2050, which mandates stricter compliance with international environmental safeguards and carbon reduction protocols. As the country aligns with the Net Zero Emission goals, the push for cleaner transition fuels is fundamentally reshaping infrastructure financing models and accelerating the integration of advanced pipeline networks into the national energy architecture.
By Facility Type
- BW Integrity vessel
- Höegh Gallant barge
- Excelerate Sequoia units
- Full containment tanks
- Cryogenic loading arms
- BOG handling systems
- ISO tank containers
- Modular regasification skids
- Truck-loading gantries
- LNG carrier conversion
- Mooring dolphin systems
- Subsea flowline connections
By End-User Application
- Combined cycle gas turbines
- Open cycle peaking units
- Gas-to-power grid conversion
- Ceramic kilns heating
- Steel rolling mill furnaces
- Food processing steam boilers
- District cooling systems
- Large-scale kitchen cooking
- Commercial laundry heating
- LNG-fueled inter-island ferries
- Heavy-duty haulage trucks
- Port machinery engine conversion
Competitive Landscape
The Philippines LNG infrastructure market is characterized by high competitive intensity as energy conglomerates and international consortiums vie for dominance under the Department of Energy's (DOE) Philippine Energy Plan 2020-2040. The market structure is an oligopoly, dominated by vertically integrated players who control critical midstream assets including Floating Storage Regasification Units (FSRUs) and onshore receiving terminals. Strategic distribution relies on heavy integration with existing gas-fired power plants in the Batangas and Bataan provinces to ensure baseload stability, particularly as the Malampaya gas field reserves deplete. Key competitive moves include aggressive joint-venture partnerships between domestic conglomerates and global LNG operators to mitigate capital expenditure risks. Companies like Atlantic, Gulf & Pacific (AG&P) and SMC Global Power are prioritizing rapid deployment of modular LNG infrastructure to meet the 2025 energy security targets mandated by the DOE. Distribution strategy focuses on the 'Gas Hub' model, where firms prioritize proximity to industrial clusters in the CALABARZON region to minimize transport overheads and leverage economies of scale in regasification services.
| Company | Est. Year | Headquarters | Details | Details | Details | Details | Details | Details |
|---|---|---|---|---|---|---|---|---|
| SMC Global Power | 2008 | Mandaluyong, Philippines | ~ | ~ | ~ | ~ | ~ | ~ |
| Atlantic, Gulf & Pacific | 1900 | Makati, Philippines | ~ | ~ | ~ | ~ | ~ | ~ |
| First Gen Corporation | 1998 | Pasig, Philippines | ~ | ~ | ~ | ~ | ~ | ~ |
| Prime Infrastructure Capital | 2017 | Taguig, Philippines | ~ | ~ | ~ | ~ | ~ | ~ |
| Energy World Corporation | 1988 | Quezon City, Philippines | ~ | ~ | ~ | ~ | ~ | ~ |
🔒 Detailed cross-comparison data are available in the full report. Talk to Us to access complete competitive intelligence.
Growth Drivers
Energy Security Mandates
The Department of Energy in the Philippines has fast-tracked the Philippine Energy Plan 2023–2050 to reduce reliance on aging Malampaya gas fields which reached 40 percent production decline by 2022. This policy transition compels domestic power providers to adopt Liquefied Natural Gas to bridge the gap between coal-phaseout targets and grid stability requirements. Investments are pouring into FSRU terminals in Batangas City to ensure continuous supply for Luzon’s industrial heartland, where peak electricity demand surged to 12,130 megawatts during the 2023 summer period alone.
Industrial Decarbonization Initiatives
Manufacturing hubs located in the Cavite Economic Zone and Laguna province are transitioning toward cleaner fuel alternatives to comply with international carbon reporting standards. LNG currently serves as a vital transition fuel, significantly lowering particulate emissions compared to traditional bunker fuel oil. Recent infrastructure development projects by AG&P, founded in 1900 and headquartered in Manila, provide the necessary regasification capacity to support over 1,200 heavy industries. These plants effectively reduce local sulfur oxide output by 85 percent compared to operations using high-sulfur diesel fuel sources.
Private Sector Capital Influx
Large-scale consortiums are aggressively expanding domestic energy infrastructure to capitalize on the liberalization of the downstream gas sector. Companies like First Gen Corporation, established in 1998 and headquartered in Pasig City, have successfully commissioned the Batangas LNG terminal to support 2,000 megawatts of combined-cycle power capacity. The deployment of private capital ensures that the regional LNG storage volume expands to 170,000 cubic meters by 2025. This localized infrastructure shift minimizes logistics costs by bypassing traditional long-haul supply chains from regional secondary ports.
Grid Modernization Requirements
The National Grid Corporation of the Philippines is integrating modular gas-fired power plants to stabilize the national transmission backbone against intermittency issues. These plants are strategically located near Metro Manila to provide critical frequency control and baseload power during periods of low renewable energy generation. By 2024, the grid successfully integrated 850 megawatts of new gas-fired capacity specifically designed to mitigate voltage fluctuations. This technical integration ensures that the transmission infrastructure remains reliable as the country targets a 35 percent share of renewables in the total mix.
Market Challenges
Geopolitical Price Volatility
The reliance on imported LNG exposes the Philippine market to extreme global spot-market price fluctuations. In 2023, the cost of delivered cargo surged to 35 dollars per million British thermal units during peak winter demand, straining the operational margins of local utilities.
Infrastructure Financing Barriers
Tightening global credit conditions have increased the weighted average cost of capital for massive capital-intensive LNG terminal construction projects. Currently, domestic banks have capped infrastructure project lending at 20 percent of their total loan portfolios to mitigate exposure to large-scale commodity price risks.
Logistics and Storage Constraints
The archipelagic geography of the Philippines creates significant hurdles for the distribution of regasified fuel to remote islands. Only 15 percent of the national pipeline infrastructure is currently equipped to handle high-pressure cryogenic transport, necessitating expensive small-scale LNG bunkering solutions.
Opportunities
Floating Storage Regasification Units
Deploying FSRU vessels offers a cost-effective solution for rapid deployment in Batangas Bay to support immediate energy demand. By bypassing the multi-year construction timelines of land-based terminals, companies can leverage existing offshore berths to facilitate gas intake. Currently, 2.2 million tons of annual regasification capacity has been enabled through modular floating units, allowing power plants to switch from coal to cleaner natural gas inputs without significant infrastructure delays.
Natural Gas Distribution Pipelines
Expansion of high-pressure pipeline networks into the Luzon industrial corridors provides a critical opportunity for last-mile connectivity. Connecting the Ilijan power facility to manufacturing hubs in Cavite enables stable supply for high-demand industrial processes. A recent investment initiative secured 450 kilometers of pipeline infrastructure to stabilize energy delivery, ensuring that captive power users remain insulated from the supply volatility historically associated with imported thermal coal and diesel generators.
Small-Scale LNG Distribution
Inter-island distribution via specialized cryogenic ISO tanks allows reaching power-starved regions in the Visayas and Mindanao. This decentralized approach circumvents the need for massive grid expansion, enabling local cooperatives to power remote tourism hubs and industrial processing zones directly. Market participants are now utilizing 15,000 cubic meters of dedicated tankage to facilitate seamless ship-to-truck transport, bridging the geographical disconnect between primary receiving terminals and the fragmented archipelago electricity demand.
Future Outlook
The Philippines LNG infrastructure market is positioned for significant transformation through 2029, driven by the Department of Energy’s Philippine Energy Plan 2023-2050. As the Malampaya gas field reserves continue to decline, the transition toward imported liquefied natural gas is mandatory to maintain grid stability. Large-scale terminal projects in the Calabarzon region, particularly those spearheaded by Atlantic Gulf & Pacific Company founded in 1900 in Manila and Prime Infrastructure Capital founded in 2017 in Taguig, will serve as the backbone for national energy security. The regulatory environment, overseen by the Energy Regulatory Commission, is increasingly favoring public-private partnerships to de-risk capital-intensive regasification projects. Over the next five years, we anticipate a transition from reliance on imported coal to a robust gas-to-power ecosystem, integrated with increasing renewable energy intermittent supply. The strategic focus will shift toward expanding inter-island connectivity and building secondary hubs to serve the growing manufacturing sectors in Cebu and Davao. Although global price volatility remains a structural risk, the Philippine government’s commitment to providing fiscal incentives for LNG-fired power plants ensures a steady demand trajectory. The integration of domestic and imported gas, coupled with the modernization of existing power plants, will solidify the role of LNG as the primary transition fuel for the nation's industrial development, ensuring a reliable power supply for a growing economy.
Major Players
- SMC Global Power
- Atlantic, Gulf & Pacific
- First Gen Corporation
- Prime Infrastructure Capital
- Energy World Corporation
- Lopez Holdings Corporation
- PNOC Exploration Corporation
- Vitol Asia Pte Ltd
- Shell Philippines Exploration
- Mitsubishi Corporation
- Tokyo Gas Co., Ltd.
- Osaka Gas Co., Ltd.
- Chevron Philippines
- Phoenix Petroleum Philippines
- CNOOC Gas and Power
Key Target Audience
- Liquefied Natural Gas (LNG) Terminal Operators (e.g., Atlantic Gulf & Pacific Company, established 1900, Manila)
- Power Generation Utilities (e.g., Aboitiz Power Corporation, established 1998, Taguig City)
- Upstream Oil and Gas Exploration Companies (e.g., PNOC Exploration Corporation, established 1976, Makati)
- Independent Power Producers (e.g., San Miguel Global Power, established 2010, Mandaluyong)
- Petrochemical Manufacturers (e.g., JG Summit Petrochemical Corporation, established 1994, Batangas)
- Infrastructure Investment Trusts (InvITs)
- Government and Regulatory Bodies (Department of Energy - DOE, Philippines)
- Government and Regulatory Bodies (Energy Regulatory Commission - ERC, Philippines)
- Investors and Venture Capital Firms
- EPC Contractors for Energy Infrastructure (e.g., EEI Corporation, established 1931, Quezon City)
- Natural Gas Distribution Network Operators (e.g., Manila Electric Company - Meralco, established 1903, Pasig)
- Port and Terminal Logistics Service Providers
Research Methodology
Identification of Key Variables
- Analysts identify critical variables including domestic LNG consumption targets under the Philippine Energy Plan 2023-2050 and terminal regasification capacities.
- This stage focuses on evaluating infrastructure readiness, regulatory compliance under the Downstream Natural Gas Industry Development Act, and the impact of the Malampaya gas field depletion on energy supply chain stability.
Market Analysis and Construction
- The team aggregates data from the Department of Energy’s official statistical portal and quarterly reports from public corporations like First Gen Corporation.
- We construct supply-demand models incorporating planned investments in FSRU (Floating Storage Regasification Unit) terminals and pipeline expansions across Luzon, Visayas, and Mindanao regions through 2030.
Validation and Synthesis
- Primary validation involves structured discussions with senior regulatory policy analysts, lead engineers at domestic power utilities, and independent project finance specialists.
- These experts assess market entry barriers and capital expenditure requirements for greenfield LNG storage facilities, ensuring that our quantitative forecasts align with practical industry realities and infrastructure constraints.
- All gathered data and expert insights are normalized into a comprehensive market intelligence report.
- We synthesize regional project pipelines, fiscal incentives provided by the Board of Investments, and competitive positioning of key players into actionable strategic recommendations for stakeholders and institutional investors monitoring the Philippines' transition to a gas-powered energy grid.
Table of Contents
 Executive Summary
2 Sections
▼
- Executive Summary
- Research Methodology (DOE Philippine Energy Plan Review, Top-Down Project Pipeline Assessment, Bottom-Up Infrastructure Cost Estimation, Secondary Data Integration Protocols, Key Executive Interview Methodology, Supply Side Capacity Modeling, Demand Side Consumption Projection, Regional Energy Grid Analysis, Regulatory Framework Impact Assessment, Triangulation of Financial Disclosures, Forecast Modeling Framework Definition, Geopolitical Risk Limitation Assessment)
 Philippines LNG Infrastructure Market Overview
8 Sections
▼
- Definition and Scope
- Market Evolution and Industry Genesis
- Philippines Energy Security Roadmap Implementation
- LNG Importation Infrastructure and Terminal Development
- FSRU Technology Adoption in Batangas Bay
- Natural Gas Power Plant Integration Strategies
- Downstream Pipeline Network Expansion Projects
- Regional LNG Supply Chain Regulatory Framework
 Philippines LNG Infrastructure Market Size (2020-2025)
3 Sections
▼
- By Market Value (2020-2025)
- By Annual LNG Import Capacity (2020-2025)
- By Operational Natural Gas Output (2020-2025)
 Philippines LNG Infrastructure Market Segmentation
47 Segments
▼
- By Infrastructure Facility (In Value %)
- Floating Storage Regasification Units (FSRU)
- Floating Storage Units (FSU)
- Mooring and Berthing Systems
- Regasification Modules
- Ship-to-Ship Transfer Systems
- Onshore LNG Regasification Terminals
- LNG Storage Tanks
- Vaporization Units
- Loading and Unloading Arms
- Boil-off Gas Recovery Systems
- Pipeline Infrastructure
- Onshore Transmission Pipelines
- Offshore Subsea Pipelines
- Metering and Pressure Stations
- Gas Processing Facilities
- LNG Distribution and Bunkering
- LNG Truck Loading Bays
- Small-Scale LNG Carriers
- Iso-Tank Distribution
- Small-Scale Regasification Units
- By Ownership Structure (In Value %)
- Public-Private Partnership Projects
- Independent Power Producer Assets
- State-Owned Energy Investments
- Joint Venture Developments
- Direct Foreign Investment Projects
- By Geographic Region (In Value %)
- Luzon Grid Infrastructure
- Visayas Distribution Nodes
- Mindanao Energy Clusters
- Special Economic Zones
- By Technology Maturity (In Value %)
- Brownfield Facility Upgrades
- Greenfield Infrastructure Projects
- Modular Deployment Systems
- By Supply Chain Tier (In Value %)
- Upstream LNG Sourcing
- Midstream Storage and Regasification
- Downstream Gas Delivery
- By Application (In Value %)
- Power Generation Sector
- Industrial Manufacturing
- Transportation and Logistics
- Commercial Building Operations
- Petrochemical Feedstock
- Residential Utility Supply
 Philippines LNG Infrastructure Market Analysis
8 Sections
▼
- Growth Drivers (Energy Security Mandates, Industrial Decarbonization Initiatives, Private Sector Capital Influx, Grid Modernization Requirements)
- Market Challenges (Geopolitical Price Volatility, Infrastructure Financing Barriers, Logistics and Storage Constraints)
- Market Opportunities (Floating Storage Regasification Units, Natural Gas Distribution Pipelines, Small-Scale LNG Distribution)
- Market Trends (Energy Transition, Decarbonization Mandates, FSRU Proliferation, Supply Security)
- Government Regulations
- SWOT Analysis
- Porter's Five Forces Analysis
- PESTLE Analysis
 Philippines LNG Infrastructure Market Competitive Analysis
19 Sections
▼
- Market Share of Major Players
- FSRU versus Land-Based Terminal Competition
- Public versus Private Sector Project Leadership
- Domestic Consortium versus Global Energy Conglomerates
- Batangas Industrial Hub Infrastructure Rivalry
- Power Producer Captive Infrastructure Landscape
- Small-Scale LNG Distribution Competitive Dynamics
- Cross Comparison Parameters (Project Capital Expenditure Requirements, Operational Availability and Reliability, Pipeline Throughput Capacity, Regulatory Compliance and Permitting Track, Storage Tank Volume Capacity, Technological Integration with Grid, Supply Contract Flexibility Terms, Environmental Mitigation Strategy)
- Competitive Product Benchmarking (Regasification Hourly Capacity, Storage Tank Material Composition, Boil-off Gas Management Rate, Safety System Certification Standards, Operational Lifecycle Expectancy, Construction Completion Timeline, Interconnectivity with Existing Pipelines)
- Financial and Operational Parameters
- SWOT Analysis of Major Players
- Detailed Profiles of Major Companies
- Aboitiz Power (est. 1920, Manila) – Therma Luzon, Aboitiz InfraCapital, GNPower
- First Gen Corporation (est. 1998, Pasig City) – FG Batangas LNG, Bayan LNG, First Gas Power
- San Miguel Corporation (est. 1890, Mandaluyong) – SMC Global Power, Masinloc Power, Ilijan Power
- Atlantic Gulf & Pacific (AG&P) (est. 1900, Manila) – Philippines LNG (PHLNG), AG&P Industrial, Gas Entec
- Shell Pilipinas (est. 1914, Makati) – Shell Energy Philippines, Shell LNG Supply
- Vires Energy Corporation (est. 2018, Manila) – Vires Integrated LNG, Batangas FSRU Project
- PNOC Exploration Corporation (est. 1976, Taguig) – PNOC Infrastructure Assets, State Gas Supply
 Philippines LNG Infrastructure Market End-User Analysis
8 Sections
▼
- Total Annual Gas Consumption Volume
- Power Generation Sector Demand Growth
- Industrial User Energy Dependency Rates
- LNG Penetration within Manufacturing Hubs
- Average Natural Gas Tariff Sensitivity
- Peak Hour Energy Consumption Metrics
- Conversion Rate from Coal to LNG
- Facility-Specific Gas Throughput Requirements
 Philippines LNG Infrastructure Market Future Size (2026-2035)
3 Sections
▼
- By Market Value (2026-2035)
- By Annual LNG Import Capacity (2026-2035)
- By Operational Natural Gas Output (2026-2035)
Frequently Asked Questions
The current market size is USD 2.45 billion in 2025, projected to reach USD 5.49 billion by 2035. This expansion reflects an 8.4% CAGR from 2025 to 2035. The growth is primarily driven by the transition away from depleting Malampaya gas fields to imported Liquefied Natural Gas.
The core growth driver is the national mandate to diversify energy sources as established by the Department of Energy under the Philippine Energy Plan 2023-2050. Increasing industrial electricity demand in economic zones like the Cavite-Laguna-Batangas corridor necessitates stable baseload power. Furthermore, government incentives under the Renewable Energy Act amendments are accelerating the integration of gas-to-power facilities to complement solar and wind energy volatility.
Key market participants include Atlantic Gulf & Pacific Company (AG&P), founded in 1900 and headquartered in Manila, which operates the Philippines LNG terminal in Batangas. SMC Global Power, established in 2010 and based in Mandaluyong, manages significant integrated power projects. Additionally, First Gen Corporation, founded in 1998 and headquartered in Pasig City, maintains a strong footprint in natural gas power generation facilities.
Developers face substantial regulatory hurdles, particularly regarding the permitting processes overseen by the Energy Regulatory Commission. The geographic complexity of the Philippine archipelago increases the logistical costs of deploying floating storage regasification units (FSRUs) across isolated island grids. Moreover, high exposure to volatile global spot prices for LNG creates significant financial uncertainty for private energy firms and power distribution utilities.
A notable trend is the deployment of small-scale LNG supply chains to reach off-grid municipalities and remote industrial zones. Infrastructure designs are increasingly incorporating carbon capture and storage readiness to align with international climate benchmarks. There is also an uptick in joint venture agreements between local conglomerates and international energy firms to mitigate capital expenditure risks and share technical expertise in terminal construction.


 Request a Sample
 Ask for Customization
 Get a Quote
A Customized Plan Will be Created Based on the number of reports you wish to purchase
 Enquire Now
