
 Download PDF
Market Overview
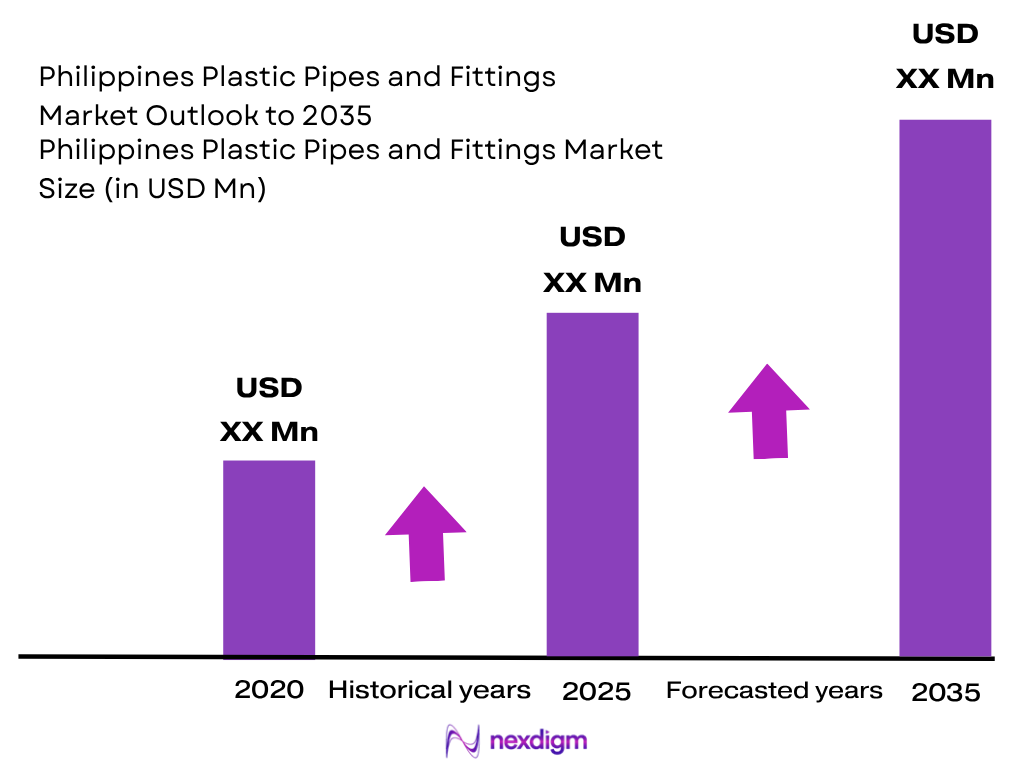
The Philippines Plastic Pipes and Fittings Market is valued at USD ~X billion in 2024, supported by increasing demand from water supply infrastructure, residential construction, wastewater management, agricultural irrigation, and industrial development projects. The market has expanded from USD ~X billion in 2023 due to rising adoption of PVC, HDPE, and PPR piping systems across municipal utilities, real estate projects, and commercial establishments. Growth is influenced by infrastructure modernization, urban expansion, replacement of aging pipeline networks, and increasing preference for lightweight, corrosion-resistant thermoplastic piping solutions.
The Philippines Plastic Pipes and Fittings Market is primarily concentrated in Metro Manila, Central Luzon, Calabarzon, Cebu, and Davao, driven by high construction activity, population concentration, infrastructure development, and industrial expansion. Metro Manila represents a major demand hub due to dense urban development, water utility requirements, and commercial construction projects. Calabarzon and Central Luzon experience strong demand from manufacturing facilities, industrial parks, and residential developments, while Cebu and Davao contribute through regional infrastructure expansion, tourism development, and agricultural irrigation requirements.
Market Segmentation
By Material Type
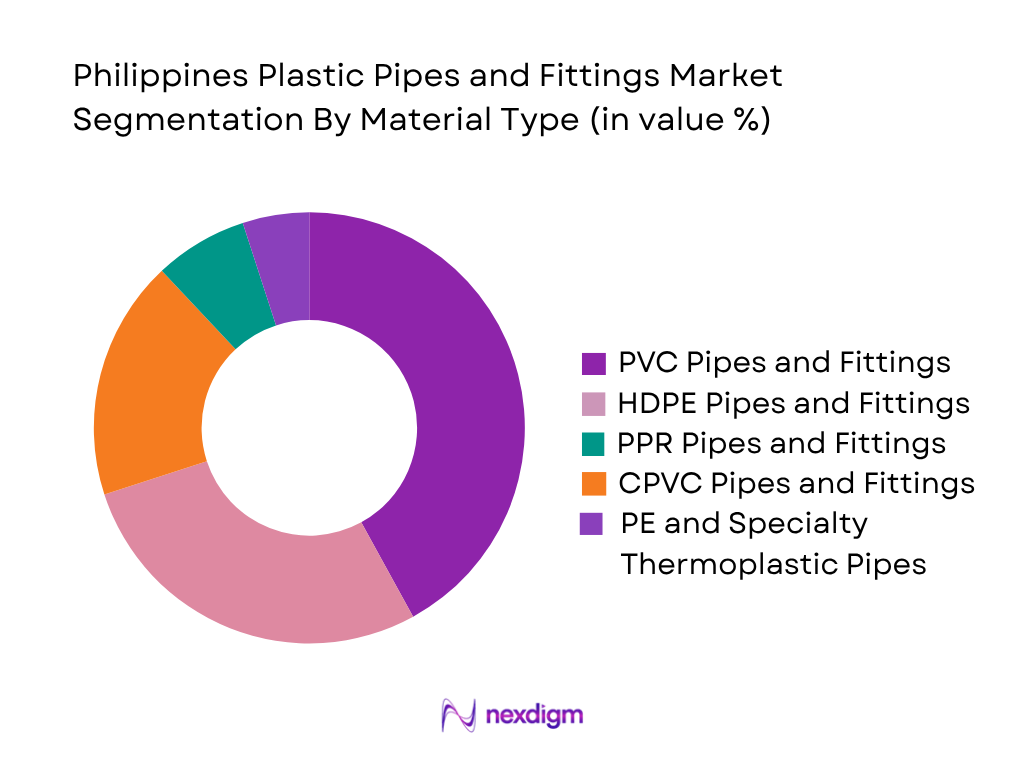
The Philippines Plastic Pipes and Fittings Market is segmented by material type into PVC pipes and fittings, HDPE pipes and fittings, PPR pipes and fittings, CPVC pipes and fittings, PE pipes, and specialty thermoplastic piping systems. Among these, PVC Pipes and Fittings represent the dominant segment in 2024 due to their extensive usage across residential plumbing, drainage systems, water distribution networks, and construction applications. PVC pipes are widely preferred because of their affordability, availability, durability, and compatibility with Philippine construction requirements. Rapid residential development, government housing initiatives, and increasing urban infrastructure projects have strengthened PVC adoption. Additionally, local manufacturers have established extensive production capabilities for PVC products, enabling efficient supply availability across different regions. The segment continues to benefit from demand in low-rise housing projects, commercial buildings, and municipal drainage applications.
By Application Type
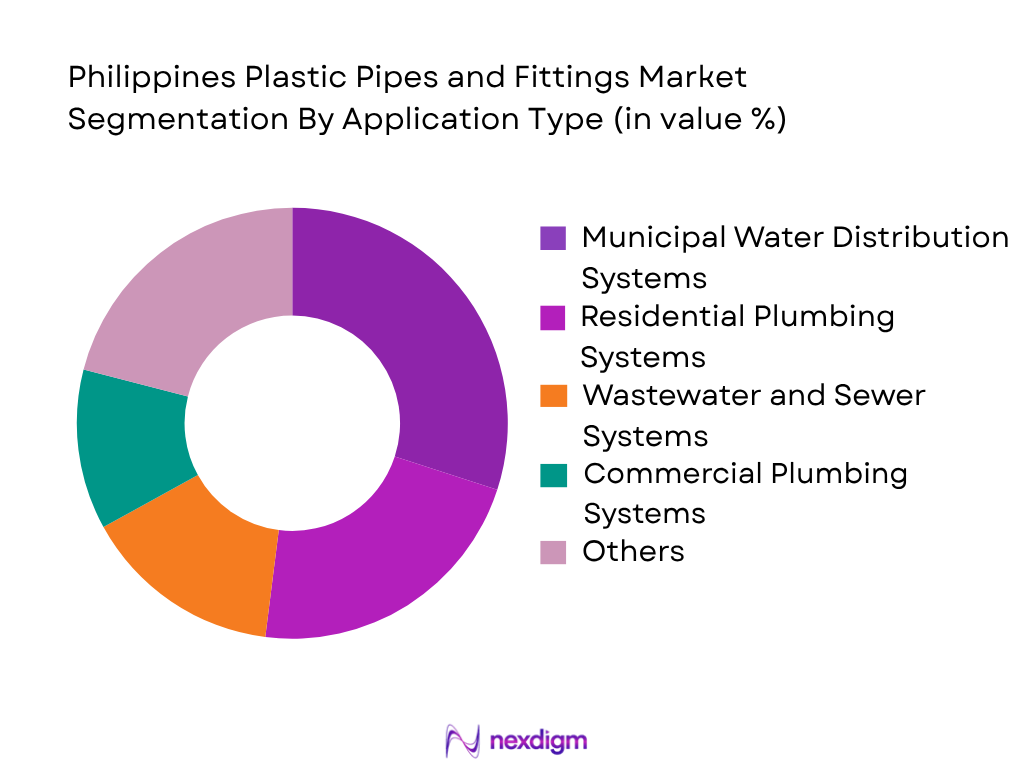
The Philippines Plastic Pipes and Fittings Market is segmented by application into municipal water distribution systems, wastewater and sewer systems, residential plumbing systems, commercial plumbing systems, agricultural irrigation systems, industrial process piping systems, flood control drainage systems, electrical conduit systems, and telecommunication duct systems. The municipal water distribution systems segment holds the leading market share in 2024 due to increasing investments in water infrastructure expansion and improvement of urban water supply networks. Plastic pipes are extensively used in municipal applications because of corrosion resistance, ease of installation, and long service life compared with traditional metal alternatives. The expansion of water utilities in Metro Manila and provincial regions has increased demand for HDPE and PVC pipeline systems. Government infrastructure programs focused on improving water access, sanitation, and flood management continue creating demand for plastic piping solutions across municipal and public infrastructure projects.
Competitive Landscape
The Philippines Plastic Pipes and Fittings Market consists of domestic manufacturers and international companies supplying piping solutions for construction, infrastructure, utility, agricultural, and industrial applications. Domestic companies maintain strong positions through local manufacturing capabilities, regional distribution networks, and familiarity with Philippine construction requirements. International players compete through advanced thermoplastic technologies, specialized piping systems, and global certification capabilities. Competition is primarily based on manufacturing capacity, product portfolio breadth, application expertise, quality certifications, distribution reach, and ability to supply large infrastructure projects.
| Company | Establishment Year | Headquarters | Product Portfolio | Manufacturing Capability | Key Applications | Distribution Network | Technology Capability | Certification Coverage |
| Neltex Development Co. Inc. | 1973 | Philippines | ~ | ~ | ~ | ~ | ~ | ~ |
| Atlanta Industries Inc. | 1977 | Philippines | ~ | ~ | ~ | ~ | ~ | ~ |
| Moldex Products Inc. | 1981 | Philippines | ~ | ~ | ~ | ~ | ~ | ~ |
| Crown Asia Chemicals Corporation | 1995 | Philippines | ~ | ~ | ~ | ~ | ~ | ~ |
| Wavin | 1955 | Netherlands | ~ | ~ | ~ | ~ | ~ | ~ |
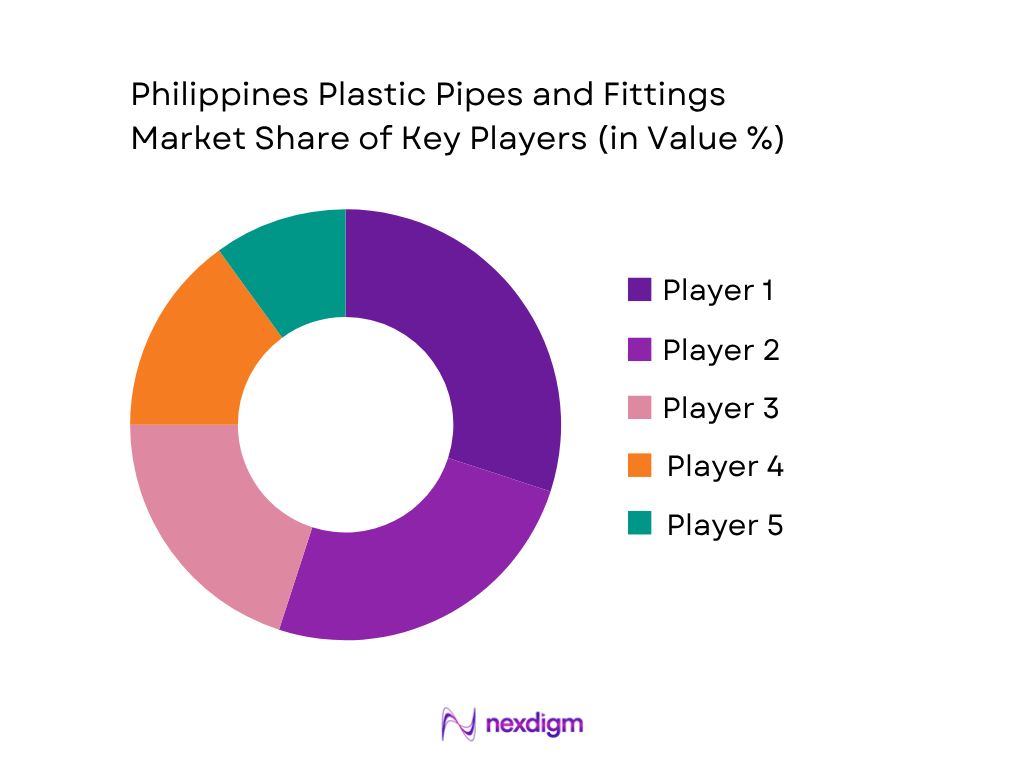
Philippines Plastic Pipes and Fittings Market Analysis
Growth Drivers
Expansion of Water Infrastructure and Urban Utility Networks
The Philippines Plastic Pipes and Fittings Market is supported by increasing investment in water supply systems, wastewater infrastructure, and urban utility networks across metropolitan and regional areas. The country’s population reached approximately 117.3 million people in 2024, according to World Bank demographic indicators, increasing demand for reliable water distribution and sanitation infrastructure. The Philippine Statistics Authority reported that the country’s urban population continued expanding, increasing pressure on cities such as Metro Manila, Cebu, and Davao to improve water accessibility and drainage systems. Plastic pipes, particularly PVC and HDPE systems, are increasingly used in municipal applications due to corrosion resistance, lightweight properties, and suitability for underground installation. The Department of Public Works and Highways allocated approximately PHP 900 billion for infrastructure programs in 2024, supporting road, drainage, flood control, and public utility projects requiring pipeline solutions. Water utilities are also investing in network improvement to reduce leakage and improve supply reliability. The Philippine economy recorded GDP growth of approximately 5.6% in 2023, according to the World Bank, supporting construction activity and infrastructure spending momentum. These developments are strengthening demand for plastic piping systems across municipal water distribution, wastewater management, and urban development projects.
Residential Construction and Industrial Development Supporting Plastic Pipe Adoption
The Philippines Plastic Pipes and Fittings Market benefits from sustained residential construction growth, commercial development, and industrial expansion requiring efficient plumbing and utility systems. The construction sector remains an important contributor to economic activity, with the industry accounting for approximately 6.4% of Philippine GDP in 2023, according to Philippine Statistics Authority economic indicators. Increasing housing demand in Metro Manila, Calabarzon, and Central Luzon has accelerated the adoption of PVC and PPR piping systems for residential water supply, drainage, and sanitation applications. The Philippine government approved more than PHP 1 trillion in infrastructure spending under the national budget framework for 2024, supporting public facilities, transportation-linked development, and urban expansion projects. Industrial regions such as Cavite, Laguna, Batangas, and Cebu continue generating demand for plastic piping systems used in manufacturing facilities, processing plants, and industrial utility networks. According to World Bank data, the Philippines maintained a population growth rate of approximately 1.5%, creating additional requirements for housing, water connectivity, and municipal services. Plastic pipes are increasingly preferred in construction projects because they provide faster installation, lower maintenance requirements, and resistance to corrosion compared with traditional metal piping systems.
Market Challenges
Dependence on Imported Raw Materials and Polymer Supply Fluctuations
The Philippines Plastic Pipes and Fittings Market faces challenges related to dependence on imported polymer materials, particularly PVC resin, polyethylene, and polypropylene required for pipe manufacturing. Although domestic manufacturers operate plastic processing facilities, the country continues relying on international supply chains for specific resin grades and additives used in advanced piping applications. According to Philippine Statistics Authority trade data, the Philippines recorded merchandise imports exceeding USD 137 billion in 2023, reflecting the country’s dependence on imported industrial materials and intermediate goods. Fluctuations in global petrochemical supply conditions can affect availability and procurement planning for plastic pipe manufacturers. The manufacturing sector contributed approximately 17% of Philippine GDP in 2023, according to World Bank economic indicators, increasing competition for polymer resources among multiple industries including packaging, automotive, construction, and consumer goods. Plastic pipe producers must maintain consistent resin quality to meet requirements for pressure pipes, water transmission systems, and industrial applications. Transportation constraints, foreign exchange movements, and international supply disruptions can influence raw material availability. These factors create operational challenges for manufacturers attempting to maintain stable production capacity while meeting infrastructure and construction demand.
Regulatory Compliance Requirements and Competition from Alternative Materials
The Philippines Plastic Pipes and Fittings Market faces challenges related to technical compliance requirements, quality standards, and competition from alternative materials including steel, concrete, and ductile iron piping systems. Plastic pipe manufacturers supplying infrastructure and utility projects must comply with Philippine National Standards, construction specifications, and requirements established by government infrastructure agencies. The Department of Public Works and Highways implemented extensive infrastructure quality requirements for public projects, increasing the importance of certified and technically compliant piping products. The Philippines generated approximately 61 million tonnes of solid waste annually according to government environmental assessments, creating increasing attention toward plastic waste management and recycling practices. Manufacturers are required to improve sustainability initiatives, recycling capabilities, and environmentally responsible production processes. The country’s electricity consumption reached approximately 118 terawatt-hours in 2023, according to International Energy Agency data, reflecting expanding infrastructure needs that also create competition among different conduit and utility piping materials. While plastic pipes offer advantages such as corrosion resistance and installation efficiency, some large infrastructure projects continue considering traditional materials based on engineering specifications, application requirements, and long-term performance expectations.
Market Opportunities
Water Security Programs and Wastewater Infrastructure Modernization
The Philippines Plastic Pipes and Fittings Market presents significant opportunities from water security initiatives, wastewater treatment expansion, and modernization of sanitation infrastructure. Increasing urbanization and population growth are creating demand for improved water distribution networks, sewer systems, and drainage infrastructure. The Philippines had approximately 76% basic drinking water service coverage in 2022, according to World Health Organization and UNICEF water access indicators, highlighting continued requirements for expanding reliable water infrastructure. Government agencies and utilities are investing in improving water availability, reducing pipeline losses, and expanding wastewater treatment capacity. Plastic pipes, particularly HDPE and PVC systems, are suitable for these applications due to durability, flexibility, and resistance to corrosion in humid tropical environments. Flood management infrastructure also creates opportunities for drainage pipes and stormwater management systems, particularly in Metro Manila and other flood-prone urban areas. The government allocated approximately PHP 255 billion for flood control programs in 2024, supporting drainage improvement and water management projects. These developments create long-term opportunities for plastic pipe manufacturers supplying municipal water, wastewater, drainage, and infrastructure rehabilitation projects.
Agricultural Irrigation Development and Industrial Utility Expansion
The Philippines Plastic Pipes and Fittings Market has growth opportunities through agricultural modernization, irrigation expansion, and industrial utility infrastructure development. Agriculture remains a significant sector of the Philippine economy, contributing approximately 8.6% of GDP in 2023, according to Philippine Statistics Authority data, creating demand for efficient irrigation systems and water distribution solutions. Plastic irrigation pipes, particularly HDPE and PVC systems, are increasingly suitable for agricultural applications due to flexibility, durability, and reduced maintenance requirements. The National Irrigation Administration continues developing and improving irrigation networks to increase agricultural productivity and water efficiency. Industrial development also provides opportunities as manufacturing, food processing, electronics, and logistics facilities expand across economic zones. The Philippines attracted approximately USD 8.9 billion in foreign direct investment inflows in 2023, according to Bangko Sentral ng Pilipinas data, supporting industrial expansion and infrastructure requirements. Industrial facilities require plastic piping systems for water supply, process applications, drainage, and utility networks. Growth in agricultural modernization and industrial investment is expected to support demand for specialized plastic piping solutions across multiple end-use sectors.
Future Outlook
Over the next decade, the Philippines Plastic Pipes and Fittings Market is expected to demonstrate sustained growth driven by urbanization, water infrastructure development, residential construction expansion, and modernization of wastewater networks. Increasing adoption of HDPE and advanced thermoplastic systems will support market expansion. The market is projected to grow at a CAGR of ~X% during 2026-2035, supported by infrastructure investments, utility development, and increasing demand for durable piping solutions.
Major Players
- Neltex Development Company Inc.
- Atlanta Industries Inc.
- Moldex Products Inc.
- Crown Asia Chemicals Corporation
- Emerald Vinyl Corporation
- Supreme Pipes Inc.
- Philippine Resins Industries Inc.
- Wavin
- Aliaxis
- Georg Fischer
- Pipelife
- Sekisui Chemical
- Astral Limited
- Finolex Industries
- REHAU
Key Target Audience
- Plastic Pipe Manufacturers
- Plastic Fittings Manufacturers
- Construction and Infrastructure Development Companies
- Water Utility Companies
- Real Estate Developers
- Investments and Venture Capitalist Firms (Philippine Investment Alliance for Infrastructure, private infrastructure investment funds)
- Government and Regulatory Bodies (Department of Public Works and Highways, Metropolitan Waterworks and Sewerage System, Department of Environment and Natural Resources)
- Industrial Manufacturing Companies
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves developing an ecosystem map covering manufacturers, polymer suppliers, distributors, contractors, utilities, developers, and infrastructure stakeholders operating within the Philippines Plastic Pipes and Fittings Market. Extensive secondary research is conducted through government publications, industry databases, trade information, and company disclosures to identify major market variables.
Step 2: Market Analysis and Construction
This phase focuses on analyzing historical market trends related to plastic pipe production, consumption patterns, material adoption, application demand, and infrastructure requirements. The analysis covers PVC, HDPE, PPR, CPVC, and specialty thermoplastic systems used across construction, water management, agriculture, and industrial sectors.
Step 3: Hypothesis Validation and Expert Consultation
Market assumptions are validated through discussions with manufacturers, distributors, contractors, and industry participants involved in plastic pipe supply and utilization. These consultations provide operational insights regarding demand patterns, procurement behavior, competitive dynamics, and technology adoption.
Step 4: Research Synthesis and Final Output
The final stage integrates primary and secondary research findings to develop a comprehensive market assessment. Data collected through supply-side and demand-side evaluation is analyzed using bottom-up and top-down approaches to validate market trends, competitive positioning, and future opportunities.

- Executive Summary
- Research Methodology (Market Definition and Scope, Philippines Plastic Pipes and Fittings Market Classification, Thermoplastic Pipe Demand Assessment, Plastic Pipe Production Volume Analysis, Plastic Fittings Consumption Mapping, PVC Pipe Demand Assessment, HDPE Pipe Consumption Analysis, PPR Plumbing System Adoption Assessment, CPVC Pipe Demand Evaluation, Municipal Water Supply Infrastructure Pipe Requirement Analysis, Wastewater and Sewerage Pipeline Demand Assessment, Residential Construction Plumbing Demand Assessment, Commercial Building Plumbing Demand Assessment)

- Definition and Scope
- Philippines Plastic Pipes and Fittings Industry Evolution and Development of Thermoplastic Piping Infrastructure
- PVC Pressure Pipes, PVC Drainage Pipes, HDPE Pipes, MDPE Pipes, PPR Pipes, CPVC Pipes, PE Pipes, Corrugated Pipes, Plastic Irrigation Systems, Plastic Utility Piping Systems
- Philippines Plastic Pipes and Fittings Value Chain Analysis
- Philippines Plastic Pipes and Fittings Supply Chain Analysis
- Polymer Resin Supplier, Compound Manufacturer, Pipe Extruder, Fittings Manufacturer, Distributor, Contractor, Construction Developer, Water Utility End User
- Plastic Pipe Integration Across Municipal Water Networks, Residential Plumbing Systems, Commercial Buildings, Industrial Facilities, Agricultural Irrigation Networks, Flood Management Systems, Electrical Conduit Networks, Telecommunication Infrastructure

- Growth Drivers (Water Infrastructure Development, Urbanization Expansion, Residential Construction Growth, Government Infrastructure Programs, Wastewater Management Development, Flood Control Infrastructure Investment, Agricultural Irrigation Modernization, Industrial Facility Expansion, Replacement of Traditional Metal Pipes, Increasing Demand for Durable Plumbing Systems)
- Market Challenges (Dependence on Imported Polymer Raw Materials, PVC and Polyethylene Resin Price Volatility, Competition Among Domestic Pipe Manufacturers, Infrastructure Project Delays, Quality Standard Compliance Requirements, Limited Recycling Infrastructure, Competition from Metal and Concrete Piping Systems, Regional Distribution Challenges)
- Market Opportunities (Water Supply Network Modernization, Wastewater Treatment Expansion, Flood Management Infrastructure Development, Large Diameter HDPE Pipeline Adoption, Sustainable Plastic Pipe Solutions, Smart Water Infrastructure Development, Industrial Manufacturing Expansion, Agricultural Irrigation Modernization, Recycled Polymer Integration, Rural Water Supply Development)
- Market Trends (HDPE Pipeline Adoption, PPR Plumbing System Growth, Large Diameter Plastic Pipe Usage, Trenchless Pipe Installation, Advanced Fusion Technology Adoption, Sustainable Pipe Manufacturing, Prefabricated Plumbing Systems, Digital Construction Integration, Smart Water Management Systems, Plastic Pipe Recycling Initiatives)
- Regulatory and Standards Landscape (Philippine National Standards for Plastic Pipes, Department of Public Works and Highways Infrastructure Standards, National Water Resources Board Requirements, Philippine Building Code Requirements, Department of Environment and Natural Resources Regulations, Water Utility Standards, Product Certification Requirements, Environmental Compliance Standards)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Competition Ecosystem

- By Market Value (2020-2025)
- By Plastic Pipe Consumption Volume (2020-2025)
- By Plastic Fittings Consumption Volume (2020-2025)
- By PVC Pipe Consumption Volume (2020-2025)
- By HDPE Pipe Consumption Volume (2020-2025)
- By PPR Pipe Consumption Volume (2020-2025)
- By CPVC Pipe Consumption Volume (2020-2025)

- By Material Type (In Value %)
PVC Pipes and Fittings
HDPE Pipes and Fittings
PPR Pipes and Fittings
CPVC Pipes and Fittings
MDPE Pipes and Fittings
PE Pipes and Fittings
Polypropylene Pipes and Fittings
Composite Plastic Pipes
Specialty Thermoplastic Pipes - By Product Type (In Value %)
Pressure Pipes
Non-Pressure Pipes
Water Supply Pipes
Drainage and Sewer Pipes
Corrugated Pipes
Solid Wall Pipes
Irrigation Pipes
Electrical Conduit Pipes
Telecommunication Duct Pipes
Injection Molded Fittings
Fabricated Fittings
Electrofusion Fittings
Mechanical Connection Fittings - By Application Type (In Value %)
Municipal Water Distribution Systems
Wastewater and Sewer Systems
Residential Plumbing Systems
Commercial Plumbing Systems
Industrial Process Piping Systems
Agricultural Irrigation Systems
Flood Control and Drainage Systems
Electrical Conduit Systems
Telecommunication and Fiber Optic Duct Systems
Fire Protection Systems
Aquaculture Water Systems
Mining and Industrial Utility Systems - By End-Use Industry (In Value %)
Water Utilities
Wastewater Utilities
Residential Construction
Commercial Construction
Industrial Manufacturing Facilities
Agriculture Sector
Aquaculture Industry
Food and Beverage Processing Facilities
Mining Industry
Energy and Utility Projects
Telecommunication Infrastructure
Government Infrastructure Projects - By Demand Type (In Value %)
New Infrastructure Installation
Water Supply Network Expansion
Wastewater Infrastructure Development
Residential Construction Demand
Commercial Construction Projects
Industrial Expansion Projects
Replacement and Rehabilitation Projects
Repair and Maintenance Demand
Agricultural Irrigation Development - By Region (In Value %)
National Capital Region
Metro Manila
Central Luzon Region
Calabarzon Region
Central Visayas Region
Western Visayas Region
Northern Mindanao Region
Davao Region

- Market Share of Major Players (By Philippines Revenue, Plastic Pipe Sales Volume, Plastic Fittings Sales Volume, PVC Pipe Sales Volume, HDPE Pipe Sales Volume, PPR Pipe Sales Volume, Water Infrastructure Exposure, Residential Construction Exposure, Manufacturing Footprint, Distribution Network Coverage, Product Portfolio Breadth, Certification Coverage)
- Cross Comparison Parameters (Philippines Plastic Pipe and Fittings Revenue, Material Portfolio Breadth Across PVC-HDPE-PPR-CPVC, Pipe Extrusion and Fittings Manufacturing Capacity, Large Diameter Pipe Production Capability, Water Infrastructure Project Exposure, Agricultural and Irrigation Application Capability, Distribution Network and Contractor Reach, Philippine National Standards and International Certification Coverage)
- SWOT Analysis of Major Players
- Competitive Positioning Matrix
- Detailed Profiles of Major Companies
Neltex Development Company Inc.
Atlanta Industries Inc.
Moldex Products Inc.
Crown Asia Chemicals Corporation
Emerald Vinyl Corporation
Aqua-Flo Supply Corporation
Supreme Pipes Inc.
Philippine Resins Industries Inc.
Wavin
Aliaxis
Georg Fischer
Pipelife
Sekisui Chemical
Astral Limited
REHAU

- Water Utility Plastic Pipe Procurement Assessment
- Wastewater Utility Sewer Pipe Replacement Requirement Analysis
- Residential Developer Plumbing System Material Selection Assessment
- Commercial Building Plumbing Specification Analysis
- Industrial Facility Process Piping Requirement Assessment
- Agricultural Irrigation Pipe Procurement Analysis
- Flood Control Contractor Pipeline Requirement Assessment
- Construction Contractor Material Preference Assessment
- Electrical Contractor Conduit Procurement Assessment
- Telecommunication Fiber Duct Installation Requirement Analysis
- Government Infrastructure Project Procurement Assessment
- Architect and Engineering Consultant Plastic Pipe Specification Analysis
- Distributor Inventory and Procurement Assessment

- By Market Value (2026-2035)
- By Plastic Pipe Consumption Volume (2026-2035)
- By Plastic Fittings Consumption Volume (2026-2035)
- By PVC Pipe Consumption Volume (2026-2035)
- By HDPE Pipe Consumption Volume (2026-2035)
- By PPR Pipe Consumption Volume (2026-2035)
- By CPVC Pipe Consumption Volume (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
