
 Download PDF
Market Overview
The Singapore coated glass market is valued at approximately USD ~ billion, based on historical market assessment, supported by demand from commercial buildings, residential developments, transport infrastructure, and sustainable construction projects. The market growth is influenced by Singapore’s focus on energy-efficient buildings, with the Building and Construction Authority (BCA) reporting continued expansion of green-certified buildings under the Green Mark scheme. The construction sector contributed approximately SGD ~ billion to Singapore’s economy, supporting demand for advanced glazing solutions such as low-E glass and solar control coated glass.
The Singapore coated glass market is concentrated in urban districts including the Central Region, Downtown Core, Marina Bay, and Jurong due to high-density commercial developments, premium office towers, residential projects, and infrastructure expansion. Singapore’s urban development strategy emphasizes sustainable buildings and efficient land utilization, increasing demand for high-performance façade materials. The Building and Construction Authority reported continued development of commercial and residential projects, while major redevelopment zones require advanced glazing technologies for thermal performance, daylight optimization, and architectural design requirements.
Market Segmentation
By Coating Technology Type
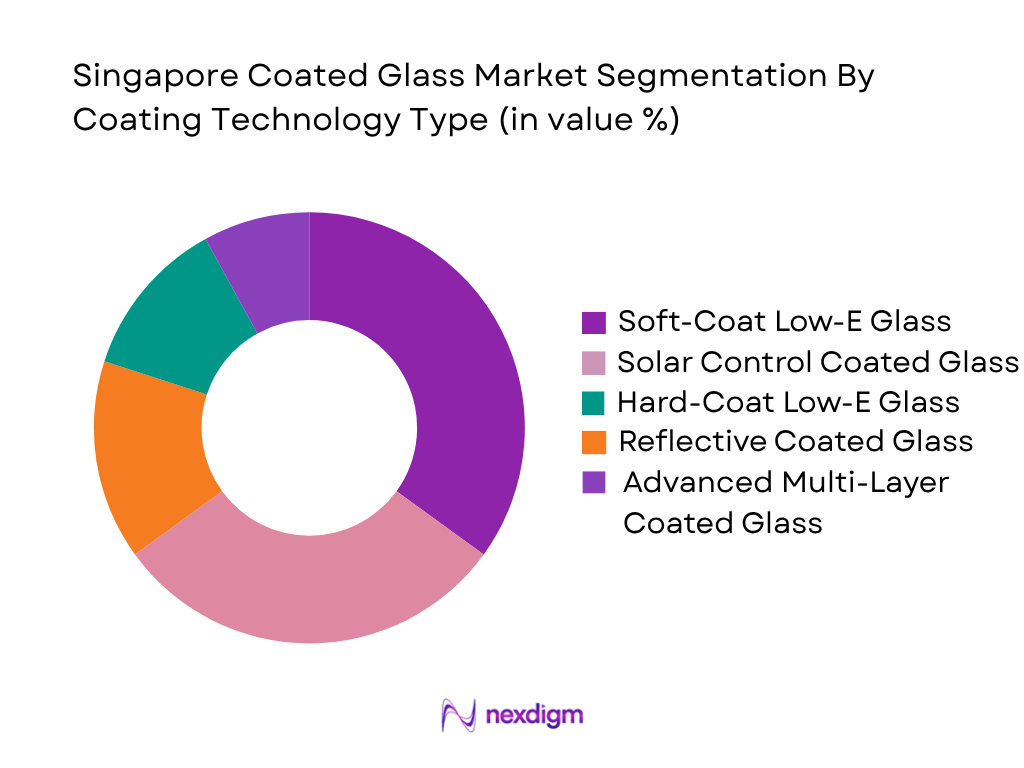
The Singapore coated glass market is segmented by coating technology type into soft-coat low-E glass, hard-coat low-E glass, solar control coated glass, reflective coated glass, and advanced multi-layer coated glass. Soft-coat low-E glass holds a dominant position in the Singapore coated glass market due to its superior thermal insulation properties and suitability for high-performance building envelopes. The technology is widely adopted in commercial towers, premium residential developments, and green-certified buildings where reducing cooling demand is a major requirement. Singapore’s tropical climate creates strong demand for glazing solutions that minimize solar heat gain while maintaining natural daylight penetration. Increasing adoption of sustainable construction standards and energy-efficient building designs further supports the usage of low-E coated glass across new developments and refurbishment projects.
By Application System
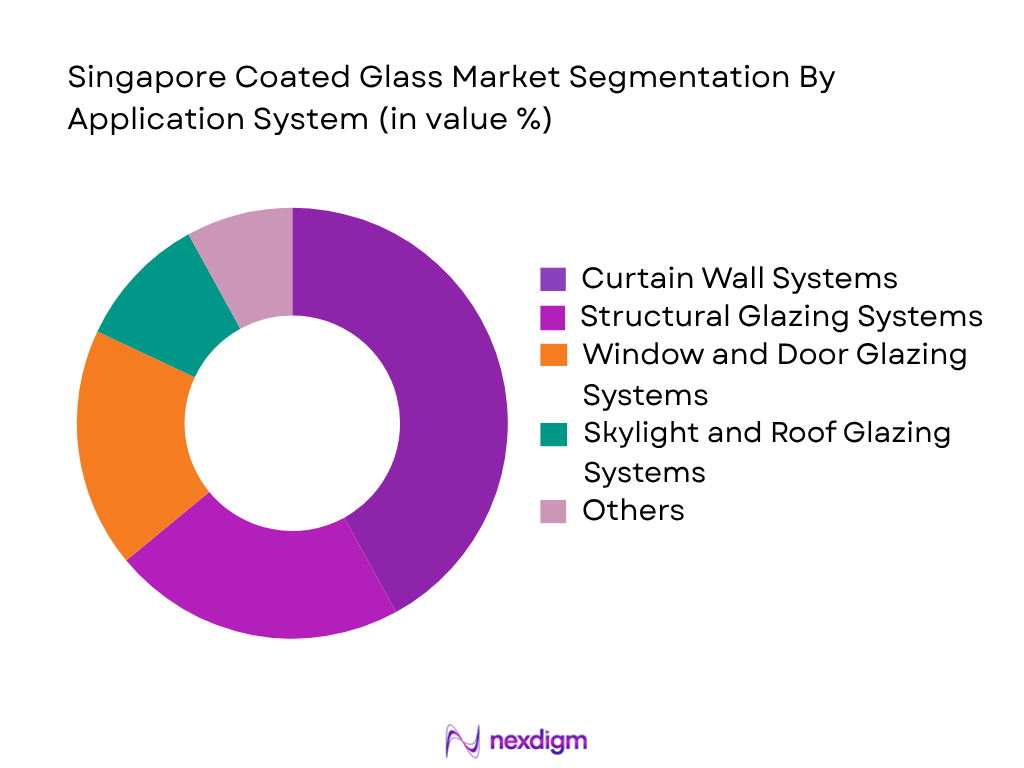
The Singapore coated glass market is segmented by application system into curtain wall systems, structural glazing systems, window and door glazing systems, skylight systems, and architectural interior applications. Curtain wall systems account for the dominant share of the Singapore coated glass market due to extensive usage in office buildings, commercial complexes, hotels, and high-rise residential developments. Singapore’s skyline consists of numerous glass-intensive buildings requiring advanced façade solutions that provide thermal efficiency, aesthetic appeal, and durability. Large-scale projects in business districts and mixed-use developments increasingly utilize coated glass to meet sustainability requirements and improve building performance. The growth of green buildings and redevelopment activities continues to increase demand for curtain wall-integrated coated glass solutions.
Competitive Landscape
The Singapore coated glass market includes global glass manufacturers, regional suppliers, and local glass processors competing through advanced coating technologies, architectural glass portfolios, façade project experience, and supply chain capabilities. Leading companies focus on low-E glass, solar control solutions, sustainable glazing technologies, and customized façade applications to serve Singapore’s commercial, residential, and infrastructure construction sectors.
| Company | Establishment Year | Headquarters | Low-E Glass Portfolio | Solar Control Glass Capability | Singapore Project Presence | Coating Technology | Distribution Network | Façade Glass Solutions |
| Saint-Gobain | 1665 | France | ~ | ~ | ~ | ~ | ~ | ~ |
| AGC Inc. | 1907 | Japan | ~ | ~ | ~ | ~ | ~ | ~ |
| Guardian Industries | 1932 | USA | ~ | ~ | ~ | ~ | ~ | ~ |
| NSG Group | 1918 | Japan | ~ | ~ | ~ | ~ | ~ | ~ |
| Şişecam | 1935 | Türkiye | ~ | ~ | ~ | ~ | ~ | ~ |
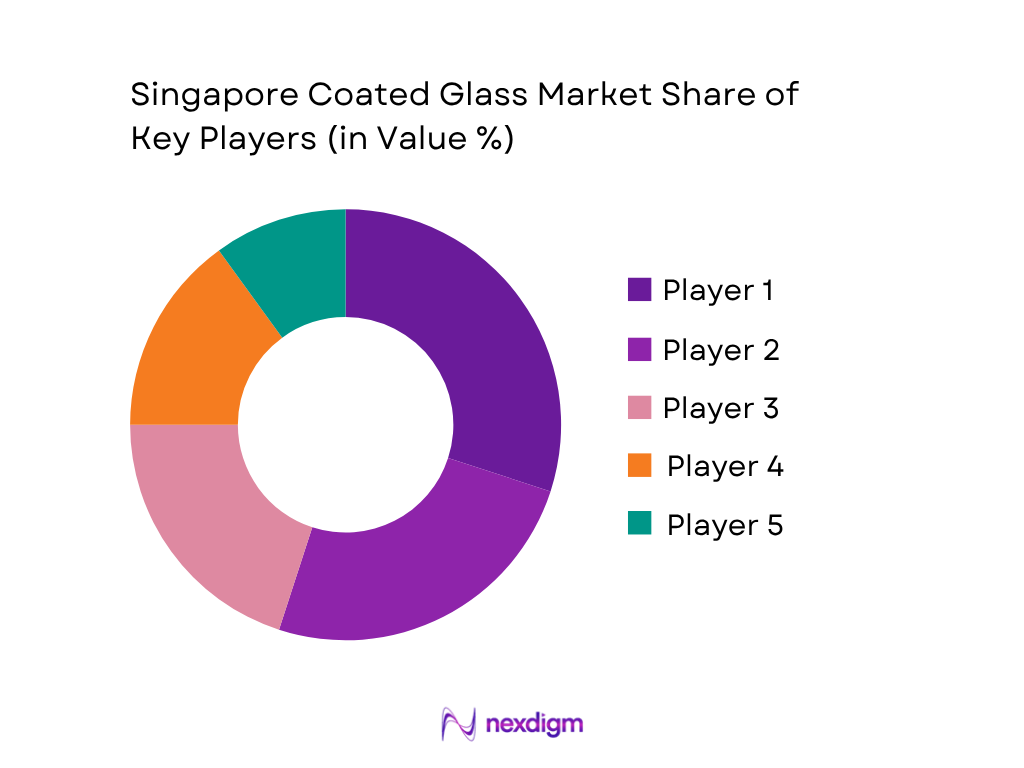
Singapore Coated Glass Market Analysis
Growth Drivers
Expansion of Sustainable Construction and Green Building Infrastructure
The Singapore coated glass market is supported by the country’s focus on sustainable urban development, energy-efficient buildings, and green-certified infrastructure. Singapore’s construction ecosystem continues to generate demand for low-E glass, solar control glass, and high-performance façade glazing due to strict building efficiency requirements. According to the Building and Construction Authority (BCA), Singapore had more than 2,500 Green Mark-certified buildings covering over 100 million square metres of floor area, reflecting strong adoption of sustainable building practices. The Urban Redevelopment Authority (URA) reported that Singapore’s total island-wide population reached approximately 6.04 million, increasing long-term demand for residential, commercial, and mixed-use developments. The Ministry of Trade and Industry reported Singapore’s GDP at approximately SGD 673 billion at current prices, indicating continued economic activity supporting infrastructure investment. Increasing redevelopment of commercial districts such as Marina Bay, Jurong Lake District, and the Central Business District is driving demand for coated glass solutions that enhance thermal insulation, reduce solar heat gain, and improve building energy performance. The adoption of advanced glazing materials aligns with Singapore’s Green Plan 2030 and building decarbonization objectives.
Growth of High-Performance Façade Systems in Commercial and High-Density Buildings
The Singapore coated glass market benefits from rising demand for advanced façade systems in office towers, residential developments, hospitality projects, and technology infrastructure facilities. Singapore’s land constraints and high urban density encourage vertical development, increasing the requirement for efficient building envelope materials. According to the Urban Redevelopment Authority, Singapore recorded approximately 728,000 private residential units and more than 1.4 million total housing units, demonstrating continued construction activity requiring durable glazing solutions. The Building and Construction Authority reported that the construction sector maintained strong activity with projected construction demand reaching approximately SGD 47 billion, supporting demand for architectural glass products. Singapore’s tropical climate, with annual temperatures frequently ranging between 25°C and 31°C according to the National Environment Agency, increases the importance of solar control and thermal insulation glazing. Coated glass technologies help reduce cooling requirements in commercial buildings while maintaining daylight availability. The expansion of premium office developments, data centres, and smart buildings further supports adoption of high-performance coated glass systems.
Market Challenges
Dependence on Imported Coated Glass and Limited Domestic Manufacturing Capability
The Singapore coated glass market faces challenges due to limited domestic production of advanced coated glass products and dependence on international suppliers for specialized glazing technologies. Singapore has a strong glass processing and fabrication ecosystem; however, advanced coating technologies such as magnetron sputtering and multi-layer low-E coating production remain concentrated among global manufacturers. According to Singapore Department of Statistics trade data, Singapore recorded merchandise trade exceeding SGD 1 trillion, highlighting the country’s reliance on international supply chains across industrial sectors. The Ministry of Trade and Industry reported Singapore’s manufacturing sector contributed approximately 20% of GDP, but specialized architectural glass production represents a smaller industrial segment compared with electronics, chemicals, and precision engineering. Dependence on imported coated glass exposes suppliers and developers to international logistics disruptions, currency fluctuations, and external supply constraints. Large construction projects requiring customized coated glass specifications often rely on global manufacturers for product availability, technical approvals, and performance certifications. This creates challenges related to procurement timelines, supply chain flexibility, and localization of advanced glass coating capabilities.
Complex Technical Requirements and High Performance Standards for Façade Applications
The Singapore coated glass market experiences challenges related to strict technical specifications, façade engineering requirements, and installation standards required for high-performance glazing systems. Coated glass performance depends on accurate specification, fabrication quality, orientation, installation methods, and integration with aluminium façade systems. The Building and Construction Authority implements detailed requirements under Singapore’s building regulatory framework, requiring construction materials and systems to meet safety, durability, and energy efficiency standards. Singapore’s construction sector recorded approximately SGD 33 billion in construction demand in recent assessments, reflecting the scale of projects where façade performance requirements are critical. The National Environment Agency highlights Singapore’s consistent warm and humid climate conditions, creating continuous demand for cooling systems and increasing the importance of effective solar control glazing. Advanced coated glass installations require coordination among architects, developers, façade contractors, and glass processors, increasing project complexity. Improper selection or installation may reduce expected thermal performance and affect building energy efficiency outcomes.
Market Opportunities
Increasing Adoption of Green Buildings and Energy-Efficient Building Materials
The Singapore coated glass market presents significant opportunities due to increasing adoption of sustainable construction practices and energy-efficient building materials. Government initiatives focused on reducing building emissions are encouraging developers to incorporate advanced glazing solutions such as low-E glass and solar control coatings. The Building and Construction Authority’s Green Mark certification framework continues to promote energy-efficient building designs, with thousands of buildings already certified under sustainability standards. Singapore’s Green Plan 2030 targets sustainable urban development and improved resource efficiency, creating opportunities for advanced architectural materials. According to the Energy Market Authority, Singapore’s electricity consumption exceeded 55 TWh, highlighting the importance of improving energy efficiency across commercial and residential buildings. Coated glass solutions support reduced cooling demand by improving thermal insulation and controlling solar radiation. Increasing redevelopment activities in commercial districts and construction of environmentally certified buildings create opportunities for suppliers offering advanced glazing technologies. Future demand is expected to benefit from requirements for sustainable façades, smart buildings, and energy-efficient infrastructure.
Expansion of Smart Buildings and Advanced Architectural Glass Applications
The Singapore coated glass market has growth opportunities from increasing investment in smart buildings, premium developments, and technology-driven infrastructure projects. Singapore’s position as a regional business and technology hub is increasing demand for advanced commercial buildings requiring efficient building envelope solutions. According to the Infocomm Media Development Authority, Singapore continues to expand its digital infrastructure ecosystem, supporting development of technology facilities and data centres requiring optimized building performance. The Economic Development Board reported continued investment activity in advanced manufacturing, technology, and services sectors, supporting construction of modern industrial and commercial facilities. High-performance coated glass enables improved daylight management, thermal comfort, and energy efficiency in these buildings. Growing adoption of intelligent building management systems creates opportunities for integration of smart glazing technologies, including dynamic glass and advanced façade solutions. The combination of urban redevelopment, sustainability requirements, and technology-driven construction is expected to increase demand for customized coated glass applications across commercial towers, hospitality developments, and next-generation infrastructure projects.
Future Outlook
Over the next decade, the Singapore coated glass market is expected to demonstrate steady growth driven by sustainable building initiatives, increasing adoption of energy-efficient glazing systems, and continuous redevelopment of commercial and residential infrastructure. Growth will be supported by green building requirements, advanced façade technologies, and rising demand for low-energy consumption buildings. The market is expected to witness increased adoption of low-E coatings, solar control glass, and smart glazing solutions. The Singapore coated glass market is projected to grow at a CAGR of approximately ~% during 2026-2035.
Major Players
- Saint-Gobain
- AGC Inc.
- Guardian Industries
- NSG Group
- Şişecam
- Vitro Architectural Glass
- Xinyi Glass Holdings
- Kibing Group
- Singapore Safety Glass
- GlassPoint Singapore
- GSC Glass
- M Glass
- Koon Seng Glass
- Hup Hing Glass
- Taiwan Glass
Key Target Audience
- Real Estate Developers and Property Development Companies
- Architectural Glass Fabricators and Processors
- Façade Engineering and Building Envelope Companies
- Aluminium Façade System Manufacturers
- Investments and Venture Capitalist Firms (Real Estate Investment Funds, Infrastructure Investment Funds, Private Equity Firms)
- Government and Regulatory Bodies (Building and Construction Authority, Urban Redevelopment Authority, Singapore Green Building Council)
- Commercial Building Owners and Facility Management Companies
- Glass Manufacturing and Construction Material Companies
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves developing a comprehensive ecosystem map covering coated glass manufacturers, processors, façade contractors, developers, regulatory authorities, and end users operating in the Singapore coated glass market. This stage includes extensive secondary research to identify key market variables influencing demand, supply, technology adoption, and application growth.
Step 2: Market Analysis and Construction
In this phase, historical information related to coated glass consumption, product categories, application systems, and construction activities is analyzed. The assessment includes evaluation of façade demand, import dependency, processing capabilities, sustainability requirements, and architectural glazing trends to construct the market framework.
Step 3: Hypothesis Validation and Expert Consultation
Market assumptions are validated through primary discussions with industry participants including glass manufacturers, façade contractors, processors, developers, and procurement specialists. These consultations provide operational insights regarding product selection, technology adoption, competitive positioning, and future market opportunities.
Step 4: Research Synthesis and Final Output
The final stage integrates qualitative and quantitative findings from primary and secondary research sources. Information collected from manufacturers, suppliers, and end users is evaluated to validate segmentation, competitive analysis, market trends, and future growth prospects of the Singapore coated glass market.

- Executive Summary
- Research Methodology (Market Definition and Scope, Singapore Coated Glass Market Classification, Commercial Building Façade Glass Demand Assessment, Green Building Energy Efficiency Glazing Assessment, High-Rise Residential Coated Glass Consumption Mapping, Low-E Glass Adoption Assessment, Solar Control Glass Requirement Analysis, Curtain Wall and Structural Glazing Demand Assessment, Smart Building Glass Integration Assessment, Domestic Glass Processing and Fabrication Capacity Assessment, Coated Glass Import Dependency Analysis, Magnetron Sputtering, Pyrolytic Coating, Low-E, Solar Control and Advanced Architectural Glass Technology Assessment)

- Definition and Scope
- Singapore Coated Glass Industry Evolution
- Coated Glass Product Categories
- Singapore Coated Glass Value Chain Analysis
- Singapore Coated Glass Supply Chain Analysis
- Coated Glass Application Landscape
- Energy Efficient Building Glass Adoption
- Green Building and Sustainable Glazing Development
- Façade and Architectural Glass Integration

- Growth Drivers (Green Building Development, Building and Construction Authority Sustainable Construction Initiatives, Commercial Building Redevelopment, High-Rise Residential Development, Energy Efficient Building Envelope Requirements, Rising Demand for Solar Control Glass, Data Centre Construction Expansion, Premium Architectural Glass Applications, Urban Redevelopment Projects)
- Market Challenges (High Dependence on Imported Coated Glass Products, Limited Domestic Coating Manufacturing Capacity, High Cost of Advanced Low-E Glass Solutions, Complex Façade Engineering Requirements, Limited Availability of Specialized Glass Processing Infrastructure, Long Project Approval Cycles, Dependence on International Supply Chains)
- Market Opportunities (Green Mark Certified Building Expansion, Building Retrofit and Façade Upgradation Projects, Smart Glass Integration, Energy Efficient Commercial Buildings, Data Centre Cooling Optimization, Advanced Low-E Glass Adoption, Sustainable Construction Material Demand, High Performance Architectural Glass Applications)
- Market Trends (Low-E Glass Adoption, Solar Control Glazing Growth, Sustainable Building Materials, Green Mark Building Compliance, Smart Glass Integration, Digital Façade Design, Large Format Architectural Glass Usage, Triple Silver Coating Adoption, High Performance Curtain Wall Systems, Energy Efficient Retrofit Solutions, Building Information Modelling Integration)
- Regulatory and Standards Landscape (Building and Construction Authority Green Mark Requirements, Singapore Building Control Regulations, Energy Conservation Standards, Sustainable Construction Guidelines, Building Envelope Performance Requirements, Safety Glass Standards, Environmental Sustainability Requirements)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Competition Ecosystem

- By Market Value (2020-2025)
- By Coated Glass Consumption Volume (2020-2025)
- By Low-E Glass Consumption Volume (2020-2025)
- By Solar Control Glass Consumption Volume (2020-2025)
- By Curtain Wall and Façade Glass Consumption Volume (2020-2025)
- By Insulating Glass Unit (IGU) Coated Glass Consumption Volume (2020-2025)
- By Commercial Building Coated Glass Consumption Volume (2020-2025)
- By Residential Building Coated Glass Consumption Volume (2020-2025)
- By Hospitality and Retail Project Coated Glass Consumption Volume (2020-2025)
- By Coated Glass Import Value (2020-2025)
- By Average Selling Price (2020-2025)

- By Coating Technology Type (In Value %)
Magnetron Sputtered Coated Glass
Soft-Coat Low-E Glass
Hard-Coat Low-E Glass
Solar Control Coated Glass
Reflective Coated Glass
Pyrolytic Coated Glass
Double Silver Low-E Glass
Triple Silver Low-E Glass
Anti-Reflective Coated Glass
Self-Cleaning Coated Glass - By Glass Product Type (In Value %)
Clear Float Glass
Tinted Float Glass
Low Iron Glass
Tempered Coated Glass
Heat Strengthened Coated Glass
Laminated Coated Glass
Insulating Glass Units (IGU)
Double Glazed Units
Triple Glazed Units
Vacuum Insulated Glass - By Application System (In Value %)
Curtain Wall Systems
Unitized Façade Systems
Structural Glazing Systems
Window and Door Glazing Systems
Skylight and Roof Glazing Systems
Atrium and Canopy Glazing
Interior Architectural Glazing
Energy Efficient Building Envelope Systems
Smart Building Glazing Systems - By End-Use Industry (In Value %)
Commercial Office Buildings
Residential Condominiums and Housing Projects
Hospitality and Tourism Infrastructure
Retail and Shopping Centres
Healthcare Facilities
Educational Institutions
Airports and Transportation Infrastructure
Industrial and Manufacturing Facilities
Government Buildings
Data Centres and Technology Infrastructure - By Region (In Value %)
Central Region
East Region
West Region
North Region
North-East Region

- Market Share of Major Players (By Singapore Revenue, Coated Glass Sales Volume, Low-E Glass Sales Volume, Solar Control Glass Sales Volume, Façade Project Exposure, End-Use Industry, Singapore Processing and Fabrication Footprint, Technical Support and Distribution Coverage)
- Cross Comparison Parameters (Singapore Coated Glass Revenue, Low-E and Solar Control Glass Portfolio Breadth, Magnetron Sputtering and Coating Technology Capability, High-Rise Building and Façade Project Exposure, Singapore Glass Processing and Fabrication Capability, Large Format Architectural Glass Availability, Green Building Certification Support Capability, Singapore Distribution Network and Technical Service Footprint)
- SWOT Analysis of Major Players
- Competitive Positioning Matrix
- Coated Glass Product and Technology Portfolio Benchmarking
- Detailed Profiles of Major Companies
Saint-Gobain
AGC Inc.
Guardian Industries
NSG Group
Şişecam
Vitro Architectural Glass
Xinyi Glass Holdings
Kibing Group
Singapore Safety Glass
GlassPoint Singapore
GSC Glass
M Glass
Koon Seng Glass
Hup Hing Glass
Taiwan Glass

- Commercial Office Building Coated Glass Procurement Assessment
- Residential Condominium Developer Glazing Requirement Analysis
- Hospitality Project Façade Glass Specification Assessment
- Retail Mall Architectural Glass Procurement Analysis
- Data Centre Cooling Efficiency Glass Requirement Assessment
- Building and Construction Authority Sustainable Building Material Assessment
- Architect and Façade Consultant Glass Specification Analysis
- Aluminium Façade Contractor Coated Glass Procurement Assessment
- Government Infrastructure Sustainable Glass Procurement Analysis
- Industrial Building Energy Efficient Glazing Requirement Assessment

- By Market Value (2026-2035)
- By Coated Glass Consumption Volume (2026-2035)
- By Low-E Glass Consumption Volume (2026-2035)
- By Solar Control Glass Consumption Volume (2026-2035)
- By Curtain Wall and Façade Glass Consumption Volume (2026-2035)
- By Insulating Glass Unit (IGU) Coated Glass Consumption Volume (2026-2035)
- By Commercial Building Coated Glass Consumption Volume (2026-2035)
- By Residential Building Coated Glass Consumption Volume (2026-2035)
- By Hospitality and Retail Project Coated Glass Consumption Volume (2026-2035)
- By Coated Glass Import Value (2026-2035)
- By Average Selling Price (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
