
 Download PDF
Market Overview
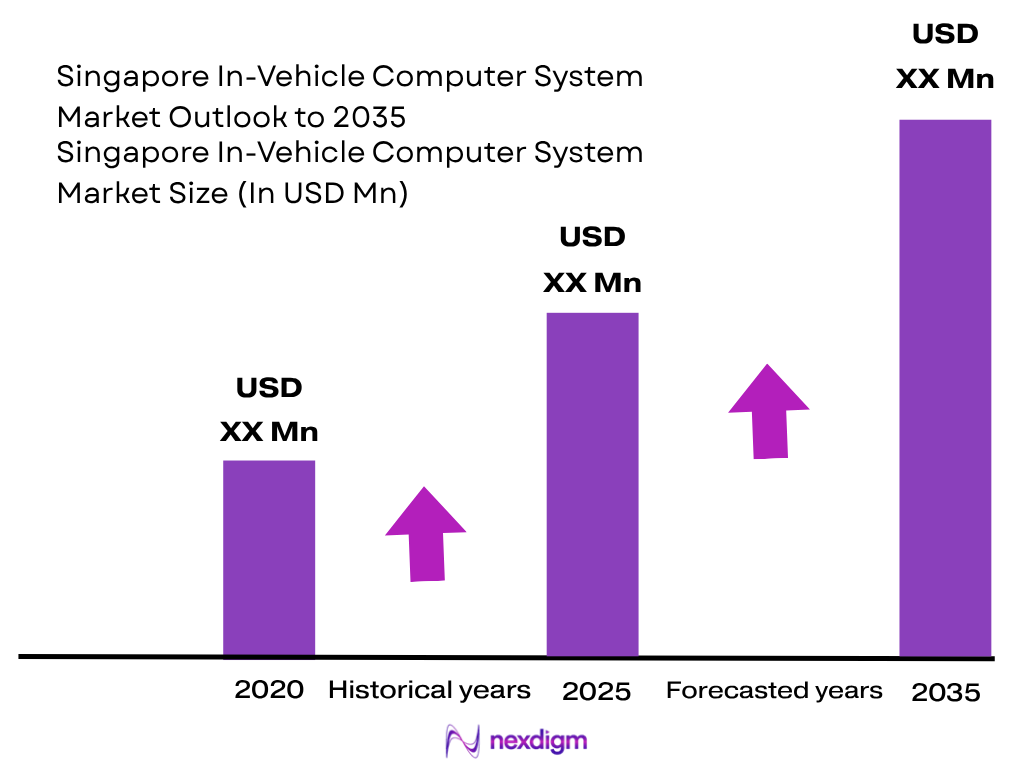
The Singapore In-Vehicle Computer System Market is valued at approximately USD ~ million, driven by the country’s transition toward connected mobility, electric vehicles, autonomous transportation systems, and intelligent vehicle infrastructure. The market ecosystem is supported by Singapore’s advanced automotive technology environment, where in-vehicle computers enable infotainment, vehicle diagnostics, safety systems, telematics, and autonomous driving functions. Singapore registered 80,000+ new vehicle registrations in 2024, according to the Land Transport Authority, creating continued demand for advanced automotive electronics. The country’s Smart Nation initiatives and intelligent transport infrastructure are accelerating adoption of vehicle computing technologies.
The Singapore In-Vehicle Computer System Market is concentrated around Singapore’s central technology and business districts due to the country’s compact geography, advanced digital infrastructure, and strong automotive technology ecosystem. Singapore serves as a regional hub for automotive software development, mobility innovation, semiconductor activities, and intelligent transportation solutions across Southeast Asia. Areas including one-north, Jurong Innovation District, and the Central Region host technology companies, research facilities, and mobility solution providers supporting vehicle computing development. Singapore’s position as a smart city with extensive connected infrastructure enables faster deployment of advanced vehicle technologies compared with traditional automotive markets.
Market Segmentation
By Vehicle Type
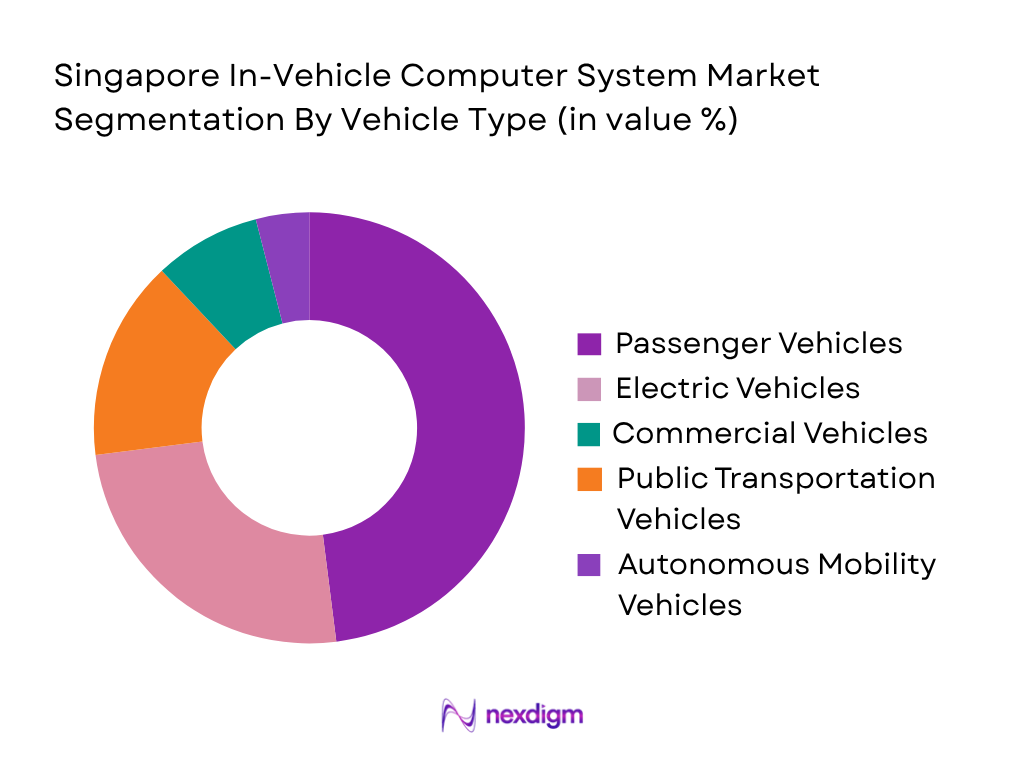
The Singapore In-Vehicle Computer System Market is segmented by vehicle type into passenger vehicles, electric vehicles, commercial vehicles, public transportation vehicles, and autonomous mobility vehicles. Passenger vehicles represent the dominant segment due to Singapore’s vehicle ownership structure, increasing preference for premium vehicles, and growing integration of digital cockpit systems, connectivity platforms, and advanced driver assistance features. The country’s automotive market has a strong presence of imported passenger vehicles equipped with advanced electronic architectures, enabling higher adoption of centralized computing systems and connected vehicle platforms. Electric vehicles are also gaining importance as Singapore promotes cleaner mobility solutions and expands charging infrastructure. Commercial and public transport vehicles contribute demand through fleet management, telematics, and intelligent transportation applications.
By Application Type
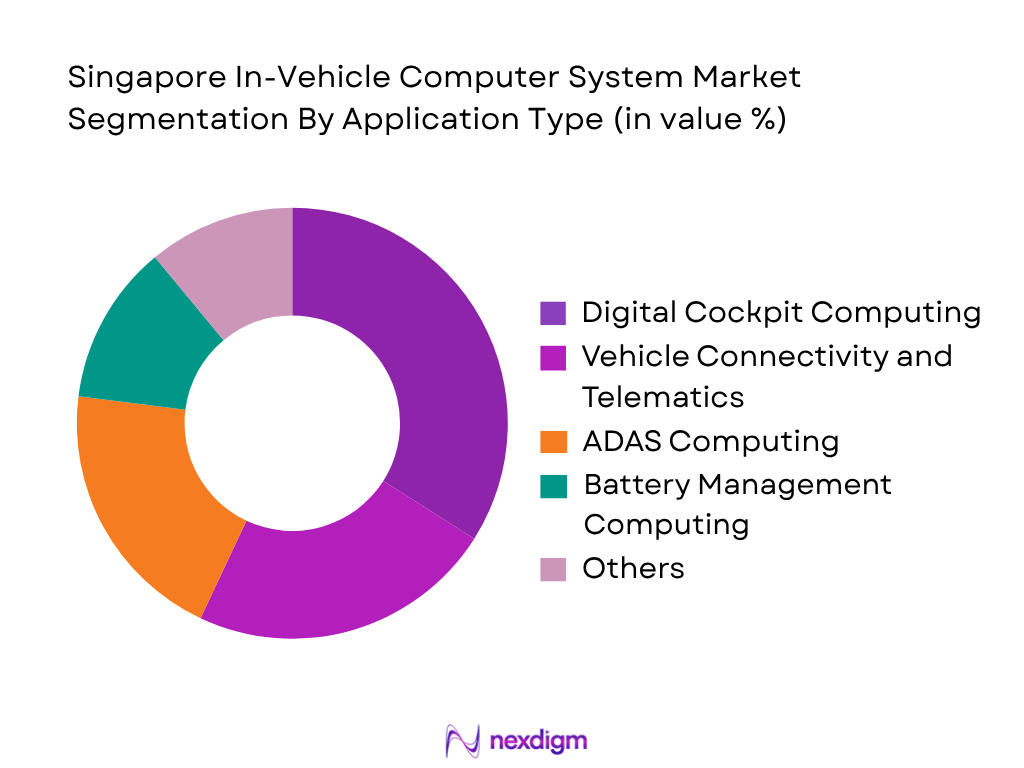
The Singapore In-Vehicle Computer System Market is segmented by application type into digital cockpit computing, ADAS computing, vehicle connectivity and telematics processing, battery management computing, autonomous driving computing, and fleet analytics processing. Digital cockpit computing holds the leading position due to increasing demand for integrated infotainment systems, navigation solutions, smartphone connectivity, and personalized in-car experiences. Singapore’s technology-focused consumer base and advanced telecommunications infrastructure support adoption of connected vehicle features. ADAS computing is gaining momentum due to increasing focus on road safety and autonomous mobility testing initiatives. Vehicle connectivity and telematics applications are widely adopted in commercial fleets and mobility services for monitoring, optimization, and real-time vehicle data management.
Competitive Landscape
The Singapore In-Vehicle Computer System Market is characterized by the presence of global automotive technology providers, semiconductor companies, and mobility solution developers. The market is influenced by international companies such as NVIDIA, Qualcomm, Bosch, Continental, and HARMAN, which provide vehicle computing platforms, processors, embedded software, digital cockpit solutions, and connected mobility technologies. Singapore’s role as a regional technology hub attracts global automotive technology companies seeking access to Southeast Asian mobility markets. Competition is primarily driven by computing performance, software integration capabilities, cybersecurity solutions, and partnerships with automotive manufacturers and mobility operators.
| Company | Establishment Year | Headquarters | Key Product Portfolio | Automotive Computing Capability | Major Application Area | Technology Focus | Singapore Market Presence | Strategic Advantage |
| NVIDIA | 1993 | Santa Clara, USA | ~ | ~ | ~ | ~ | ~ | ~ |
| Qualcomm | 1985 | San Diego, USA | ~ | ~ | ~ | ~ | ~ | ~ |
| Robert Bosch GmbH | 1886 | Gerlingen, Germany | ~ | ~ | ~ | ~ | ~ | ~ |
| Continental AG | 1871 | Hanover, Germany | ~ | ~ | ~ | ~ | ~ | ~ |
| HARMAN International | 1980 | Stamford, USA | ~ | ~ | ~ | ~ | ~ | ~ |
Singapore In-Vehicle Computer System Market Analysis
Growth Drivers
Expansion of Smart Mobility Infrastructure and Connected Vehicle Ecosystem
The Singapore In-Vehicle Computer System Market is benefiting from the country’s advanced smart mobility infrastructure, high digital connectivity penetration, and government-led intelligent transport development. Singapore’s Land Transport Authority (LTA) continues to expand its Intelligent Transport Systems ecosystem, supporting connected vehicle communication, real-time traffic management, and digital mobility services. The country recorded more than 1 million registered vehicles across categories, creating a technology base for advanced vehicle electronics integration. Singapore’s digital infrastructure remains highly developed, with internet penetration exceeding 90% of the population according to World Bank digital development indicators, supporting connected vehicle platforms requiring continuous data exchange. The country’s transport network includes more than 5,000 kilometres of roads, enabling deployment of intelligent transportation technologies and vehicle connectivity solutions. The National AI Strategy and Smart Nation initiatives are encouraging adoption of artificial intelligence, cloud computing, and data-driven mobility solutions. These developments directly support demand for in-vehicle computers capable of managing vehicle connectivity, infotainment, navigation, telematics, and safety applications. As automotive systems transition from independent electronic control units toward integrated computing architectures, Singapore’s connected mobility environment creates opportunities for advanced processors, automotive software platforms, and centralized vehicle computing solutions.
Increasing Electric Vehicle Adoption and Demand for Advanced Vehicle Computing Systems
The growth of electric mobility in Singapore is increasing demand for advanced in-vehicle computer systems required for battery management, energy optimization, vehicle connectivity, and intelligent control functions. Singapore recorded 26,225 electric vehicles in its vehicle population at the end of 2024, representing a significant increase compared with previous years, according to transport statistics. Electric vehicles accounted for approximately one-third of new car registrations in 2024, demonstrating accelerating adoption of vehicles equipped with advanced electronic architectures. The Land Transport Authority has established a national EV charging expansion roadmap targeting 60,000 charging points across public and private locations, supporting broader electric mobility adoption. Singapore had more than 19,000 charging points installed, creating infrastructure support for connected EV ecosystems. The transition toward electric vehicles increases dependence on computing platforms because EVs require continuous monitoring of battery systems, thermal management, power electronics, charging communication, and vehicle software functions. Government initiatives requiring cleaner-energy vehicle adoption, including the transition toward cleaner vehicle registrations, are encouraging automakers to introduce technologically advanced vehicles with integrated computing capabilities. This environment supports increasing deployment of automotive processors, domain controllers, connectivity modules, and intelligent vehicle operating systems.
Market Challenges
Dependence on Imported Automotive Electronics and Semiconductor Components
The Singapore In-Vehicle Computer System Market faces supply chain challenges due to the country’s dependence on imported automotive semiconductor components, processors, and advanced electronic systems. Singapore is a major global semiconductor manufacturing hub, but automotive-grade semiconductor design and vehicle computing hardware production remain dependent on international supply networks. The electronics industry contributes significantly to Singapore’s manufacturing ecosystem, with electronics accounting for a substantial portion of manufacturing output according to the Singapore Economic Development Board. Automotive computing systems require specialized components including automotive-grade microcontrollers, processors, memory systems, artificial intelligence accelerators, and connectivity chips, which are primarily sourced from global semiconductor suppliers. Singapore’s manufacturing economy recorded total merchandise trade exceeding SGD 1 trillion, reflecting its strong position in global electronics supply chains but also highlighting exposure to international component movements. Supply chain disruptions, geopolitical uncertainties, and semiconductor allocation constraints can affect availability of advanced automotive computing components. As vehicle manufacturers increasingly adopt centralized computing architectures, dependence on imported high-performance chips creates challenges related to supply security, component localization, and technology resilience. Strengthening domestic automotive electronics capabilities remains important for supporting long-term growth of intelligent mobility solutions.
Complexity of Connected Vehicle Software Integration and Cybersecurity Requirements
The Singapore In-Vehicle Computer System Market faces increasing complexity due to the integration of software platforms, connectivity technologies, cybersecurity requirements, and vehicle data management systems. Modern in-vehicle computers support multiple functions including infotainment, navigation, telematics, ADAS, remote diagnostics, and cloud connectivity, requiring advanced software architecture and security frameworks. Singapore recorded more than 5.9 million residents and maintains one of the highest levels of digital adoption globally, creating a highly connected environment where cybersecurity protection is essential for connected mobility systems. The Cyber Security Agency of Singapore has highlighted the importance of strengthening cybersecurity resilience across critical information infrastructure sectors, including transportation-related systems. Connected vehicles generate large volumes of operational data through sensors, communication modules, and cloud platforms, increasing the requirement for secure data transmission and protection mechanisms. Vehicle manufacturers and technology providers must comply with cybersecurity standards while ensuring reliability and safety of automotive software. The transition toward software-defined vehicles also requires specialized expertise in embedded software development, artificial intelligence, vehicle operating systems, and secure communication protocols. These technical requirements increase development complexity and create challenges for companies integrating advanced computing solutions into Singapore’s mobility ecosystem.
Market Opportunities
Growth of Autonomous Mobility Testing and Intelligent Transportation Ecosystem
The expansion of Singapore’s autonomous mobility ecosystem creates opportunities for advanced in-vehicle computer systems supporting perception processing, artificial intelligence, vehicle control, and real-time decision-making. Singapore has established itself as a testing environment for autonomous vehicle technologies through government-supported trials and controlled deployment programmes. The Centre of Excellence for Testing and Research of Autonomous Vehicles at Nanyang Technological University provides dedicated infrastructure for autonomous vehicle evaluation, supporting development of intelligent transportation technologies. Singapore’s road infrastructure exceeds 5,000 kilometres, providing a comprehensive environment for connected and autonomous mobility testing. The government’s Smart Nation initiatives and intelligent transport programmes encourage integration of digital technologies across mobility systems. Autonomous vehicles require high-performance computing platforms capable of processing sensor inputs from cameras, LiDAR, radar, and vehicle communication systems. These requirements create demand for automotive AI processors, high-performance computing units, domain controllers, and advanced software platforms. The increasing focus on autonomous mobility, vehicle automation, and intelligent transportation solutions positions Singapore as an important regional development hub for next-generation in-vehicle computing technologies.
Expansion of Electric Mobility and Automotive Software Development Ecosystem
The development of Singapore’s electric mobility ecosystem and technology sector creates opportunities for growth in automotive software, vehicle computing, and intelligent mobility platforms. Singapore’s EV transition roadmap includes deployment of 60,000 charging points by 2030, supported by government initiatives to accelerate cleaner transportation adoption. The country had more than 19,000 EV charging points available, demonstrating continued infrastructure development supporting electric mobility. Singapore also maintains a strong technology ecosystem, with digital economy activities contributing significantly to national economic development and supporting advanced engineering capabilities. Electric vehicles require sophisticated computing platforms for battery monitoring, charging communication, energy optimization, and connected services, creating demand for advanced in-vehicle computers. The increasing adoption of software-defined vehicle architectures provides opportunities for companies developing automotive middleware, cloud-connected platforms, artificial intelligence solutions, and vehicle data analytics systems. Singapore’s position as a regional technology hub enables collaboration between automotive manufacturers, semiconductor companies, mobility operators, and software developers. This ecosystem supports future development of intelligent vehicle platforms requiring scalable computing architectures and advanced digital capabilities.
Future Outlook
Over the next decade, the Singapore In-Vehicle Computer System Market is expected to witness steady expansion driven by the country’s smart mobility initiatives, increasing electric vehicle adoption, connected transportation infrastructure, and autonomous mobility development. Singapore’s focus on intelligent transport systems and digital infrastructure is encouraging the integration of advanced vehicle computing platforms capable of supporting connectivity, automation, safety, and vehicle data management. The market is projected to grow at a CAGR of approximately ~% during 2026-2035, supported by increasing demand for software-defined vehicles, AI-based automotive processing, and centralized computing architectures. Global adoption of in-vehicle computing platforms is being accelerated by the transition toward connected and autonomous vehicles requiring advanced processing capabilities.
Major Players
- NVIDIA – Automotive AI Computing Platforms, Autonomous
- Driving Computers and Vehicle Intelligence Solutions
- Qualcomm – Snapdragon Automotive Platforms, Vehicle SoCs and Connected Computing Solutions
- Intel – Automotive Computing Platforms and Artificial Intelligence-Based Vehicle Processing Technologies
- Robert Bosch GmbH – Vehicle Computers, Embedded Systems and Automotive Electronics Solutions
- Continental AG – Vehicle Computing Architecture, Cockpit Systems and Software-Defined Vehicle Solutions
- Aptiv – Smart Vehicle Architecture, Automotive Software and Computing Platforms
- Renesas Electronics – Automotive Microcontrollers, System-on-Chip Solutions and Embedded Computing Technologies
- NXP Semiconductors – Automotive Processors, Vehicle Networking and Secure Computing Platforms
- Texas Instruments – Automotive Processors, Embedded Computing and Vehicle Electronics Solutions
- STMicroelectronics – Automotive Semiconductor Components and Vehicle Computing Technologies
- Tata Elxsi – Automotive Software Engineering, Digital Cockpit and Connected Vehicle Solutions
- KPIT Technologies – Automotive Software Platforms and Intelligent Mobility Solutions
- HARMAN International – Connected Vehicle Platforms, Digital Cockpit and Infotainment Computing Solutions
- Denso Corporation – Automotive Electronics, Vehicle Computing and Mobility Technology Solutions
- Mitsubishi Electric – Automotive Electronics, Vehicle Control Systems and Intelligent Mobility Solutions
Key Target Audience
- Automotive Original Equipment Manufacturers (OEMs)
- Automotive Tier-1 Electronics and System Suppliers
- Automotive Semiconductor and Computing Technology Companies
- Electric Vehicle Manufacturers and Mobility Technology Providers
- Investments and Venture Capitalist Firms
- Government and Regulatory Bodies
- Fleet Management and Mobility Service Providers
- Automotive Software and Connected Mobility Solution Providers
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves developing an ecosystem map covering major stakeholders operating within the Singapore In-Vehicle Computer System Market. This process includes extensive secondary research through automotive databases, government transportation publications, technology documentation, and company-level information. The objective is to identify key variables influencing market development, including vehicle computing architecture, connectivity adoption, electric mobility integration, semiconductor dependency, and software platform evolution.
Step 2: Market Analysis and Construction
In this phase, historical and current market indicators related to vehicle registrations, connected mobility adoption, electric vehicle deployment, automotive electronics integration, and intelligent transportation development are analyzed. The assessment evaluates demand across passenger vehicles, commercial fleets, electric mobility platforms, and autonomous transportation applications. Both demand-side and supply-side analysis approaches are used to understand technology adoption patterns and ecosystem development.
Step 3: Hypothesis Validation and Expert Consultation
Market assumptions are validated through consultations with automotive technology stakeholders, vehicle manufacturers, Tier-1 suppliers, semiconductor companies, and mobility solution providers. Expert discussions are conducted to understand procurement strategies, computing architecture preferences, integration challenges, technology adoption barriers, and future investment priorities within Singapore’s intelligent mobility ecosystem.
Step 4: Research Synthesis and Final Output
The final stage involves consolidating primary and secondary research findings to develop a comprehensive market assessment. Industry insights are used to validate segmentation analysis, competitive positioning, technology trends, and future opportunities. The final output provides strategic understanding of market dynamics, growth opportunities, challenges, and competitive developments in Singapore’s in-vehicle computing ecosystem.

- Executive Summary
- Research Methodology (Market Definition and Scope, Singapore In-Vehicle Computer System Classification, Automotive Computing Architecture Assessment, Vehicle Electronic Control Architecture Mapping, Centralized Vehicle Computing System Evaluation, Domain Controller Technology Assessment, Zonal Computing Architecture Analysis, Connected Vehicle Computing Framework Assessment, Autonomous Driving Computing Application Mapping, Automotive Semiconductor Ecosystem Analysis, Embedded Software Platform Evaluation, Vehicle Operating System Classification, Automotive Data Processing Architecture Assessment, OEM and Tier Supplier Ecosystem Mapping)

- Definition and Scope
- Singapore In-Vehicle Computer System Industry Evolution and Development of Intelligent Mobility
- Automotive Computing Architecture, Hardware Integration and Software Platform Structure
- Singapore In-Vehicle Computer System Value Chain Analysis
- Singapore In-Vehicle Computer System Supply Chain Analysis
- Vehicle Computer Hardware, Automotive SoC, ECU Consolidation, Domain Controller, Connectivity Module and Embedded Software Ecosystem Analysis
- Smart Mobility System Integration Assessment Across Internal Combustion Engine Vehicles, Hybrid Vehicles and Electric Vehicles

- Growth Drivers (Government Smart Mobility Initiatives, Expansion of Electric Vehicle Ecosystem, Increasing Connected Vehicle Adoption, Development of Autonomous Vehicle Testing Infrastructure, Rising Demand for Digital Cockpit Systems, Growth of Automotive Software and Semiconductor Capabilities)
- Market Challenges (Limited Domestic Vehicle Manufacturing Base, Dependence on Imported Automotive Semiconductor Components, High Integration Complexity of Advanced Computing Systems, Cybersecurity Requirements for Connected Vehicles, Small Domestic Automotive Market Size, Regulatory Compliance Complexity)
- Market Opportunities (Expansion of Autonomous Mobility Solutions, Development of Smart Transportation Infrastructure, Increasing EV Charging Ecosystem Integration, Growth of Vehicle Data Analytics Platforms, Advancement of AI-Based Automotive Computing, Increasing Demand for Software-Defined Vehicles)
- Market Trends (Centralized Vehicle Computing Architecture Adoption, AI-Powered Vehicle Processing, Software-Defined Vehicle Development, Digital Cockpit Expansion, 5G Connected Vehicle Integration, Cloud-Based Vehicle Management Platforms, Automotive Cybersecurity Enhancement)
- Regulatory and Standards Landscape (Land Transport Authority Intelligent Transport Systems Framework, Singapore Autonomous Vehicle Testing Regulations, Electric Vehicle Early Adoption Incentive Scheme, Vehicle Type Approval Requirements, Cybersecurity Standards for Connected Vehicles, Automotive Software Safety Standards)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Competition Ecosystem

- By Market Value (2020-2025)
- By In-Vehicle Computer System Installation Volume (2020-2025)
- By Passenger Vehicle Computing System Deployment Volume (2020-2025)
- By Commercial Vehicle Computing System Deployment Volume (2020-2025)
- By Electric Vehicle Computing System Deployment Volume (2020-2025)
- By Connected Vehicle Computing Platform Deployment Volume (2020-2025)
- By Autonomous Driving Computing System Deployment Volume (2020-2025)

- By Vehicle Type (In Value %)
Passenger Vehicles
Premium Passenger Vehicles
Electric Passenger Vehicles
Hybrid Vehicles
Commercial Vehicles
Light Commercial Vehicles
Heavy Commercial Vehicles
Public Transport Vehicles
Autonomous Mobility Vehicles - By Computing Architecture Type (In Value %)
Centralized Vehicle Computing Systems
Domain Controller-Based Computing Systems
Cockpit Domain Controllers
ADAS Domain Controllers
Powertrain Domain Controllers
Body Control Domain Controllers
Zonal Computing Systems
Distributed ECU-Based Computing Systems
High-Performance Vehicle Computing Platforms - By Application Type (In Value %)
Digital Cockpit Computing
Advanced Driver Assistance System Computing
Vehicle Connectivity and Telematics Processing
Battery Management System Computing
Powertrain Control Computing
Electric Motor Control Computing
Autonomous Driving Computing
Fleet Management and Mobility Analytics Processing - By Processing Technology (In Value %)
Microcontroller Unit (MCU)-Based Automotive Computing
Microprocessor Unit (MPU)-Based Automotive Computing
System-on-Chip (SoC)-Based Vehicle Computing Platforms
Artificial Intelligence Accelerator-Based Computing Systems
GPU Integrated Automotive Computing Platforms
Neural Processing Unit (NPU)-Enabled Vehicle Computing Systems - By Connectivity Technology (In Value %)
4G Connected Vehicle Computing Systems
5G Enabled Automotive Computing Platforms
Vehicle-to-Everything (V2X) Communication Systems
Cloud Connected Vehicle Computing Platforms
Edge Computing-Based Automotive Systems
Smart Mobility Infrastructure Integrated Computing Systems - By Software Platform (In Value %)
AUTOSAR-Based Automotive Computing Platforms
Android Automotive Operating Systems
Linux-Based Vehicle Computing Platforms
QNX Automotive Software Platforms
Proprietary OEM Vehicle Operating Systems
Automotive Middleware and Application Platforms - By End User Application (In Value %)
Private Vehicle Owners
Fleet Operators
Public Transportation Operators
Ride-Hailing and Mobility Service Providers
Autonomous Vehicle Developers
Corporate Mobility Solutions Providers - By Region (In Value %)
Central Region
East Region
North Region
North-East Region
West Region

- Market Share of Major Players (By Revenue, Vehicle Computing Architecture, Application Segment, Vehicle Type, OEM Partnership Network, Software Platform Integration, Semiconductor Platform Usage, Customer Segment Distribution)
- Cross Comparison Parameters (Automotive Computing Architecture Capability, AI Processing Performance, Automotive SoC Integration Capability, Connected Vehicle Platform Compatibility, ADAS Computing Capability, Software Ecosystem Strength, OEM and Mobility Partnership Network, Automotive Cybersecurity Capability)
- SWOT Analysis of Major Players
- Pricing and System Category Benchmarking
- Detailed Profiles of Major Companies
NVIDIA – Automotive AI Computing Platforms, Autonomous Driving Computers and Vehicle Intelligence Solutions
Qualcomm – Snapdragon Automotive Platforms, Vehicle SoCs and Connected Computing Solutions
Intel – Automotive Computing Platforms and AI-Based Vehicle Processing Technologies
Robert Bosch GmbH – Vehicle Computers, Embedded Systems and Automotive Electronics Solutions
Continental AG – Vehicle Computing Architecture, Cockpit Systems and Software-Defined Vehicle Solutions
Aptiv – Smart Vehicle Architecture, Automotive Software and Computing Platforms
Renesas Electronics – Automotive Microcontrollers, SoCs and Embedded Computing Solutions
NXP Semiconductors – Automotive Processors, Vehicle Networking and Secure Computing Platforms
Texas Instruments – Automotive Processors, Embedded Computing and Vehicle Electronics Solutions
STMicroelectronics – Automotive Semiconductor Components and Vehicle Computing Technologies
Tata Elxsi – Automotive Software Engineering, Digital Cockpit and Connected Vehicle Solutions
KPIT Technologies – Automotive Software Platforms and Intelligent Mobility Solutions
HARMAN International – Connected Vehicle Platforms, Digital Cockpit and Infotainment Computing Solutions
Mitsubishi Electric – Automotive Electronics and Vehicle Control Computing Solutions
Denso Corporation – Automotive Electronics, Vehicle Computing and Mobility Technology Solutions

- Vehicle Owner Technology Adoption Assessment
- Passenger Vehicle Manufacturer Analysis
- Electric Vehicle Manufacturer Analysis
- Commercial Fleet Operator Analysis
- Public Transport Operator Analysis
- Autonomous Vehicle Technology Developer Analysis
- Automotive Tier-1 Supplier Analysis
- Mobility-as-a-Service Provider Analysis
- Connected Vehicle Solution Provider Analysis

- By Market Value (2026-2035)
- By In-Vehicle Computer System Installation Volume (2026-2035)
- By Passenger Vehicle Computing System Deployment Volume (2026-2035)
- By Commercial Vehicle Computing System Deployment Volume (2026-2035)
- By Electric Vehicle Computing System Deployment Volume (2026-2035)
- By Connected Vehicle Computing Platform Deployment Volume (2026-2035)
- By Autonomous Vehicle Computing System Deployment Volume (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
