
 Download PDF
Market Overview
The Singapore Mining Drill Bits Market is closely associated with rock excavation, geotechnical drilling, tunnelling, foundation works and construction-material activities because the country has limited conventional mineral extraction. Singapore’s total construction demand increased from S$33.8 billion in 2023 to S$44.2 billion in 2024, while construction output rose from S$34.8 billion to S$38.4 billion, according to the Building and Construction Authority. The expansion of infrastructure, residential, industrial and civil-engineering projects creates recurring requirements for DTH, top-hammer, rotary and diamond drill bits across drilling contractors and construction applications.
Singapore’s Mining Drill Bits Market is concentrated around major infrastructure, tunnelling, foundation and construction activity rather than traditional mining centres. Jurong, Tuas, Changi and other major development corridors generate drilling requirements through port, airport, industrial, transport and urban-development projects. BCA recorded S$19.5 billion of public-sector construction demand and S$14.3 billion of private-sector demand in 2023, while 2024 construction demand reached S$44.2 billion. Singapore also regulates commercial imports of sand and granite through BCA licensing, permits and aggregate testing, reinforcing the importance of construction-material and rock-related supply chains.
Market Segmentation
By Drill Bit Type
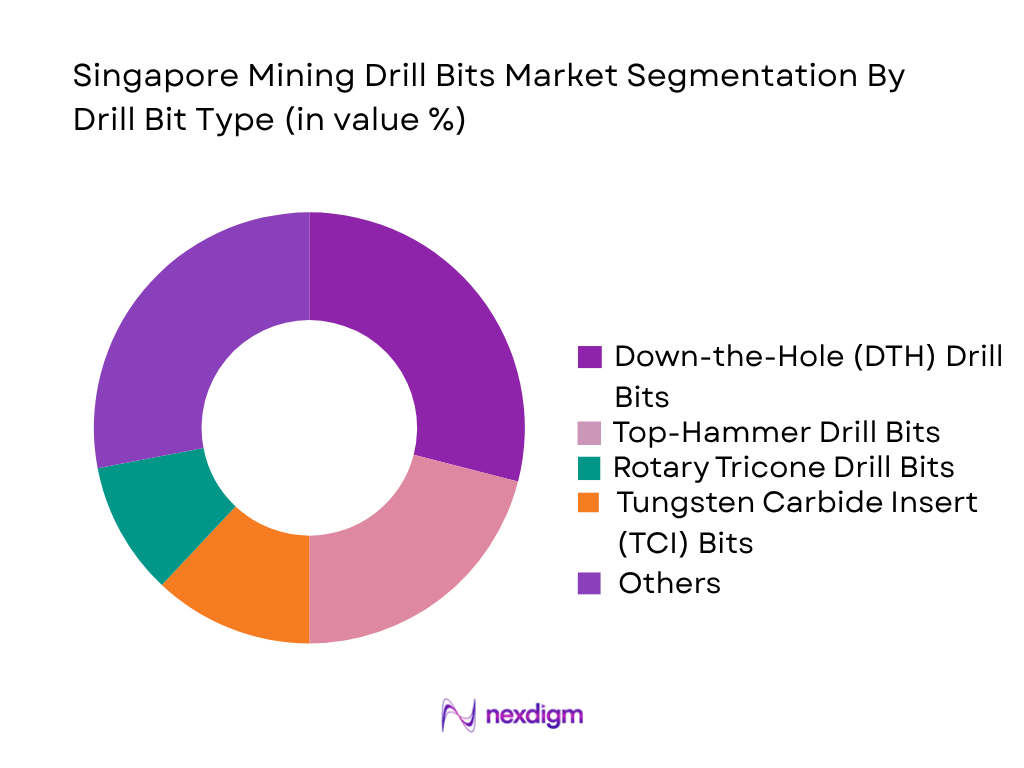
The Singapore Mining Drill Bits Market is segmented by drill bit type into Down-the-Hole (DTH) drill bits, top-hammer drill bits, rotary tricone drill bits, tungsten carbide insert (TCI) bits, milled-tooth drill bits, polycrystalline diamond compact (PDC) bits, diamond core bits, drag bits, button bits and specialty rock-drilling bits. DTH drill bits represent the leading sub-segment in the analytical segmentation because their operating characteristics are well suited to hard-rock excavation, quarry-derived aggregate applications and large-diameter drilling requirements. Singapore’s construction ecosystem handles substantial quantities of imported sand and granite, with aggregate terminals capable of handling up to 33 million tonnes annually. BCA also requires licensing and quality testing for commercial imports of sand and granite, demonstrating the strategic importance of construction aggregates to the domestic construction supply chain. DTH systems provide consistent penetration and hole accuracy in demanding formations and can be deployed across construction, foundation, geotechnical and infrastructure applications. Demand is therefore influenced less by domestic mineral extraction and more by rock-drilling requirements associated with infrastructure development, tunnelling and construction activity.
By Application Area
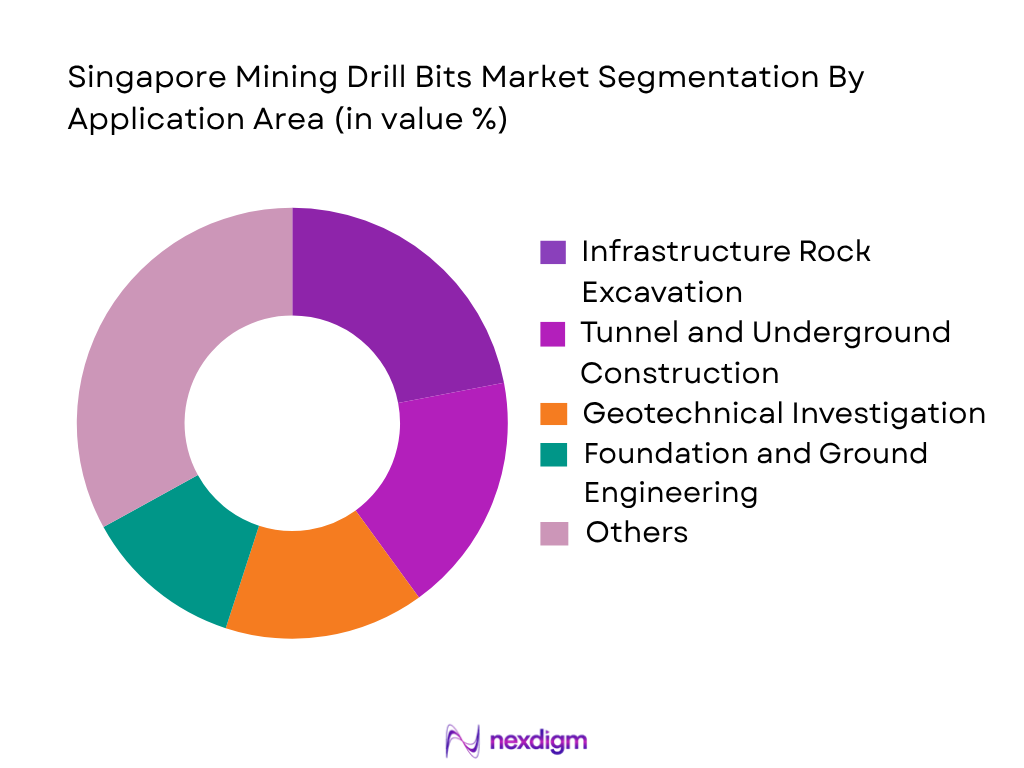
The Singapore Mining Drill Bits Market is segmented by application area into stone quarrying, limestone and aggregate extraction, sand and clay quarrying, construction-material extraction, infrastructure rock excavation, tunnel and underground construction, geotechnical investigation, mineral exploration, foundation and ground engineering, and other rock-drilling applications. Infrastructure rock excavation represents a leading application in the analytical segmentation because Singapore’s constrained land area and extensive infrastructure development require specialized drilling for foundations, underground structures, tunnelling and civil-engineering works. BCA projected total construction demand of S$32 billion–S$38 billion for 2024 and construction output of S$34 billion–S$37 billion, providing a significant downstream environment for drilling contractors and construction-equipment suppliers. Singapore’s aggregate supply chain is also highly dependent on imported materials: BCA regulates commercial imports of sand and granite through licensing, permits and testing requirements. These conditions support demand for drilling technologies used in construction and ground engineering even though Singapore itself has limited conventional mineral production. Diamond core bits, DTH bits and top-hammer systems are consequently relevant across different geological investigation and rock-excavation requirements.
Competitive Landscape
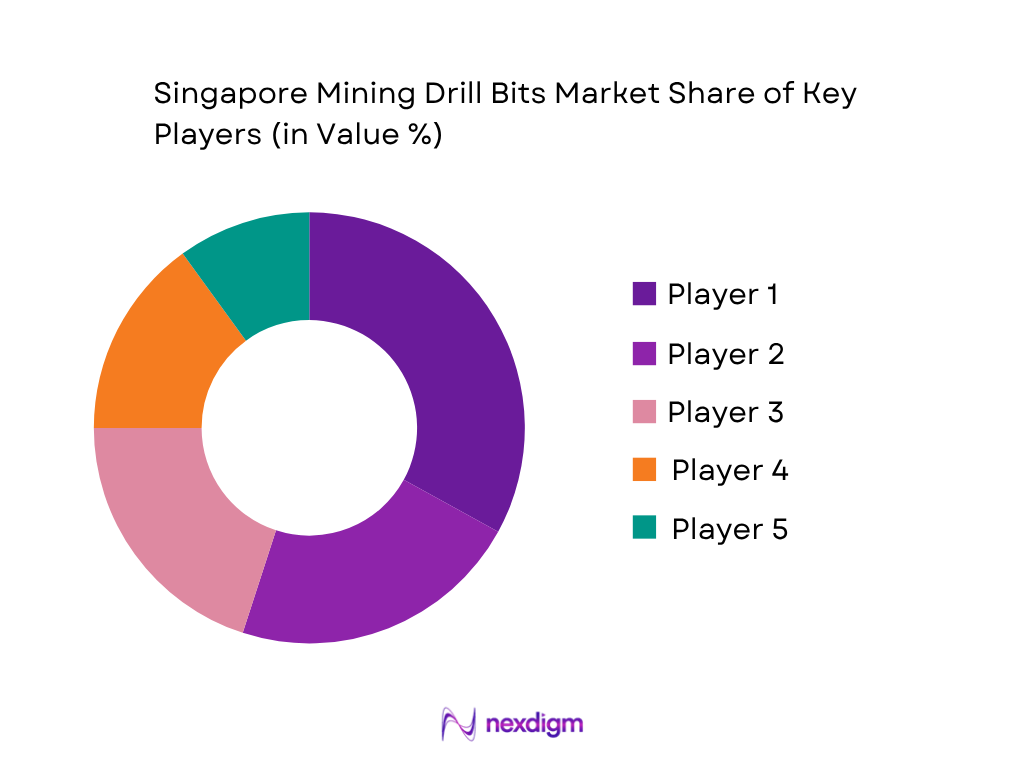
The Singapore Mining Drill Bits Market is characterized by international drilling-equipment and rock-tool manufacturers serving the country through direct operations, regional headquarters, distributors and equipment-service networks. Companies such as Sandvik, Epiroc, Boart Longyear, Komatsu and Caterpillar participate across drilling equipment, rock tools, consumables and technical services. Competitive differentiation is primarily associated with drill-bit durability, penetration performance, compatibility with drilling rigs, carbide and diamond technology, aftermarket availability and technical support. Singapore’s position as a regional logistics and industrial hub also allows international equipment suppliers to support customers through broader Southeast Asian distribution networks.
| Company | Establishment Year | Headquarters | DTH Technology | Top-Hammer Technology | Diamond Drilling | Carbide Tooling | Aftermarket Support | Singapore/Regional Presence |
| Sandvik Mining and Rock Solutions | 1862 | Stockholm, Sweden | ~ | ~ | ~ | ~ | ~ | ~ |
| Epiroc | 2018 | Stockholm, Sweden | ~ | ~ | ~ | ~ | ~ | ~ |
| Boart Longyear | 1890 | Salt Lake City, USA | ~ | ~ | ~ | ~ | ~ | ~ |
| Komatsu | 1921 | Tokyo, Japan | ~ | ~ | ~ | ~ | ~ | ~ |
| Caterpillar | 1925 | Irving, USA | ~ | ~ | ~ | ~ | ~ | ~ |
Singapore Mining Drill Bits Market Analysis
Growth Drivers
Expansion of Construction and Civil Infrastructure Activity
Singapore’s expanding construction pipeline is creating sustained requirements for drilling equipment and consumables, including mining drill bits used in rock excavation, bored piling, tunnelling, site investigation and aggregate-related activities. Total construction demand reached S$44.2 billion, while construction output reached S$38.4 billion, establishing a substantial downstream base for drilling contractors and equipment suppliers. Public-sector construction demand reached S$25.9 billion, while private-sector demand reached S$18.3 billion, demonstrating the breadth of project activity across government-led and private developments. Major infrastructure programs involving MRT expansion, Changi Airport Terminal 5, Tuas Port and large-scale residential developments require excavation, foundation and civil-engineering activities where drilling tools are essential. The medium-term construction pipeline is also expected to maintain annual demand within the S$39 billion–S$46 billion range from 2026 to 2029. Underground construction and foundation applications are particularly relevant because drilling conditions can involve hard strata, requiring DTH, top-hammer, rotary and diamond drilling technologies. Increasing project complexity is also creating demand for drill bits that provide consistent penetration, controlled hole geometry and longer operating cycles. The combination of transport infrastructure, underground construction and industrial development therefore provides a recurring demand base for specialized drilling consumables across Singapore’s construction ecosystem.
Strengthening Precision Engineering and Industrial Manufacturing Base
Singapore’s advanced manufacturing ecosystem supports demand for specialized drilling equipment through precision engineering, industrial facilities, semiconductor plants, aerospace infrastructure and equipment-intensive construction projects. Manufacturing output reached S$429.584 billion, compared with S$410.871 billion, while precision engineering generated S$51.983 billion in output, demonstrating the scale of industrial activity supporting equipment-intensive development. Electronics manufacturing alone generated S$181.166 billion in output, creating a large ecosystem of semiconductor, electronics and industrial facilities requiring construction, expansion and maintenance activities. Manufacturing establishments numbered 9,858, while manufacturing value added reached S$116.595 billion, reinforcing the depth of Singapore’s industrial base. Fixed-asset investment commitments reached S$13.5 billion, with S$11.1 billion associated with manufacturing projects, including semiconductor, biomedical, aerospace and advanced industrial developments. Construction of these facilities involves ground investigation, foundation drilling, excavation and underground utility installation, generating opportunities for specialized drilling products. High-value industrial projects also require accurate drilling where hole diameter, depth, penetration rate and tool wear need to be tightly controlled. The concentration of technologically sophisticated facilities therefore creates demand for higher-performance drilling products rather than basic commodity tools. Suppliers that combine drill-bit technology with application engineering, equipment compatibility and technical support can address requirements from Singapore’s increasingly sophisticated industrial construction environment.
Market Challenges
Limited Domestic Mineral Extraction and Conventional Mining Activity
Singapore presents a structurally different demand environment from countries with substantial coal, iron ore, copper or gold mining industries because domestic conventional mineral extraction is limited. Consequently, mining drill-bit demand is primarily associated with construction-related rock excavation, tunnelling, foundation drilling, geotechnical investigation and construction-material activities rather than continuous large-scale mine production. Construction demand reached S$44.2 billion, demonstrating the importance of construction as the principal downstream activity for drilling-related applications. Construction-material requirements also include aggregates such as granite, with official statistics recording 1,765.60 thousand tonnes of granite demand in June 2025. However, the absence of extensive domestic mineral deposits restricts the number of applications where mining-specific drill bits can be consumed continuously at mine sites. Suppliers must therefore target construction contractors, tunnelling companies, foundation specialists, geotechnical operators and companies involved in construction-material handling. This concentration makes demand more dependent on infrastructure-development schedules and individual project cycles. Product suppliers may also face challenges in maintaining consistent volumes when major projects reach completion. Demand can consequently shift between DTH, top-hammer, rotary and diamond drilling depending on the geological and engineering requirements of each project. The market structure requires suppliers to adapt mining drill-bit products toward construction and civil-engineering applications to maintain broader utilization.
Dependence on Project-Based Construction and Specialized Equipment Requirements
Demand for drill bits in Singapore is closely connected to infrastructure, tunnelling, foundation and industrial construction projects, creating exposure to project timing, construction sequencing and technical specifications. Construction demand reached S$44.2 billion, while construction output stood at S$38.4 billion, and the medium-term pipeline is projected to remain within S$39 billion–S$46 billion annually from 2026 to 2029. Although this represents substantial activity, individual projects can require different drilling technologies according to ground conditions, hole diameter, drilling depth and equipment configuration. MRT construction, underground utility projects, foundation works and industrial developments may require specialized drilling solutions rather than standardized mining products. Formal construction requirements also increase the importance of equipment reliability, documentation and technical compliance. The CONQUAS framework is mandatory for specified public-sector projects with estimated construction costs of S$10 million or above, illustrating the quality-control environment surrounding major construction activity. Drill-bit suppliers must therefore meet contractor requirements relating to drilling accuracy, durability, compatibility and operational consistency. Technical qualification can also increase the time required for suppliers to establish themselves with major contractors. Furthermore, project-specific procurement can make replacement demand dependent on construction schedules, drilling intensity and contractor equipment fleets. These characteristics create a need for suppliers to maintain responsive technical support and application-specific product portfolios.
Market Opportunities
Growth of Tunnelling, Underground Infrastructure and Foundation Drilling
Singapore’s continued investment in underground transportation, utilities and major civil infrastructure creates opportunities for drill-bit suppliers to expand beyond conventional mining applications. Major infrastructure programs include the Cross Island MRT Line Phase 3, Downtown Line Extension to Sungei Kadut, Changi Airport Terminal 5, Tuas Port and major healthcare and urban-development projects. The medium-term construction pipeline is expected to maintain annual construction demand within S$39 billion–S$46 billion from 2026 to 2029, providing a substantial base of civil-engineering activity. Bored tunnelling, foundation drilling and underground construction require drilling technologies capable of operating across variable geological conditions. This supports opportunities for DTH, top-hammer, rotary, button and specialized drilling bits designed for hard-ground applications. Demand can also extend to diamond drilling products used for geological investigation, foundation assessment and construction-site characterization. Suppliers can strengthen their position by combining drill-bit sales with technical services such as bit selection, drilling-parameter optimization, wear monitoring and replacement planning. The opportunity is particularly relevant for companies capable of providing application-specific solutions rather than relying exclusively on conventional mining products. Singapore’s emphasis on underground infrastructure also creates scope for longer-life drilling tools that can improve drilling continuity and reduce equipment interruptions during tightly scheduled projects.
Industrial and Semiconductor Infrastructure Development
Singapore’s continuing development as an advanced manufacturing hub creates opportunities for mining drill-bit suppliers through industrial construction, facility expansion and specialized ground-engineering requirements associated with semiconductor, aerospace, biomedical and precision-engineering projects. Fixed-asset investment commitments reached S$13.5 billion, including S$11.1 billion from manufacturing, providing evidence of continued industrial development activity. Manufacturing output reached S$429.584 billion, while electronics manufacturing generated S$181.166 billion, supporting a large base of technologically intensive facilities. Semiconductor, biomedical, aerospace and other advanced manufacturing projects require new factories, facility expansions, utility infrastructure, foundations and site-development works. These activities can involve ground investigation, piling, excavation and underground service installation, creating applications for specialized drilling tools. The opportunity is particularly relevant for high-precision drill bits, carbide products, diamond drilling solutions and application-specific tools capable of meeting controlled drilling requirements. Suppliers can also expand their addressable market by working with construction contractors responsible for industrial facilities rather than limiting sales to conventional mining customers. Combining drill-bit supply with equipment servicing, technical support and drilling-process optimization can improve customer retention. As Singapore continues to attract capital-intensive manufacturing projects, suppliers with specialized drilling technologies can participate in the associated construction and ground-engineering ecosystem.
Future Outlook
Over the forecast period, the Singapore Mining Drill Bits Market is expected to remain closely linked to infrastructure construction, underground development, geotechnical investigation and specialized rock excavation rather than large-scale domestic mineral extraction. Singapore’s construction sector provides an important demand foundation, while the country’s dependence on imported sand and granite makes aggregate logistics and construction-material quality strategically important. BCA’s aggregate infrastructure can handle up to 33 million tonnes of sand and granite annually, while the Jurong Port Integrated Construction Park is designed to integrate aggregate handling with downstream construction-material production. Future demand is therefore expected to emphasize high-performance drilling consumables, longer-life carbide structures, application-specific DTH configurations, diamond drilling and technical aftermarket services.
Major Players
- Sandvik Mining and Rock Solutions
- Epiroc Singapore Pte Ltd
- Boart Longyear
- Komatsu Singapore Pte Ltd
- Caterpillar Asia Pte Ltd
- Furukawa Rock Drill Co., Ltd.
- Mincon Group plc
- Robit Plc
- Rockmore International
- Mitsubishi Materials Corporation
- Kennametal Inc.
- Halliburton Singapore Pte Ltd
- SLB Singapore Pte Ltd
- Liebherr-Singapore Pte Ltd
- Hitachi Construction Machinery Asia and Pacific Pte. Ltd.
Key Target Audience
- Quarrying and aggregate operators
- Construction and civil-engineering contractors
- Geotechnical and drilling contractors
- Infrastructure and tunnel-development companies
- Mining and construction equipment distributors
- Investments and venture capitalist firms (Infrastructure funds, industrial technology investors, private-equity firms)
- Government and regulatory bodies (Building and Construction Authority, Ministry of Trade and Industry, Ministry of Manpower, National Environment Agency)
- Drilling-equipment manufacturers and industrial technology suppliers
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves defining the Singapore Mining Drill Bits Market ecosystem, including drill-bit manufacturers, drilling-equipment suppliers, distributors, drilling contractors, quarry-related businesses and infrastructure users. Secondary research is used to identify construction demand, aggregate-import activity, infrastructure development, drilling applications and equipment requirements. Market variables include drill-bit type, application, drilling method, material composition, equipment compatibility and end-user category.
Step 2: Market Analysis and Construction
Historical market information is compiled through top-down and bottom-up assessment of drilling consumables, construction activity, aggregate requirements and drilling applications. Singapore’s construction-output data and regulated sand and granite import framework are incorporated into the demand model. Product-level analysis evaluates DTH, top-hammer, rotary, carbide and diamond drilling technologies and their relevance across infrastructure, geotechnical and construction applications.
Step 3: Hypothesis Validation and Expert Consultation
Market hypotheses are validated through consultations with drilling contractors, equipment distributors, construction companies and industrial equipment specialists. Discussions focus on drill-bit replacement cycles, rig compatibility, drilling depth, rock conditions, penetration performance, product selection and aftermarket requirements. These inputs are used to cross-check assumptions regarding application demand and the relative importance of individual drilling technologies within Singapore.
Step 4: Research Synthesis and Final Output
The final stage integrates demand-side, supply-side and company-level information into a consolidated Singapore Mining Drill Bits Market assessment. Market estimates are reconciled through data triangulation involving construction activity, aggregate requirements, drilling applications and supplier information. The resulting analysis provides segmentation, competitive assessment, market drivers, challenges, opportunities and future-demand scenarios while distinguishing published government statistics from analytical market estimates.

- Executive Summary
- Research Methodology (Market Definition and Scope, Singapore Mining Drill Bits Market Classification, Drill Bit Technology Mapping, DTH Drilling Assessment, Top-Hammer Drilling Evaluation, Rotary Drilling Technology Analysis, Carbide Button Technology Assessment, Diamond Drilling Evaluation, Drill-Rig Compatibility Mapping, Quarrying Application Assessment, Construction-Material Extraction Assessment, Exploration Drilling Assessment, Drill-Bit Consumption Estimation, Demand-Side Assessment, Supply-Side Assessment, Top-Down Market Sizing, Bottom-Up Market Sizing, Primary Industry Interviews, Data Triangulation, Forecasting Framework)

- Definition and Scope
- Singapore Mining and Quarrying Industry Evolution and Development of Construction Aggregate Extraction, Stone Quarrying, Sand and Clay Quarrying, Underground Infrastructure Excavation, Marine and Civil Engineering Development, Geological Investigation Activities, Construction-Material Supply Chain Development, Imported Mining Equipment Adoption and Industrial Drilling Technology Deployment
- Mining Drill Bits Value Chain Analysis
- Mining Drill Bits Supply Chain Analysis
- Drill-Bit Manufacturers, Carbide Insert Suppliers, Diamond Tool Suppliers, Drilling Equipment Manufacturers, Drill-Rig Suppliers, Mining Equipment Distributors, Industrial Equipment Distributors, Quarrying Contractors, Drilling Contractors, Construction Companies, Infrastructure Developers, Geological Investigation Contractors and End-Use Operators

- Growth Drivers (Expansion of Construction and Infrastructure Projects, Growth in Rock Excavation Requirements, Demand for Construction Aggregates, Tunnel and Underground Infrastructure Development, Geotechnical Investigation Activity, Replacement Demand for Drilling Consumables, Adoption of High-Performance Drill Bits)
- Market Challenges (Limited Domestic Mineral Production, Small Quarrying Base, Dependence on Imported Drill-Bit Technologies, Limited Local Mining Operations, High Equipment and Consumable Logistics Dependency, Restricted Land Availability, Environmental and Land-Use Constraints)
- Market Opportunities (Advanced DTH Drill-Bit Adoption, High-Wear-Resistance Carbide Technologies, Infrastructure and Tunnel Drilling Applications, Geotechnical and Ground-Investigation Drilling, Digital Drill-Bit Performance Monitoring)
- Market Trends (Shift Toward High-Performance Carbide Bits, Increasing Drill-Rig Automation, Digital Drilling Monitoring, Longer-Life Cutting Structures, Demand for Application-Specific Bits, Sustainable Drilling Practices, Equipment Productivity Optimization, Expansion of Advanced Geotechnical Drilling Technologies)
- Government Regulations and Standards (Singapore Sand and Granite Quarries Act, Singapore Building and Construction Authority Requirements, Singapore Workplace Safety and Health Act, Workplace Safety and Health Regulations, National Environment Agency Environmental Requirements, Singapore Standard Industrial Classification Requirements)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Competition Ecosystem

- By Market Value (2020-2025)
- By Drill Bit Consumption Volume (2020-2025)
- By Average Selling Price (2020-2025)
- By DTH Drill Bit Consumption Volume (2020-2025)
- By Top-Hammer Drill Bit Consumption Volume (2020-2025)
- By Rotary Drill Bit Consumption Volume (2020-2025)
- By Diamond Core Bit Consumption Volume (2020-2025)
- By Carbide Drill Bit Consumption Volume (2020-2025)
- By Quarrying-Related Drill Bit Consumption Volume (2020-2025)

- By Drill Bit Type (In Value %)
Down-the-Hole (DTH) Drill Bits
Top-Hammer Drill Bits
Rotary Tricone Drill Bits
Tungsten Carbide Insert (TCI) Bits
Milled-Tooth Drill Bits
Polycrystalline Diamond Compact (PDC) Bits
Diamond Core Bits
Drag Bits
Button Bits
Specialty Rock and Mining Drill Bits - By Drilling Method (In Value %)
Percussive Drilling
Rotary Drilling
Rotary-Percussive Drilling
Core Drilling
Down-the-Hole Hammer Drilling
Top-Hammer Drilling
Diamond Drilling
Blast-Hole Drilling - By Application Area (In Value %)
Stone Quarrying
Limestone and Aggregate Extraction
Sand and Clay Quarrying
Construction Material Extraction
Infrastructure Rock Excavation
Tunnel and Underground Construction
Geotechnical Investigation
Mineral Exploration
Foundation and Ground Engineering
Other Rock Drilling Applications - By Drill Bit Material and Cutting Structure (In Value %)
Tungsten Carbide Button Bits
Carbide Insert Bits
Diamond-Impregnated Bits
Polycrystalline Diamond Compact Cutting Structures
Milled-Tooth Cutting Structures
Steel-Tooth Cutting Structures
Diamond Surface-Set Bits
Hybrid Cutting Structures - By End-Use Industry (In Value %)
Quarrying and Aggregate Industry
Construction Industry
Civil Engineering and Infrastructure
Tunnel Construction
Geotechnical Engineering
Marine and Port Infrastructure
Industrial Manufacturing
Environmental and Ground Investigation
Mineral Exploration
Other Drilling Applications - By Equipment Compatibility (In Value %)
Crawler Drill Rigs
Rotary Blast-Hole Rigs
DTH Drill Rigs
Top-Hammer Drill Rigs
Core Drilling Rigs
Underground Drilling Equipment
Geotechnical Drill Rigs
Portable Drilling Systems - By Customer Type (In Value %)
Quarry Operators
Drilling Contractors
Construction Contractors
Civil Engineering Contractors
Geotechnical Contractors
Infrastructure Developers
Mining Equipment Distributors
Industrial Equipment Users

- Market Share of Major Players (Singapore Revenue, Drill-Bit Product Coverage, DTH Product Portfolio, Top-Hammer Technology Coverage, Diamond Drilling Capability, Carbide Technology Portfolio, Drill-Rig Compatibility, Quarrying Application Coverage, Geotechnical Application Coverage, Distribution Network, Aftermarket Service Capability, Technical Support, Product Availability, Regional Supply Chain Reach)
- Cross Comparison Parameters (DTH Drill-Bit Portfolio Breadth, Top-Hammer Drill-Bit Capability, Carbide Cutting Structure Technology, Diamond Core Drilling Capability, Drill-Rig Compatibility Coverage, Hard-Rock Drilling Expertise, Product Customization Capability, Aftermarket and Technical Support Network)
- SWOT Analysis of Major Players
- Competitive Positioning Matrix
- Drill-Bit Technology and Performance Benchmarking
- Quarrying and Construction Drilling Assessment
- Drill-Bit Procurement and Aftermarket Assessment
- Detailed Profiles of Major Companies
Sandvik Mining and Rock Solutions
Epiroc Singapore Pte Ltd
Boart Longyear
Komatsu Singapore Pte Ltd
Caterpillar Asia Pte Ltd
Furukawa Rock Drill Co., Ltd.
Mincon Group plc
Robit Plc
Rockmore International
Mitsubishi Materials Corporation
Kennametal Inc.
Halliburton Singapore Pte Ltd
Schlumberger Singapore Pte Ltd
Liebherr-Singapore Pte Ltd
Hitachi Construction Machinery Asia and Pacific Pte. Ltd.

- Quarry Operator Procurement Assessment
- Drilling Contractor Demand Analysis
- Construction Contractor Requirement Assessment
- Tunnel Contractor Drilling Requirement Analysis
- Geotechnical Contractor Assessment
- Infrastructure Developer Procurement Assessment
- Mining Equipment Distributor Demand Assessment
- Drill-Bit Replacement and Reordering Analysis
- Product Selection Criteria Assessment
- Supplier Evaluation Assessment

- By Market Value (2026-2035)
- By Drill Bit Consumption Volume (2026-2035)
- By Average Selling Price (2026-2035)
- By DTH Drill Bit Consumption Volume (2026-2035)
- By Top-Hammer Drill Bit Consumption Volume (2026-2035)
- By Rotary Drill Bit Consumption Volume (2026-2035)
- By Diamond Core Bit Consumption Volume (2026-2035)
- By Carbide Drill Bit Consumption Volume (2026-2035)
- By Quarrying-Related Drill Bit Consumption Volume (2026-2035)
- By Geotechnical Drilling Application Volume (2026-2035)
- By Infrastructure Rock Excavation Application Volume (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
