
 Download PDF
Market Overview
The Singapore Plastic Pipes and Fittings Market is valued at approximately USD ~XX billion, supported by demand from water infrastructure, residential developments, industrial facilities, commercial buildings, and advanced manufacturing sectors. The market is driven by Singapore’s highly developed water management ecosystem, where plastic piping systems are used across potable water distribution, wastewater networks, NEWater facilities, and desalination infrastructure. Singapore’s total population reached approximately 6.04 million, according to the Singapore Department of Statistics, increasing requirements for reliable urban water networks and building services infrastructure. The Public Utilities Board (PUB) manages more than 6,000 kilometers of water pipelines, creating continuous demand for durable plastic pipe systems. Growth in semiconductor manufacturing, data centers, and industrial facilities further supports adoption of HDPE, PVC, and PPR piping solutions due to their corrosion resistance, lightweight characteristics, and long operational lifespan.
The Singapore Plastic Pipes and Fittings Market is concentrated across Singapore’s Central Region, East Region, West Region, and industrial clusters due to the country’s dense urban development and infrastructure requirements. The Central Region dominates demand because of extensive commercial buildings, residential developments, hospitality infrastructure, and government facilities requiring plumbing and utility systems. Jurong Island and Tuas represent major industrial demand centers due to petrochemical, manufacturing, and process industries requiring specialized piping solutions. According to Singapore Economic Development Board data, Singapore hosts more than 7,000 multinational corporations, supporting industrial infrastructure requirements. The growth of data centers in Singapore also increases demand for specialized cooling and utility piping systems. Residential projects developed under Housing & Development Board programs further contribute to consumption of plastic pipes for domestic water supply, drainage, and sanitation applications.
Market Segmentation
By Material Type
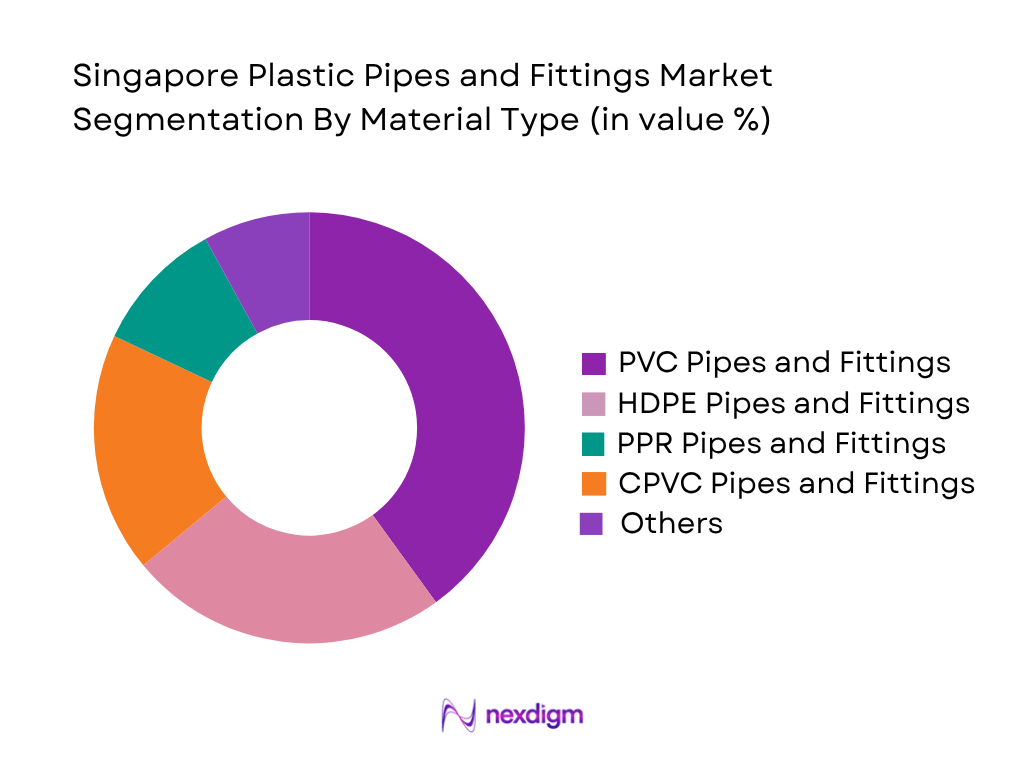
The Singapore Plastic Pipes and Fittings Market is segmented by material type into PVC pipes and fittings, HDPE pipes and fittings, PPR pipes and fittings, CPVC pipes and fittings, polyethylene pipes, and specialty thermoplastic pipes. PVC pipes and fittings represent the leading segment due to their extensive usage in drainage, sewerage systems, building plumbing, and utility applications. PVC systems are preferred because of their corrosion resistance, durability, cost efficiency, and suitability for Singapore’s humid climate conditions. HDPE pipes are increasingly adopted for water transmission, underground infrastructure, and industrial applications due to flexibility and high impact resistance. PPR pipes are widely used in residential and commercial hot and cold-water systems because of their temperature resistance and long service life. The established use of PVC across public infrastructure, construction projects, and drainage networks contributes to its leading position within the material segmentation.
By Application Type
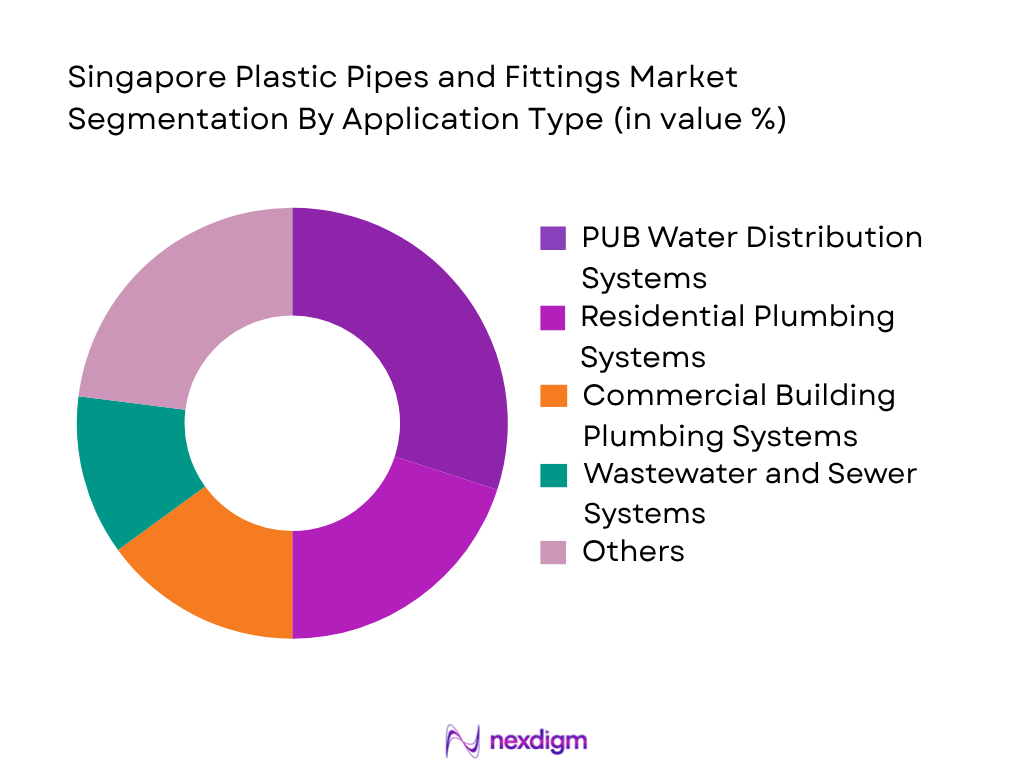
The Singapore Plastic Pipes and Fittings Market is segmented by application type into PUB water distribution systems, NEWater infrastructure, residential plumbing systems, commercial buildings, wastewater networks, industrial process piping, data center cooling systems, marine applications, and electrical conduit systems. PUB water distribution and municipal utility applications represent a dominant segment due to Singapore’s extensive water management infrastructure and continuous requirement for reliable pipeline networks. Plastic pipes are widely utilized in water transmission, distribution, and rehabilitation projects due to their resistance to corrosion and suitability for underground installations. Residential and commercial plumbing applications also contribute significantly because of continuous construction and redevelopment activities. Industrial applications, particularly semiconductor manufacturing and petrochemical facilities, require specialized piping systems capable of handling demanding operating environments. The expansion of data centers and advanced manufacturing facilities further supports demand for high-performance plastic piping solutions.
Competitive Landscape
The Singapore Plastic Pipes and Fittings Market consists of international manufacturers, regional suppliers, and specialized piping solution providers serving infrastructure, construction, industrial, and utility applications. Competition is influenced by product certification, technical capabilities, material portfolio, project experience, and distribution partnerships. Companies operating in the market focus on supplying PVC, HDPE, PPR, CPVC, and specialty piping solutions for water management, industrial applications, and building infrastructure. Global players such as Georg Fischer, Aliaxis, Wavin, Uponor, and REHAU compete alongside regional manufacturers through advanced piping technologies, application-specific solutions, and extensive distribution networks.
| Company | Establishment Year | Headquarters | Product Portfolio | Manufacturing Capability | Key Applications | Distribution Network | Certification Coverage |
| Georg Fischer | 1802 | Switzerland | ~ | ~ | ~ | ~ | ~ |
| Aliaxis | 2003 | Belgium | ~ | ~ | ~ | ~ | ~ |
| Wavin | 1955 | Netherlands | ~ | ~ | ~ | ~ | ~ |
| Uponor | 1918 | Finland | ~ | ~ | ~ | ~ | ~ |
| REHAU | 1948 | Germany | ~ | ~ | ~ | ~ | ~ |
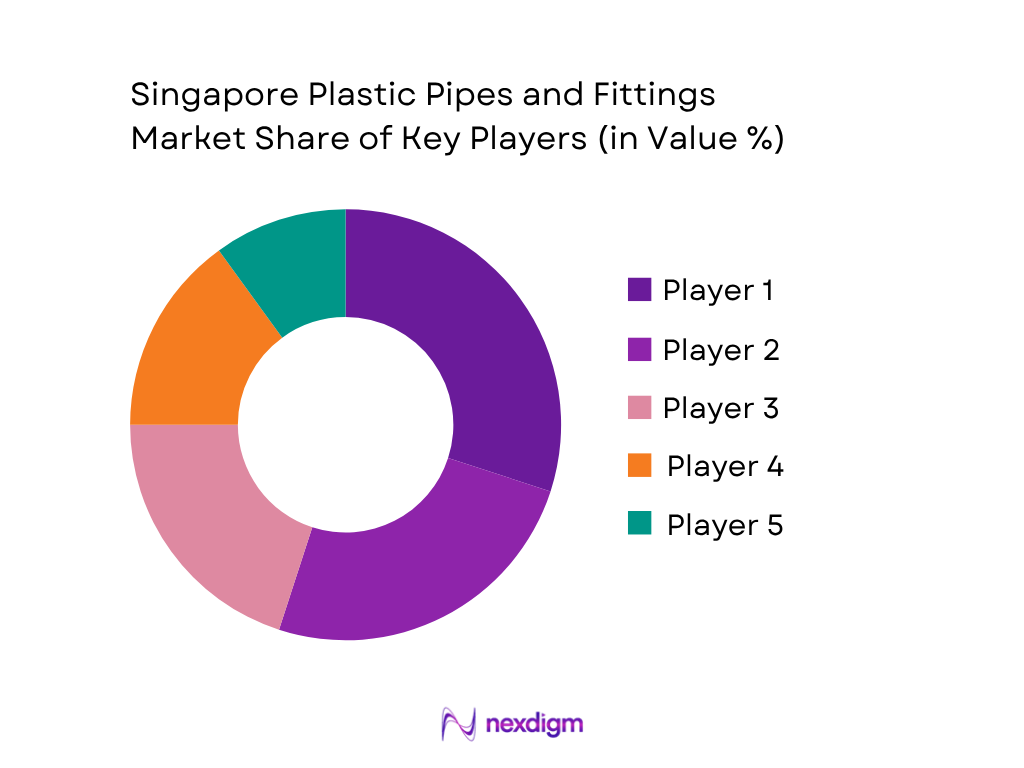
Singapore Plastic Pipes and Fittings Market Analysis
Growth Drivers
Expansion of Water Infrastructure and Advanced Water Management Systems
The Singapore Plastic Pipes and Fittings Market is strongly supported by continuous investments in water infrastructure, NEWater expansion, desalination facilities, and municipal water distribution networks. Singapore’s water security strategy requires extensive use of durable piping systems for potable water transmission, wastewater recycling, and industrial water applications. According to Singapore’s Public Utilities Board (PUB), the country manages more than 6,000 kilometers of water pipelines, creating continuous requirements for PVC, HDPE, and other thermoplastic piping systems across urban utility networks. Singapore’s population reached approximately 6.04 million according to the Singapore Department of Statistics, increasing long-term demand for reliable water supply infrastructure. The country operates four national taps, including imported water, local catchment water, NEWater, and desalinated water, requiring extensive pipeline connectivity and maintenance systems. The UAE and Singapore comparison in water infrastructure highlights Singapore’s high dependence on advanced water management solutions. Plastic pipes are increasingly preferred in water networks due to corrosion resistance, low maintenance requirements, and suitability for underground installations. Expansion of NEWater plants, desalination facilities, and wastewater treatment systems continues supporting demand for advanced plastic piping solutions.
Growth of Industrial Infrastructure, Semiconductor Manufacturing, and Data Center Development
The Singapore Plastic Pipes and Fittings Market benefits from expansion of industrial infrastructure, semiconductor manufacturing facilities, and data center developments requiring specialized piping systems. Singapore remains a major global manufacturing hub, with advanced industries requiring reliable fluid handling, cooling, and utility networks. According to the Singapore Economic Development Board (EDB), the manufacturing sector contributes significantly to national economic activity, with electronics and semiconductor industries representing key investment areas. Singapore’s semiconductor ecosystem includes more than 2,700 companies across electronics manufacturing and related industries, creating demand for high-performance piping solutions used in industrial facilities. The country also hosts a growing data center ecosystem requiring cooling infrastructure, water management systems, and specialized utility networks. According to the Infocomm Media Development Authority (IMDA), Singapore continues developing digital infrastructure to support enterprise connectivity and cloud services. HDPE, PVC, and specialty thermoplastic pipes are increasingly used in industrial applications due to chemical resistance, durability, and operational reliability. Expansion of Jurong Island industrial facilities, Tuas manufacturing zones, and data center infrastructure supports future demand for plastic piping systems across industrial and commercial applications.
Market Challenges
Dependence on Imported Raw Materials and Limited Domestic Manufacturing Capacity
The Singapore Plastic Pipes and Fittings Market faces challenges due to dependence on imported polymer materials and limited domestic production of plastic pipe raw materials. The country imports significant quantities of petrochemical feedstocks and polymer materials required for manufacturing plastic products. According to the Singapore Department of Statistics, Singapore’s total merchandise trade exceeded SGD 1 trillion, reflecting its highly trade-dependent economy and exposure to international supply chain conditions. Plastic pipe manufacturers rely on materials such as PVC resin, polyethylene, polypropylene, and engineering polymers sourced from regional and global suppliers. Although Singapore has a strong petrochemical industry, including large-scale operations in Jurong Island, raw material availability remains influenced by global energy markets and international logistics conditions. According to the Energy Market Authority of Singapore, the country imports almost all of its natural gas requirements for energy generation, highlighting its dependence on international energy supply chains. Fluctuations in global petrochemical production, shipping conditions, and material availability can impact procurement strategies for plastic pipe manufacturers. Maintaining stable supply chains while ensuring compliance with quality requirements remains a key challenge for companies operating within the Singapore Plastic Pipes and Fittings Market.
Strict Regulatory Standards and Competition from Alternative Piping Materials
The Singapore Plastic Pipes and Fittings Market operates under strict regulatory requirements related to construction quality, water safety, and environmental compliance. Plastic piping systems used in potable water, building services, industrial applications, and public infrastructure must comply with standards established by agencies including PUB, Building and Construction Authority (BCA), and Singapore Standards Council. Singapore’s construction sector is highly regulated, requiring manufacturers and suppliers to meet technical specifications before participating in major infrastructure projects. According to BCA statistics, Singapore’s construction demand remains supported by public infrastructure projects, residential development, and industrial facilities, increasing competition among piping solution providers. Plastic pipes compete with alternative materials such as copper, stainless steel, ductile iron, and concrete pipes depending on application requirements. Industrial users often require specialized piping systems capable of handling chemical exposure, temperature variations, and high-pressure operations. Additionally, Singapore’s environmental policies emphasize sustainable construction practices and waste reduction, requiring manufacturers to improve material efficiency and recycling capabilities. Companies operating in the market must continuously invest in certification compliance, product innovation, and technical support to address evolving customer requirements.
Market Opportunities
Smart Water Infrastructure and Digital Utility Network Development
The Singapore Plastic Pipes and Fittings Market presents opportunities from the development of smart water infrastructure, digital monitoring systems, and advanced utility networks. Singapore continues investing in technology-driven water management solutions to improve efficiency, reduce losses, and strengthen water resilience. According to PUB, Singapore’s water distribution system covers more than 6,000 kilometers of pipelines, creating opportunities for modernization, replacement, and integration of advanced monitoring technologies. The country’s Smart Nation initiative supports digital transformation across infrastructure sectors, encouraging adoption of intelligent utility systems. Plastic pipes such as HDPE and advanced polyethylene systems are suitable for smart water applications due to durability, flexibility, and compatibility with modern infrastructure designs. Singapore’s water demand is expected to remain influenced by residential, commercial, and industrial activities, particularly from manufacturing and technology sectors. The expansion of NEWater facilities, desalination infrastructure, and wastewater recycling projects creates opportunities for manufacturers supplying specialized piping solutions. Increasing adoption of sustainable infrastructure practices also encourages the use of lightweight, corrosion-resistant plastic piping systems that support long-term operational efficiency.
Expansion of Data Centers, Semiconductor Facilities, and Sustainable Industrial Infrastructure
The Singapore Plastic Pipes and Fittings Market has significant opportunities from increasing investments in data centers, semiconductor facilities, and sustainable industrial infrastructure. Singapore remains a strategic location for technology-driven industries due to its connectivity, skilled workforce, and advanced infrastructure ecosystem. According to the Singapore Economic Development Board, the electronics industry continues to be one of the country’s major manufacturing sectors, supporting demand for advanced industrial facilities. Semiconductor manufacturing plants require specialized piping networks for water management, chemical handling, and cooling systems, creating demand for high-performance thermoplastic pipes. Data center expansion also creates opportunities for plastic piping suppliers involved in cooling infrastructure, drainage systems, and utility networks. According to the Infocomm Media Development Authority, Singapore continues strengthening digital infrastructure capabilities to support cloud computing and enterprise technologies. The country’s focus on sustainable development and green buildings further supports adoption of efficient piping solutions. HDPE, PPR, and specialty plastic pipes are increasingly relevant for industrial applications requiring corrosion resistance, reliability, and reduced maintenance requirements. Expansion of technology infrastructure and advanced manufacturing facilities is expected to create additional demand opportunities for plastic pipe manufacturers and suppliers.
Future Outlook
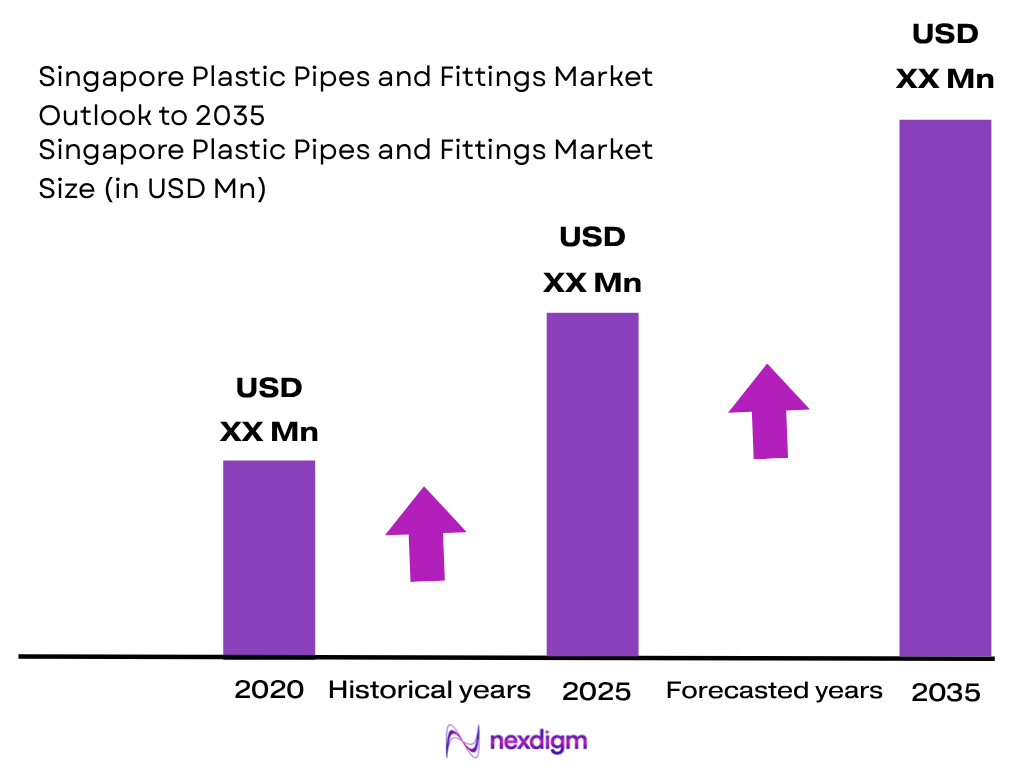
Over the next decade, the Singapore Plastic Pipes and Fittings Market is expected to experience steady expansion driven by water infrastructure modernization, industrial development, data center growth, and sustainable construction initiatives. Increasing demand for durable and corrosion-resistant piping systems will support adoption of advanced thermoplastic solutions. Expansion of NEWater infrastructure, wastewater management systems, and industrial facilities will create additional opportunities for manufacturers. The market is projected to register a CAGR of approximately ~XX% during 2026-2035.
Major Players
- Georg Fischer
- Aliaxis
- Wavin
- Uponor
- REHAU
- Sekisui Chemical
- Iplex Pipelines
- REX Pipes
- Krah Pipes
- Astral Limited
- Supreme Industries Limited
- Finolex Industries Limited
- Prince Pipes and Fittings Limited
- Dutron Group
- Hepworth PME
Key Target Audience
- Plastic Pipe and Fittings Manufacturers
- Water Utility Operators and Infrastructure Companies
- Residential and Commercial Real Estate Developers
- Industrial Manufacturing Companies
- Semiconductor and Data Center Infrastructure Operators
- Investments and Venture Capitalist Firms (Temasek Holdings, GIC Private Limited, Vertex Ventures Singapore)
- Government and Regulatory Bodies (Public Utilities Board, Building and Construction Authority, Enterprise Singapore, Singapore Economic Development Board, National Environment Agency)
- Building Material Distributors and Plumbing Contractors
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves developing an ecosystem map covering polymer suppliers, pipe manufacturers, fittings producers, distributors, contractors, utilities, and end-use industries operating within the Singapore Plastic Pipes and Fittings Market. This stage involves extensive secondary research using government publications, infrastructure databases, company information, and industry resources to identify critical variables influencing demand, supply, and market development.
Step 2: Market Analysis and Construction
In this phase, historical market information related to plastic pipe consumption, material adoption, application demand, and infrastructure requirements is analyzed. The assessment includes evaluation of water utility projects, residential construction activities, industrial investments, and commercial developments influencing plastic pipe consumption. Supply-side analysis examines manufacturing capabilities, product portfolios, and distribution structures.
Step 3: Hypothesis Validation and Expert Consultation
Market assumptions are validated through discussions with manufacturers, distributors, contractors, utility representatives, and industry professionals. These consultations provide insights into procurement practices, material preferences, regulatory requirements, and competitive dynamics. Expert inputs help refine market segmentation and validate industry trends.
Step 4: Research Synthesis and Final Output
The final stage combines insights from primary and secondary research to develop a comprehensive assessment of the Singapore Plastic Pipes and Fittings Market. Market segmentation, competitive analysis, regulatory environment, and future opportunities are evaluated to provide strategic insights for industry participants and investors.

- Executive Summary
- Research Methodology (Market Definition and Scope, Singapore Plastic Pipes and Fittings Market Classification, Thermoplastic Pipe Demand Assessment, Plastic Pipe Consumption Volume Analysis, Plastic Fittings Consumption Mapping, PVC Pipe Demand Assessment, HDPE Pipe Consumption Analysis, PPR Plumbing System Adoption Assessment, CPVC Pipe Demand Evaluation, PUB Water Supply Network Pipe Requirement Analysis, NEWater Infrastructure Pipeline Demand Assessment, Desalination Water Transmission Pipe Requirement Analysis, HDB Residential Plumbing Pipe Consumption Mapping, Commercial Construction Plumbing Demand Assessment, Industrial Process Piping Requirement Analysis, Data Center Cooling Infrastructure Pipe Demand Assessment, Marine and Offshore Piping Requirement Analysis, Electrical Conduit and Telecom Duct Demand Assessment)

- Definition and Scope
- Singapore Plastic Pipes and Fittings Industry Evolution and Development of Thermoplastic Piping Infrastructure
- PVC Pressure Pipes, PVC Drainage Pipes, CPVC Pipes, HDPE Pipes, MDPE Pipes, PPR Pipes, PE Pipes, Composite Pipes, Specialty Thermoplastic Pipes
- Singapore Plastic Pipes and Fittings Value Chain Analysis
- Singapore Plastic Pipes and Fittings Supply Chain Analysis
- Plastic Resin Supplier, Compound Manufacturer, Pipe Extruder, Fittings Manufacturer, Distributor, Contractor, Utility End User
- Plastic Pipe Integration Across PUB Water Distribution Networks, NEWater Infrastructure, Desalination Facilities, HDB Residential Plumbing Systems, Commercial Buildings, Industrial Facilities, Data Centers, Marine Infrastructure, Electrical and Telecom Networks

- Growth Drivers (PUB Water Infrastructure Modernization, NEWater Expansion, Desalination Capacity Development, HDB Residential Development, Commercial Building Construction, Data Center Infrastructure Expansion, Semiconductor Manufacturing Growth, Industrial Facility Development, Replacement of Aging Piping Systems, Increasing Adoption of Corrosion Resistant Thermoplastic Pipes)
- Market Challenges (Limited Domestic Manufacturing Base, Dependence on Imported Polymer Raw Materials, High Land and Infrastructure Development Costs, Strict Product Certification Requirements, Competition from Metal Piping Systems, Limited Market Size Due to Geographic Constraints, Installation Quality Requirements, Environmental Regulations on Plastic Waste Management)
- Market Opportunities (Smart Water Infrastructure Development, Advanced Water Recycling Systems, Data Center Cooling Infrastructure Expansion, Sustainable Building Projects, Industrial Automation Facilities, Semiconductor Manufacturing Infrastructure, Advanced HDPE and PPR Pipe Applications, Green Building Material Adoption, Digital Utility Network Development)
- Market Trends (NEWater Infrastructure Expansion, Smart Water Management Systems, Sustainable Plastic Pipe Solutions, Data Center Cooling Pipeline Demand, Large Diameter HDPE Pipe Adoption, Prefabricated Plumbing Systems, BIM-Based Pipe Design Integration, Low Carbon Construction Materials, Advanced Joining Technologies)
- Regulatory and Standards Landscape (PUB Water Supply Regulations, Singapore Standard SS Plastic Pipe Requirements, Building and Construction Authority Standards, Singapore Green Building Masterplan Requirements, Environmental Protection Regulations, Fire Safety and Shelter Department Standards, Product Certification Requirements, Construction Quality Standards)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Competition Ecosystem

- By Market Value (2020-2025)
- By Plastic Pipe Consumption Volume (2020-2025)
- By Plastic Fittings Consumption Volume (2020-2025)
- By PVC Pipe Consumption Volume (2020-2025)
- By HDPE Pipe Consumption Volume (2020-2025)
- By PPR Pipe Consumption Volume (2020-2025)
- By CPVC Pipe Consumption Volume (2020-2025)

- By Material Type (In Value %)
PVC Pipes and Fittings
CPVC Pipes and Fittings
HDPE Pipes and Fittings
MDPE Pipes and Fittings
PPR Pipes and Fittings
Polyethylene Pipes and Fittings
Composite Plastic Pipes and Fittings
PVDF and Specialty Thermoplastic Pipes - By Product Type (In Value %)
Pressure Pipes
Non-Pressure Pipes
Potable Water Pipes
Drainage Pipes
Sewerage Pipes
Corrugated Pipes
Solid Wall Pipes
Flexible Pipes and Tubing
Conduit Pipes
Telecom Ducts
Injection Molded Fittings
Fabricated Fittings
Electrofusion Fittings
Mechanical Connection Fittings - By Application Type (In Value %)
PUB Water Distribution Systems
NEWater Distribution Infrastructure
Desalination Water Transmission Systems
Residential Plumbing Systems
Commercial Building Plumbing Systems
Wastewater and Sewer Systems
Industrial Process Piping Systems
Data Center Cooling Systems
Marine and Offshore Piping Systems
Electrical Conduit Systems
Telecommunication Fiber Optic Duct Systems
Fire Protection Systems
District Cooling Systems - By End-Use Industry (In Value %)
Public Utilities and Water Infrastructure
Residential Construction Sector
Commercial Construction Sector
Industrial Manufacturing Facilities
Semiconductor Manufacturing Facilities
Data Center Infrastructure
Marine and Offshore Industry
Healthcare Facilities
Hospitality Industry
Educational Institutions
Government Infrastructure Projects
Telecommunication Infrastructure - By Joining Technology (In Value %)
Solvent Cement Joining
Rubber Ring Joining
Butt Fusion Joining
Electrofusion Joining
Socket Fusion Joining
Compression Joining
Mechanical Coupling Systems
Flanged Connection Systems
Heat Fusion Joining Systems - By Region (In Value %)
Central Region
East Region
North Region
North-East Region
West Region

- Market Share of Major Players (By Singapore Revenue, Plastic Pipe Sales Volume, Plastic Fittings Sales Volume, PVC Pipe Sales Volume, HDPE Pipe Sales Volume, PPR Pipe Sales Volume, PUB Infrastructure Exposure, Residential Plumbing Exposure, Industrial Project Exposure, Manufacturing Footprint, Distribution Network Coverage, Product Portfolio Breadth, Certification Coverage)
- Cross Comparison Parameters (Singapore Plastic Pipe and Fittings Revenue, Material Portfolio Breadth Across PVC-HDPE-PPR-CPVC, Pipe Extrusion and Fittings Manufacturing Capacity, Water Utility Project Exposure, Data Center and Industrial Application Capability, Joining Technology Portfolio and Fusion Capability, Distribution Network and Contractor Reach, Singapore Standards and Certification Coverage)
- SWOT Analysis of Major Players
- Competitive Positioning Matrix
- Detailed Profiles of Major Companies
Georg Fischer
Wavin
Aliaxis
Uponor
REHAU
Sekisui Chemical
Iplex Pipelines
REX Pipes
Krah Pipes
Astral Limited
Supreme Industries Limited
Finolex Industries Limited
Prince Pipes and Fittings Limited
Dutron Group
Hepworth PME

- PUB Water Utility Plastic Pipe Procurement Assessment
- NEWater Infrastructure Pipeline Requirement Analysis
- Residential Developer Plumbing System Material Selection Assessment
- HDB Building Plumbing Specification Analysis
- Commercial Building Plumbing Requirement Analysis
- Data Center Cooling Infrastructure Pipe Requirement Assessment
- Semiconductor Facility Process Piping Assessment
- Marine and Offshore Piping Procurement Analysis
- Industrial Facility Plastic Pipe Requirement Assessment
- Electrical Contractor Conduit Procurement Assessment
- Telecommunication Fiber Duct Installation Requirement Analysis
- Plumbing Contractor Material Preference Assessment
- Distributor Inventory and Procurement Assessment

- By Market Value (2026-2035)
- By Plastic Pipe Consumption Volume (2026-2035)
- By Plastic Fittings Consumption Volume (2026-2035)
- By PVC Pipe Consumption Volume (2026-2035)
- By HDPE Pipe Consumption Volume (2026-2035)
- By PPR Pipe Consumption Volume (2026-2035)
- By CPVC Pipe Consumption Volume (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
