
 Download PDF
Market Overview
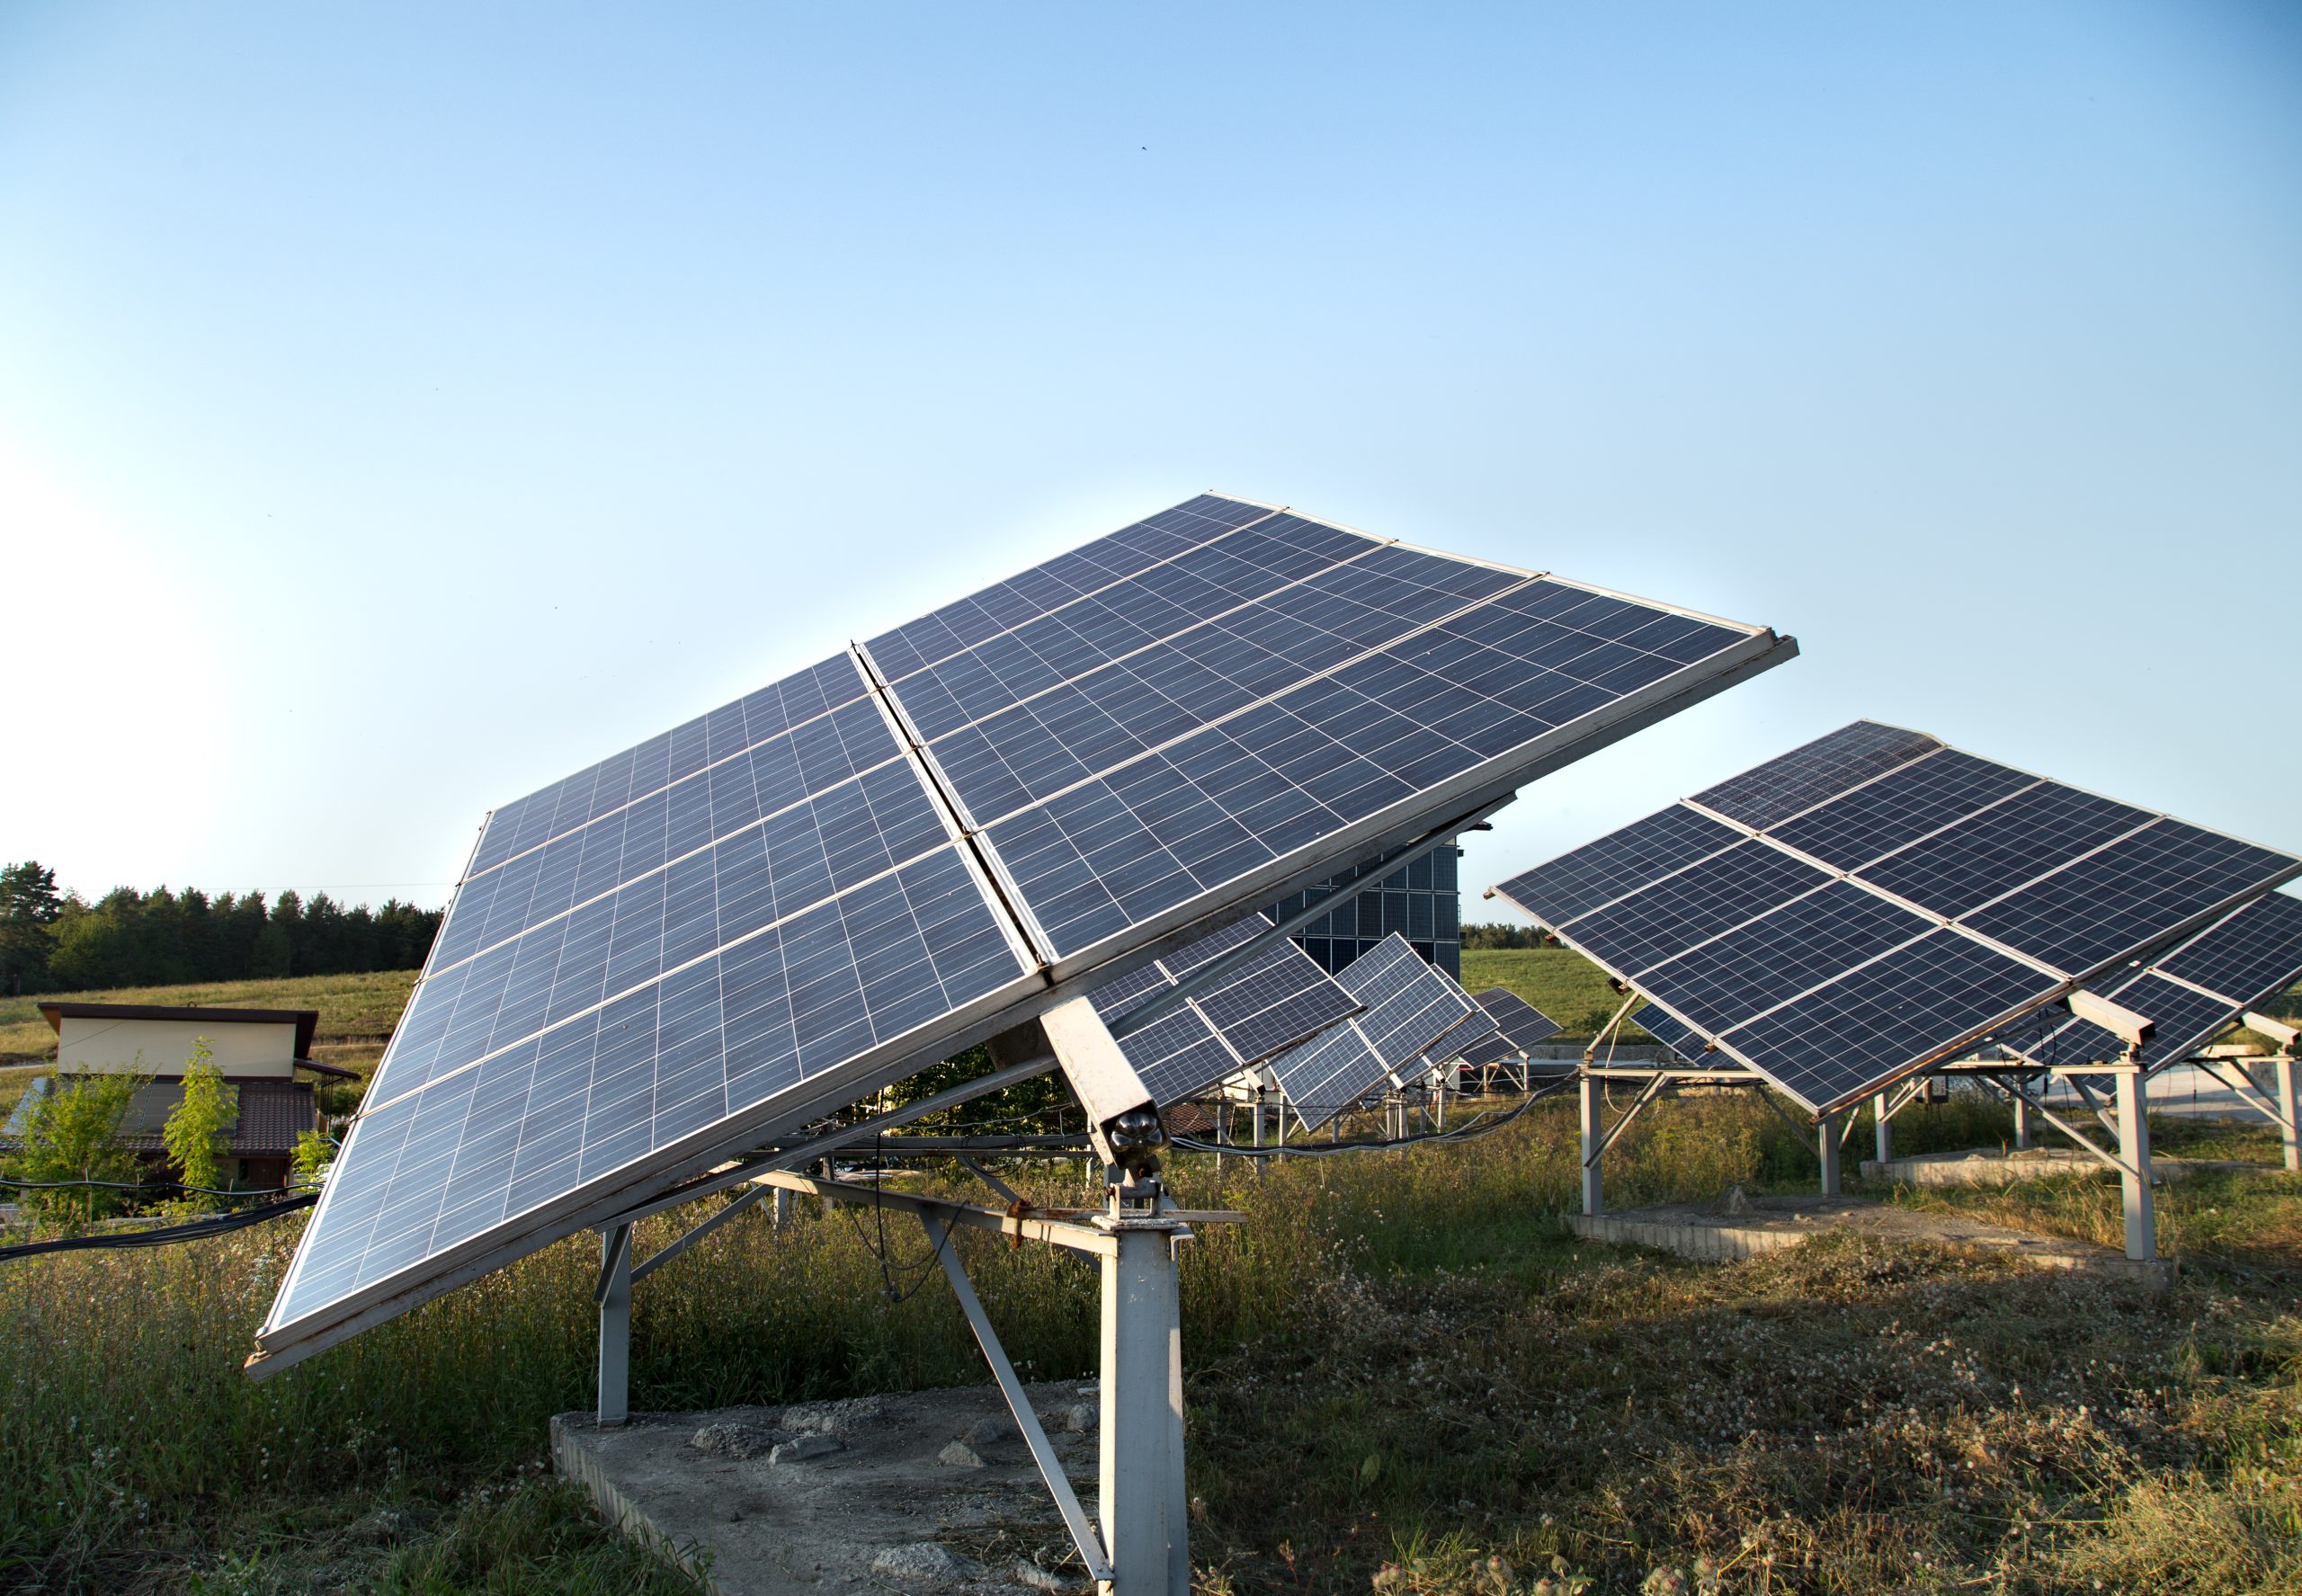
The Spanish solar PV mounting systems market is projected to reach USD 1.42 billion in 2025, expanding at an 8.4% CAGR through 2035 as the nation consolidates its position as a European leader in renewable capacity. Industrial hubs such as Seville have emerged as critical nodes for utility-scale deployment due to high irradiance levels and extensive land availability, while the region of Zaragoza serves as the primary logistical corridor for the manufacturing and distribution of steel and aluminum racking components. Demand-side momentum is driven by the rapid scaling of green hydrogen production facilities requiring dedicated solar clusters, while supply-side advancements focus on the integration of bifacial-optimized tracking mechanisms to maximize yield per square meter. Regulatory oversight by the Spanish Ministry for the Ecological Transition and the Demographic Challenge, alongside strict adherence to the Integrated National Energy and Climate Plan (PNIEC), continues to mandate higher structural integrity and longevity for mounting infrastructure. Furthermore, the industry is increasingly prioritizing circular economy principles, with major domestic players like Gonvarri Solar Steel, founded in 2017 and headquartered in Madrid, leading initiatives to implement low-carbon steel recycling processes to satisfy stringent EU Green Deal sustainability mandates and reduce the overall carbon footprint of large-scale solar installations.
By Installation Environment
- Fixed-tilt tracker systems
- Single-axis solar trackers
- Fixed-ground galvanized steel frames
- Ballasted mounting systems
- Trapezoidal sheet clamps
- Mechanically fastened rails
- Pitched roof tile hooks
- Flat roof mounting kits
- Low-profile rail interfaces
- Modular steel structure frames
- Waterproof drainage channels
- High-clearance mounting poles
By Material Composition
- Zinc-coated structural profiles
- Corrosion-resistant steel beams
- Heavy-duty wind-load bracing
- Anodized aluminium rails
- Lightweight mounting clamps
- Corrosion-resistant fasteners
- High-tensile zinc-magnesium strips
- Super-durable surface finishes
- Advanced maritime-grade coatings
- Ballasted polymer trays
- Recycled plastic mounting bases
- Lightweight floating PV anchors
Competitive Landscape
The Spanish solar PV mounting systems market exhibits high competitive intensity, driven by the aggressive targets set by the Plan Nacional Integrado de Energía y Clima (PNIEC) 2021-2030. Industry incumbents are focusing on vertical integration and the deployment of advanced tracker technologies to improve yield coefficients in high-irradiance regions like Extremadura and Andalusia. Leading manufacturers such as Soltec, headquartered in Murcia, leverage strong R&D pipelines to compete with international players like Schletter Group, focusing on modular designs that minimize installation labor costs, which rose by 14.2% in 2023 due to regulatory wage adjustments. Distribution strategies are shifting toward direct supply agreements with Tier-1 engineering, procurement, and construction (EPC) contractors to mitigate logistics volatility. Companies are increasingly adopting high-corrosion-resistant coatings and advanced geotechnical anchoring methods to meet strict environmental impact assessments mandated by the Ministerio para la Transición Ecológica y el Reto Demográfico. Competitive differentiation is now centered on the speed of deployment and the long-term reliability of single-axis tracking algorithms, with companies like STI Norland securing major utility-scale project bids through proprietary software integration.
| Company | Est. Year | Headquarters | Details | Details | Details | Details | Details | Details |
|---|---|---|---|---|---|---|---|---|
| Soltec | 2004 | Murcia, Spain | ~ | ~ | ~ | ~ | ~ | ~ |
| STI Norland | 1996 | Pamplona, Spain | ~ | ~ | ~ | ~ | ~ | ~ |
| Schletter Group | 1968 | Kirchdorf, Germany | ~ | ~ | ~ | ~ | ~ | ~ |
| Gonvarri Solar Steel | 1958 | Madrid, Spain | ~ | ~ | ~ | ~ | ~ | ~ |
| ArcelorMittal Projects | 2006 | Luxembourg City, Luxembourg | ~ | ~ | ~ | ~ | ~ | ~ |
🔒 Detailed cross-comparison data are available in the full report. Talk to Us to access complete competitive intelligence.
Growth Drivers
Industrial Decarbonization Mandates
The Spanish Ministry for the Ecological Transition and the Demographic Challenge has expedited the integration of large-scale solar arrays within industrial clusters in the Andalusia region. Companies like Gonvarri Steel Services, founded in 1958 and headquartered in Madrid, are seeing increased demand for high-durability mounting structures. In 2023, the government authorized 450 million euros in subsidies for self-consumption installations in manufacturing hubs. This initiative forces heavy industry to transition from fossil fuels to captive solar power, directly boosting the technical requirements for specialized ground-mounted aluminum and galvanized steel racking systems.
Technological Advancements in Agri-Photovoltaics
Spain has prioritized dual-use land strategies in the regions of Extremadura and Castile-La Mancha to reconcile agricultural interests with clean energy expansion. Solar Steel, a division of the Gonvarri Industries group, has deployed innovative elevated mounting systems that allow for simultaneous crop cultivation and electricity generation. By 2024, these specialized racking solutions achieved a 15 percent increase in land utility efficiency compared to fixed-tilt traditional systems. This shift addresses regional land scarcity concerns while providing farmers with additional stable income streams through long-term energy leasing agreements.
Streamlined Permitting and Grid Integration
Regulatory reforms implemented by the European Commission under the REPowerEU plan have significantly compressed the administrative timelines for solar project approvals in Spain. Local municipalities in Seville and Valencia have reduced the average permitting cycle from 24 months to 10 months as of 2023. These efficiency gains enable developers to move more mounting systems from inventory to installation sites with reduced holding costs. Consequently, regional logistics centers for suppliers like ArcelorMittal, established in 2006 and based in Asturias, report a 22 percent increase in logistical throughput for components.
High Irradiation Levels and Utility-Scale Upscaling
Spain maintains some of the highest horizontal irradiation levels in Europe, averaging 1,900 kilowatt-hours per square meter annually in the southern territories. This environmental advantage drives heavy investment in utility-scale solar farms that require robust, wind-resistant tracking systems. Major projects currently under construction in the Murcia region involve over 60,000 individual mounting units per site to maximize energy capture. Increased localized production of high-grade steel components by domestic fabricators in 2024 has further strengthened the regional supply chain, reducing reliance on imported mounting hardware from Asia.
Market Challenges
Supply Chain Volatility
Fluctuations in the price of raw steel and aluminum significantly destabilize project budgeting and hardware procurement. In 2023, spot prices for galvanized structural components rose by 18 percent, forcing many installers to renegotiate existing fixed-price contracts. This instability creates high uncertainty for mid-sized contractors struggling to maintain thin margins.
Grid Congestion Barriers
The inability of existing transmission infrastructure to handle the sudden influx of solar power prevents many shovel-ready projects from breaking ground. Approximately 12 gigawatts of installed capacity remained offline or curtailed throughout 2024 due to localized grid saturation. This bottleneck directly discourages the immediate purchase of new mounting systems for planned solar plants.
Stringent Environmental Permitting
Regulatory bodies in regions such as Catalonia and Aragon have implemented stricter land-use restrictions to protect indigenous biodiversity. During 2023, environmental impact assessments caused a 30 percent cancellation rate for proposed utility-scale installations near protected corridors. These restrictive zones limit the viable land available for the deployment of large-scale solar mounting structures.
Opportunities
Agrivoltaic Integration in Extremadura
Farmers in the Extremadura region are increasingly adopting elevated mounting structures to permit dual land use for livestock grazing and renewable energy generation. This shift allows for the dual exploitation of agricultural plots, which have seen a 14 percent increase in dual-purpose permits issued by the Spanish Ministry for the Ecological Transition during 2023. These systems must withstand wind loads specifically tested for open plains environments.
Industrial Rooftop Retrofitting in Barcelona
The dense industrial corridors surrounding Barcelona are witnessing a surge in demand for lightweight, aerodynamic ballasted mounting systems that avoid structural roof penetrations. Companies like Renusol, founded in 1997 and headquartered in Cologne, are expanding their distribution to meet the 450 megawatt demand spike identified for warehouse-scale installations in 2024. These non-penetrative solutions are critical for maintaining the building warranties of existing manufacturing facilities.
Floating PV on Reservoir Infrastructure
Expansion into water-based energy systems provides a stable solution for regional utilities operating in water-stressed areas of Southern Spain. Deployments on managed irrigation reservoirs rose to 85 megawatts in 2023, driven by specialized mounting platforms that reduce evaporation rates while generating clean electricity. Local manufacturers are currently investing in anti-corrosive HDPE modular pontoons to support the long-term integrity of these offshore-style floating structures.
Future Outlook
The Spanish solar PV mounting systems market is projected to enter a phase of sustained maturity through 2035, underpinned by the stringent requirements of the PNIEC (Plan Nacional Integrado de Energía y Clima). As Spain solidifies its position as a primary European renewable energy hub, the demand for sophisticated tracking systems and high-resilience mounting hardware will escalate to optimize generation in the Iberian climate. We anticipate a shift toward high-durability, low-maintenance materials capable of enduring the Mediterranean heat and salt-laden coastal atmospheres. The competitive landscape will consolidate around regional players like Gonvarri Solar Steel, founded in 1958 and headquartered in Madrid, and global manufacturers focusing on localized assembly to mitigate supply chain volatility. By 2030, the integration of AI-driven sun-tracking algorithms into mounting mechanicals will become standard for utility-scale projects to maximize the levelized cost of energy. Furthermore, the regulatory environment will continue to mandate higher local content requirements, incentivizing domestic production of steel components and fasteners. The synergy between grid-connected utility-scale developments and the growth of decentralized self-consumption models will provide a dual-engine trajectory for market growth. While initial infrastructure focuses on ground-mounted assets, the latter half of the decade will see increased engineering complexity as projects move toward rugged, mountainous terrain and complex hybrid hydrogen-solar configurations, ultimately defining the technical standards for the wider European market.
Major Players
- Soltec
- STI Norland
- Schletter Group
- Gonvarri Solar Steel
- ArcelorMittal Projects
- Alusín Solar
- Nclave
- ClickCon
- Mounting Systems GmbH
- K2 Systems
- Esdec
- Renusol
- Zahnen Technik
- Poleos
- Unirac
Key Target Audience
- Solar PV Mounting System Manufacturers (e.g., Gonvarri Solar Steel, founded 2015, Madrid)
- EPC Contractors (e.g., Solarpack, founded 2005, Getxo)
- Project Developers (e.g., Iberdrola Renovables, founded 2007, Bilbao)
- Government and Regulatory Bodies (Ministerio para la Transición Ecológica y el Reto Demográfico)
- Utility-Scale Power Producers (e.g., Naturgy Energy Group, founded 1843, Barcelona)
- Steel and Aluminum Component Suppliers (e.g., ArcelorMittal Spain, founded 2006, Avilés)
- Operations and Maintenance Service Providers (e.g., Grenergy Renovables, founded 2007, Madrid)
- Investors and Venture Capital Firms (e.g., Q-Energy, founded 2007, Madrid)
- Municipal Planning Authorities in Castile-La Mancha and Andalusia
- Independent Power Producers (e.g., Solaria Energía y Medio Ambiente, founded 2002, Madrid)
- International Renewable Energy Equity Funds (e.g., Bruc Energy, founded 2015, Madrid)
Research Methodology
Identification of Key Variables
- Analysts map critical market drivers such as the PNIEC (Plan Nacional Integrado de Energía y Clima) 2021-2030 targets and land-use regulations in Extremadura.
- Researchers define technical parameters like tracking system penetration and ground-mount versus rooftop structural requirements to align with current Spanish tariff structures and grid connectivity milestones.
Market Analysis and Construction
- The team aggregates production data from manufacturers like Gonvarri Solar Steel and tracks new installation capacities reported by Red Eléctrica de España.
- By cross-referencing supply chain import statistics from the Ministerio de Industria with regional project pipelines, the model constructs a bottom-up forecast for mounting system demand through 2035.
Validation and Synthesis
- Validation involves rigorous discussions with senior electrical engineers at regional distribution utilities and independent policy analysts focusing on renewable subsidies.
- Primary input is gathered from lead project managers at large-scale solar farms and regulatory compliance officers to ensure the market growth trajectories reflect actual procurement cycles and technical shift requirements.
- The final stage consolidates all quantitative datasets into a comprehensive outlook for the Spanish PV mounting market, verified against current macroeconomic headwinds.
- Findings are formatted into a strategic report detailing projected CAGR for fixed-tilt and single-axis tracker systems, ensuring alignment with the European Green Deal frameworks and national energy security mandates.
Table of Contents
 Executive Summary
2 Sections
▼
- Executive Summary
- Research Methodology (Market Definition and Scope Definition, Primary Demand-Side Expert Interviews, Supply-Side Structural Manufacturer Analysis, Regulatory Impact Evaluation (PNIEC), Top-Down Market Sizing Validation, Bottom-Up Project Pipeline Analysis, Grid Connection Capacity Mapping, Pricing Trend Data Triangulation, Geospatial Deployment Volume Modeling, Component-Level Material Cost Indexing, Historical Installation CAGR Benchmarking, Future Regulatory Forecasting Scenarios, Market Penetration Limitations Analysis)
 Spain Solar PV Mounting Systems Market Overview
7 Sections
▼
- Definition and Scope
- Market Evolution and Industry Genesis
- Iberian Peninsula Solar Irradiance Analysis
- Spanish National Integrated Energy Plan (PNIEC)
- Utility-Scale Solar Infrastructure Deployment Trends
- Regulatory Framework and Grid Connection Mandates
- Structural Engineering Standards for Mounting Systems
 Spain Solar PV Mounting Systems Market Size (2020-2025)
3 Sections
▼
- By Market Value (2020-2025)
- By Installed Capacity Megawatts (MW) (2020-2025)
- By Total Market Revenue (EUR) (2020-2025)
 Spain Solar PV Mounting Systems Market Segmentation
47 Segments
▼
- By Mounting System Architecture (In Value %)
- Fixed-Tilt Structures
- Ground-Mounted Driven Piles
- Ballasted Concrete Foundations
- Single-Pole Support Frames
- H-Beam Steel Systems
- Solar Trackers
- Single-Axis Horizontal Trackers
- Single-Axis Tilted Trackers
- Dual-Axis Tracking Systems
- Backtracking Algorithm Integration
- Roof-Integrated Solutions
- Pitched Roof Rail Systems
- Flat Roof Penetrating Mounts
- Standing Seam Metal Roof Clamps
- Lightweight Aerodynamic Tray Systems
- Specialized Infrastructure
- Agri-PV Vertical Racking
- Floating Solar Platform Anchors
- Solar Carport Steel Canopies
- Solar Noise Barrier Structures
- By Application Segment (In Value %)
- Utility-Scale Solar Parks
- Commercial and Industrial (C&I)
- Residential Rooftop Systems
- Agricultural PV Integration
- Floating Photovoltaic (FPV) Projects
- By Material Composition (In Value %)
- Galvanized Steel
- Aluminum Extrusions
- Stainless Steel Components
- Composite Polymer Structures
- By Distribution Channel (In Value %)
- Direct to EPC Contractors
- Wholesale Distributors
- System Integrator Partnerships
- Direct-to-Utility Tenders
- By Wind-Load Classification (In Value %)
- Coastal High-Wind Zones
- Inland Low-Wind Plains
- Mountainous Terrain Profiles
- By Regional Focus (In Value %)
- Andalusia Solar Clusters
- Castilla-La Mancha Development
- Extremadura Utility Projects
- Aragon Industrial Installations
- Levante Region Markets
 Spain Solar PV Mounting Systems Market Analysis
8 Sections
▼
- Growth Drivers (Industrial Decarbonization Mandates, Technological Advancements in Agri-Photovoltaics, Streamlined Permitting and Grid Integration, High Irradiation Levels and Utility-Scale Upscaling)
- Market Challenges (Supply Chain Volatility, Grid Congestion Barriers, Stringent Environmental Permitting)
- Market Opportunities (Agrivoltaic Integration in Extremadura, Industrial Rooftop Retrofitting in Barcelona, Floating PV on Reservoir Infrastructure)
- Market Trends (Bifacial Module Optimization, Agri-PV Modular Growth, Corrosion-Resistant Coating Innovation, Prefabricated Structural Components, Supply Chain Decentralization)
- Government Regulations
- SWOT Analysis
- Porter's Five Forces Analysis
- PESTLE Analysis
 Spain Solar PV Mounting Systems Market Competitive Analysis
21 Sections
▼
- Market Share of Major Players
- Domestic Manufacturers versus Chinese Importers
- Tier-1 EPC Procurement Strategy Analysis
- Utility-Scale Versus Residential Market Dynamics
- Innovation Leadership in Tracking Systems
- Supply Chain Resilience and Localization
- Specialized Structural Engineering Consulting Landscape
- Cross Comparison Parameters (Structural Wind-Tunnel Testing Validation, Corrosion Resistance Certification (ISO 9223), Installation Man-Hour Efficiency Ratio, Supply Chain Local Content Percentage, Warranty Terms for Coastal Deployments, Project-Specific Engineering Design Capacity, Digital Twin Compatibility, Structural Steel Grade Compliance)
- Competitive Product Benchmarking (Tensile Strength Metrics, Coating Thickness (Microns), Installation Tooling Requirements, Tilt Angle Adjustment Range, Module Compatibility Clamping Systems, Shipping Volume Efficiency, Weight-to-Load Capacity Ratio)
- Financial and Operational Parameters
- SWOT Analysis of Major Players
- Detailed Profiles of Major Companies
- Soltec (2004, Murcia) – SFOne, SF7, SF7 Tandem
- Gonvarri Solar Steel (2015, Madrid) – RackTrack, TrackSmart, Fixed-V
- Clavijo (1998, La Rioja) – SP-100, SP-160, Bi-axial
- Aldo (1985, Barcelona) – AluRoof, SteelGround
- ArcelorMittal Solar (2018, Asturias) – Magnelis, TerraSteel
- Exosun (Acquired by ArcelorMittal, 2018) – Exotrack HZ
- Nclave (2017, Madrid) – Monoline, Duo-Horizon
- Esdec (2004, Netherlands/Global) – FlatFix, ClickFit
- Schletter Group (1968, Germany/Spain) – FS Duo, PvMax
 Spain Solar PV Mounting Systems Market End-User Analysis
8 Sections
▼
- Utility-Scale Project Racking Intensity per MW
- Annual Maintenance and Structural Inspection Frequency
- Average Installation Time per Kilowatt-peak
- Total Cost of Ownership (TCO) Expectations
- Regional Wind-Load Foundation Requirement Variance
- Preference for Aluminum versus Steel Components
- Average Project Size per Procurement Cycle
- Retrofit Demand for Existing Solar Parks
 Spain Solar PV Mounting Systems Market Future Size (2026-2035)
3 Sections
▼
- By Market Value (2026-2035)
- By Installed Capacity Megawatts (MW) (2026-2035)
- By Total Market Revenue (EUR) (2026-2035)
Frequently Asked Questions
The current market size is USD 1.42 billion in 2025, projected to reach USD 3.19 billion by 2035. This growth represents an 8.4% CAGR from 2025 to 2035. These figures reflect the rapid expansion of utility-scale projects across the Andalusian and Extremaduran regions.
The primary catalyst is the Integrated National Energy and Climate Plan (PNIEC), which mandates aggressive renewable capacity expansion to reach climate neutrality. Increased investment in bifacial module technologies requires advanced tracking and mounting solutions to optimize energy yield. Furthermore, the stabilization of land-use regulations by regional governments in Castilla-La Mancha has accelerated project approvals.
Key market participants include Gonvarri Solar Steel, founded in 2012 and headquartered in Madrid, which specializes in high-durability tracking systems. Another prominent player is PV Hardware, established in 2011 and based in Valencia, known for its vertically integrated supply chain. Additionally, Alusín Solar, operating since 2008 from Gijón, remains a critical provider for residential and commercial rooftop mounting structures.
The industry faces substantial logistical bottlenecks and fluctuations in the cost of high-grade steel components essential for structural integrity. Grid connection delays imposed by Red Eléctrica de España frequently stall the commissioning of new large-scale projects. Furthermore, rising interest rates have tightened the capital expenditure budgets for independent power producers operating in the Iberian Peninsula.
A notable trend is the rapid adoption of artificial intelligence-driven solar trackers that dynamically adjust panel angles based on real-time atmospheric data. Agri-voltaic mounting designs are gaining significant traction, allowing dual land use for crops and solar generation in regions like Murcia. Manufacturers are also prioritizing the use of recycled aluminum alloys to comply with the European Green Deal circular economy requirements.


 Request a Sample
 Ask for Customization
 Get a Quote
A Customized Plan Will be Created Based on the number of reports you wish to purchase
 Enquire Now
