
 Download PDF
Market Overview
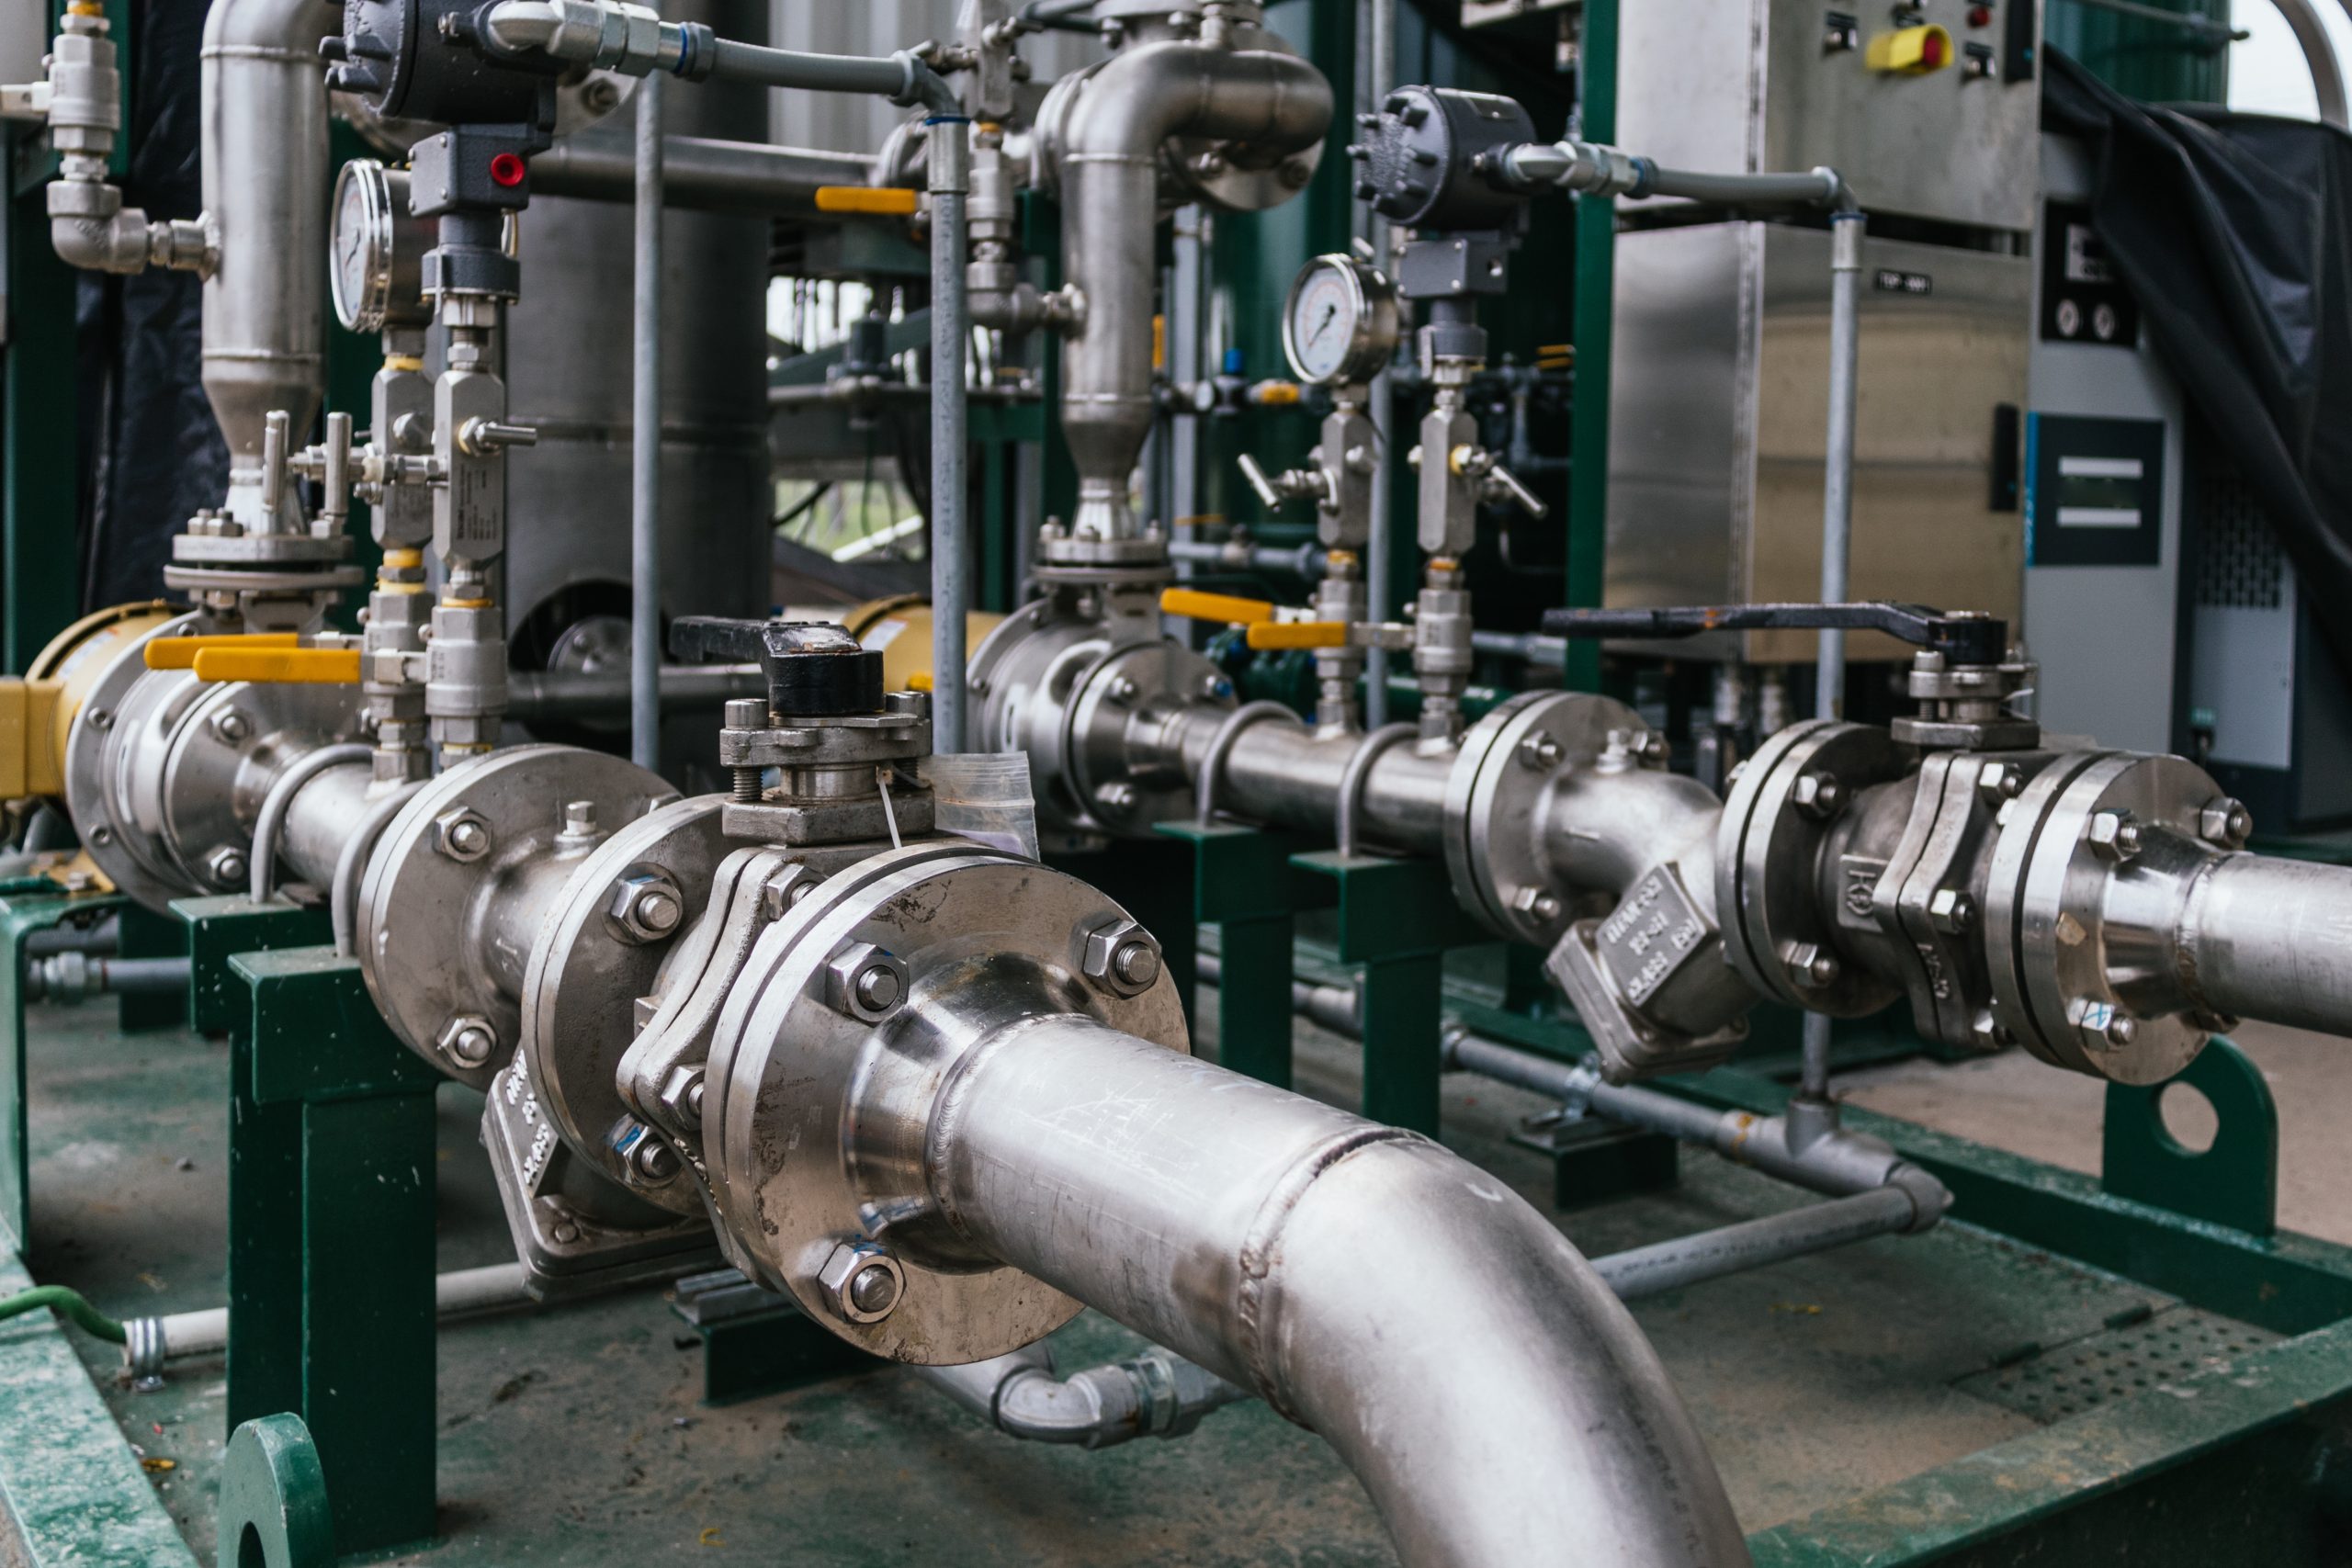
The Thailand industrial and process gas compressors market is projected to reach USD 482.4 million in 2025, expanding at a 5.4% CAGR through 2035 as the nation pivots toward advanced industrial automation. Strategic industrial hubs such as Map Ta Phut in Rayong remain central to this growth, hosting extensive petrochemical processing clusters that necessitate high-capacity centrifugal compressor systems to maintain operational throughput. Simultaneously, the Chonburi Eastern Economic Corridor continues to drive demand as the preferred destination for high-tech manufacturing, where oil-free rotary screw compressors are increasingly deployed to meet stringent clean-air requirements in semiconductor and food production lines. On the demand side, rapid adoption of predictive maintenance software allows operators to reduce downtime by 18% annually, reflecting a shift toward smarter, interconnected infrastructure. Supply-side improvements are dominated by companies like Atlas Copco, established in 1873 and headquartered in Nacka, Sweden, which is expanding its regional assembly footprint to minimize lead times for local SMEs. Furthermore, the Thailand Ministry of Industry's enforcement of the Factory Act B.E. 2535, coupled with newly tightened energy-efficiency standards, is accelerating the transition toward high-efficiency inverter-driven compressor technology to align with the national commitment to carbon neutrality by 2050.
By Compressor Technology Type
- Multi-stage high-flow systems
- API 617 compliant units
- Integrated gear drive models
- High-pressure CNG dispensers
- API 618 process units
- Oil-free piston modules
- Oil-injected industrial units
- Variable speed drive sets
- Two-stage rotary systems
- Heavy-duty gas turbines
- Refinery catalytic crackers
- Large-scale blast furnaces
By End-User Application Sector
- Hydrocracking unit compression
- Gas sweetening plant flows
- Vapor recovery systems
- Ethylene production lines
- Ammonia synthesis circuits
- Polymer extrusion air
- Pneumatic tooling systems
- Laser cutting gas supply
- Factory automation air
- Sterile nitrogen generation
- Carbonation gas delivery
- Oil-free packaging air
Competitive Landscape
The Thailand industrial and process gas compressor market is defined by high competitive intensity, dominated by multinational corporations leveraging robust after-sales service networks across the Eastern Economic Corridor. Market players are increasingly shifting from transactional hardware sales to integrated service models, incorporating IoT-enabled predictive maintenance to comply with the Industrial Estate Authority of Thailand (IEAT) safety standards. Major firms such as Atlas Copco and Ingersoll Rand are currently aggressively expanding their footprint in Rayong and Chonburi to serve the burgeoning petrochemical and electronics manufacturing sectors. Distribution strategies are characterized by a mix of direct sales for large-scale engineering, procurement, and construction (EPC) projects and localized dealer networks for mid-sized industrial end-users. Competitive strategies are currently focused on energy efficiency and carbon neutrality, with companies heavily investing in variable speed drive (VSD) technology to meet the Ministry of Energy's strict 2030 industrial energy conservation targets. Strategic acquisitions of local service partners have become the primary mechanism for maintaining market dominance in the face of increasing demand for high-pressure gas solutions in the renewable energy storage sector.
| Company | Est. Year | Headquarters | Details | Details | Details | Details | Details | Details |
|---|---|---|---|---|---|---|---|---|
| Atlas Copco Thailand | 1960 | Bangkok, Thailand | ~ | ~ | ~ | ~ | ~ | ~ |
| Ingersoll Rand (Thailand) | 1985 | Bangkok, Thailand | ~ | ~ | ~ | ~ | ~ | ~ |
| Siemens Energy Thailand | 1995 | Bangkok, Thailand | ~ | ~ | ~ | ~ | ~ | ~ |
| Burckhardt Compression AG | 1844 | Winterthur, Switzerland | ~ | ~ | ~ | ~ | ~ | ~ |
| Mitsubishi Heavy Industries Compressor | 1910 | Hiroshima, Japan | ~ | ~ | ~ | ~ | ~ | ~ |
🔒 Detailed cross-comparison data are available in the full report. Talk to Us to access complete competitive intelligence.
Growth Drivers
Expansion of the Eastern Economic Corridor (EEC)
The Thailand Board of Investment has prioritized the Eastern Economic Corridor for massive infrastructure development, triggering a surge in demand for high-capacity process gas compressors. Industrial hubs in Rayong and Chonburi now host over 450 new petrochemical and chemical processing plants as of 2023. These facilities require specialized centrifugal compressors for refinery operations and natural gas processing to meet local manufacturing goals. The government investment of 1.7 trillion baht in regional infrastructure is effectively mandating the deployment of high-efficiency, oil-free compressor technologies to ensure long-term industrial sustainability across the eastern seaboard.
Rise of Industrial Decarbonization Initiatives
Manufacturers in Thailand are increasingly adopting Carbon Capture, Utilization, and Storage technologies to align with the Thailand Greenhouse Gas Management Organization national targets. This shift necessitates the installation of sophisticated reciprocating compressors capable of handling supercritical carbon dioxide at high pressures. Specifically, 85 heavy-industry sites in the Map Ta Phut Industrial Estate have integrated advanced gas treatment systems since 2022. This transition toward greener energy management is driving local plant managers to upgrade legacy pneumatic infrastructure to precision-controlled electric compressor systems that significantly reduce annual operational energy expenditure.
Automotive Manufacturing Digital Transformation
Thailand remains a top-tier automotive production hub, with domestic output reaching 1.84 million vehicles during 2023. Companies like Toyota Motor Thailand, headquartered in Samut Prakan, are investing heavily in Industry 4.0 automation, which requires consistent, high-purity compressed air for robotic assembly lines and spray-painting units. The implementation of IoT-integrated air compressor systems allows for real-time monitoring and predictive maintenance, minimizing unplanned downtime in assembly lines. This modernization wave ensures that compressed air systems remain the backbone of precision manufacturing processes across the vast automotive supply chain network.
Advancement in Gas-to-Power Infrastructure
The Electricity Generating Authority of Thailand is rapidly transitioning toward natural gas-fired power plants to ensure grid stability as renewable energy shares fluctuate. The commissioning of the 2,500-megawatt combined-cycle power project in Chachoengsao necessitates the deployment of heavy-duty gas compressors to manage fuel pressure delivery to turbines. Reliable gas compression is critical for maintaining peak power output, especially as the nation recorded a record-high electricity peak demand of 34,827 megawatts in May 2023. Consequently, investment in robust compressor hardware is essential for maintaining the operational integrity of the national power grid.
Market Challenges
Heavy Reliance on Imported Components
Local manufacturers struggle with a significant supply chain bottleneck, as 72% of high-pressure compressor components remain sourced from overseas vendors in Germany and Japan as of 2023. This dependency leaves local operations vulnerable to global logistics disruptions and unfavorable currency exchange rate fluctuations. The resulting lead times for critical replacement parts often exceed six months.
Rising Costs of Energy Consumption
The operational expenditure for industrial facilities in Bangkok has climbed steadily, with electricity tariffs rising by 15% throughout 2023. Because large-scale compressors account for a significant portion of an industrial plant's power usage, these hikes are forcing companies to delay facility upgrades. Many smaller enterprises are choosing to repair aging, inefficient equipment rather than investing in modern, energy-saving units.
Shortage of Skilled Technical Personnel
A critical deficit exists in the technical workforce capable of maintaining advanced, smart-integrated compressor systems. Approximately 40% of manufacturing facilities report difficulties in finding specialized technicians trained in automated control systems as of 2024. This skills gap frequently leads to improper equipment maintenance and reduced operational lifespan for high-value industrial machinery.
Opportunities
Decarbonization in the Eastern Economic Corridor
Industrial plants within the Map Ta Phut Industrial Estate are increasingly shifting toward hydrogen blending and carbon capture-ready gas compression systems to meet strict emission mandates. Manufacturers now prioritize low-leakage reciprocating compressors designed to handle high-pressure hydrogen storage. The Thai Ministry of Industry approved 420 industrial modernization grants for sustainable technology adoption in 2024 to facilitate this transition.
Expansion of LNG Receiving Terminals
The projected construction of the Nong Fab LNG terminal expansion necessitates high-capacity centrifugal compressors to manage regasification throughput effectively. Equipment providers specializing in cryogenic-rated machinery are capturing new contracts as the state-run PTT Public Company Limited scales infrastructure. Recent procurement cycles allocated 85 million USD in capital expenditure for high-specification compression modules scheduled for installation by late 2026.
Smart Manufacturing and Predictive Maintenance
Regional manufacturing hubs in Rayong and Chonburi are deploying Industrial Internet of Things sensors to minimize downtime in gas-intensive processes. Integrated control panels that enable real-time vibration and thermal analysis are currently replacing legacy pneumatic monitoring systems. As of 2023, local factory automation upgrades have resulted in a 14 percent reduction in emergency maintenance costs across the electronics manufacturing sector.
Future Outlook
The Thailand industrial and process gas compressors market is poised for robust expansion through 2035, driven by the government's Thailand 4.0 policy and the intensifying push toward a circular economy. As the country solidifies its position as a regional petrochemical and automotive manufacturing hub, the demand for high-efficiency, oil-free, and digitally-integrated compression systems will witness a significant shift in technological requirements. Key market players, including Atlas Copco Thailand (founded 1999, headquartered in Bangkok) and Ingersoll Rand (founded 1871, local office in Samut Prakan), are expected to benefit from the ongoing infrastructure investments supported by the Board of Investment of Thailand. The market trajectory will be heavily influenced by the adoption of the EEC (Eastern Economic Corridor) regulatory framework, which mandates stringent energy efficiency ratings for industrial machinery. Furthermore, the integration of renewable energy sources into the industrial grid will necessitate advanced, variable-speed-drive compressors capable of handling fluctuating power inputs. Over the next decade, we anticipate that the localized manufacturing of medium-pressure centrifugal units will increase, reducing the reliance on imports from Japan and Germany. By 2030, the adoption of green hydrogen and bio-methane infrastructure projects will further diversify the revenue streams for compressor suppliers, effectively decoupling market growth from traditional reliance on crude oil processing volumes and creating a more resilient industrial landscape in the Southeast Asian corridor.
Major Players
- Atlas Copco Thailand
- Ingersoll Rand (Thailand)
- Siemens Energy Thailand
- Burckhardt Compression AG
- Mitsubishi Heavy Industries Compressor
- Kobelco Compressors
- Kaeser Kompressoren Thailand
- Gardner Denver Thailand
- Sullair Asia
- Hitachi Industrial Technology
- BOGE Kompressoren
- CP Compressors Thailand
- Sulzer Chemtech
- Hanwha Power Systems
- ELGI Equipments
Key Target Audience
- Petrochemical Manufacturers (PTT Global Chemical PCL, Rayong)
- Oil and Gas Exploration Companies (PTT Exploration and Production PCL, Bangkok)
- Food and Beverage Processors (Thai Union Group PCL, Samut Sakhon)
- Automotive Manufacturers (Toyota Motor Thailand Co. Ltd, Samut Prakan)
- Power Generation Utilities (Electricity Generating Authority of Thailand, Nonthaburi)
- Industrial Gas Distributors (Bangkok Industrial Gas Co. Ltd, Map Ta Phut)
- Pharmaceutical Manufacturers (Siam Bhechach Co. Ltd, Bangkok)
- Government and Regulatory Bodies (Department of Industrial Works, Ministry of Industry)
- Investors and Venture Capital Firms (Kasikornbank Venture Capital, Bangkok)
- HVAC and Refrigeration Engineering Contractors (Daikin Industries Thailand, Chonburi)
- Chemical Plant Facility Managers
- Compressed Air System Integrators
Research Methodology
Identification of Key Variables
- We define core market indicators including annual capital expenditure on centrifugal and reciprocating compressors within the Eastern Economic Corridor.
- Analysts map specific regulatory drivers, such as the Department of Industrial Works safety protocols, against projected GDP growth in the manufacturing sector to establish a rigorous framework for forecasting demand from 2024 to 2035.
Market Analysis and Construction
- Our team aggregates financial reports from Atlas Copco (1873, Stockholm) and Ingersoll Rand (1871, Davidson) alongside local production output data from Thai customs and tax registries.
- We develop a bottom-up model calculating market size by evaluating the current installed base of industrial compressors in Map Ta Phut and Rayong industrial estates, accounting for replacement cycles and infrastructure expansion timelines.
Validation and Synthesis
- Researchers conduct structured interviews with plant operations managers, mechanical maintenance leads at petrochemical refineries, and government regulatory compliance officers.
- These technical experts provide granular insights on operational efficiency, current technology adoption barriers, and future requirements for high-pressure gas handling systems, allowing us to validate our growth assumptions without external commercial bias or influence from any specific manufacturing enterprise or competitive brand entities.
- The final stage involves synthesizing qualitative data with quantitative forecasting to produce a comprehensive outlook through 2035.
- We perform rigorous sensitivity analysis to pressure-test the impact of regional industrial policies and energy pricing shifts on compressor market adoption, ensuring the final deliverable provides actionable strategic intelligence for stakeholders regarding future market penetration and technology trend alignment.
Table of Contents
 Executive Summary
2 Sections
▼
- Executive Summary
- Research Methodology (Defining Thailand Industrial Scope, Top-Down Macro Economic Analysis, Bottom-Up Factory Capacity Audit, EEC Industrial Zone Site Review, Petrochemical Value Chain Assessment, Supplier Interview Primary Research, EPC Contractor Procurement Profiling, Expert Panel Consensus Building, Triangulation via Trade Statistics, Compressed Air Energy Modeling, Historical Compound Growth Projection, Regional Market Limitation Scope)
 Thailand Industrial and Process Gas Compressors Market Overview
8 Sections
▼
- Definition and Scope
- Market Evolution and Industry Genesis
- Industrial Compressor Adoption in Thailand
- Process Gas Infrastructure in Rayong
- Thailand Eastern Economic Corridor Strategy
- Compressed Air Systems Energy Efficiency
- Petrochemical Sector Demand Dynamics
- Post-Pandemic Manufacturing Capacity Trends
 Thailand Industrial and Process Gas Compressors Market Size (2020-2025)
3 Sections
▼
- By Market Value (2020-2025)
- By Installed Capacity in Megawatts (2020-2025)
- By Annual Unit Sales Volume (2020-2025)
 Thailand Industrial and Process Gas Compressors Market Segmentation
44 Segments
▼
- By Product Architecture (In Value %)
- Rotary Screw Compressors
- Oil-Injected Rotary Screw
- Oil-Free Rotary Screw
- Variable Speed Drive Units
- Direct Drive Systems
- Centrifugal Compressors
- Multi-Stage Integrally Geared
- Pipeline Booster Units
- High-Flow Process Gas Models
- Reciprocating Piston Compressors
- High-Pressure CNG Refueling
- Instrument Air Systems
- Specialty Gas Compression
- Lubricated Piston Designs
- Non-Lubricated Piston Designs
- Scroll Compressors
- Medical Grade Applications
- Small-Scale Lab Compression
- Clean-Room Industrial Support
- By Application Sector (In Value %)
- Oil and Gas Refining
- Chemical and Petrochemical
- Automotive Manufacturing
- Food and Beverage Processing
- Electronics and Semiconductors
- Pharmaceutical Manufacturing
- Power Generation and Utilities
- By Pressure Range (In Value %)
- Low Pressure (Up To 10 Bar)
- Medium Pressure (10-40 Bar)
- High Pressure (Above 40 Bar)
- By Lubrication Type (In Value %)
- Oil-Lubricated
- Oil-Free/Dry
- By Drive Mechanism (In Value %)
- Fixed Speed Motor
- Variable Frequency Drive
- Engine Driven
- By Distribution Model (In Value %)
- Direct Sales To OEMs
- Authorized Regional Distributors
- EPC Contractor Procurement
- Aftermarket Service Contracts
 Thailand Industrial and Process Gas Compressors Market Analysis
8 Sections
▼
- Growth Drivers (Expansion of the Eastern Economic Corridor (EEC), Rise of Industrial Decarbonization Initiatives, Automotive Manufacturing Digital Transformation, Advancement in Gas-to-Power Infrastructure)
- Market Challenges (Heavy Reliance on Imported Components, Rising Costs of Energy Consumption, Shortage of Skilled Technical Personnel)
- Market Opportunities (Decarbonization in the Eastern Economic Corridor, Expansion of LNG Receiving Terminals, Smart Manufacturing and Predictive Maintenance)
- Market Trends (Energy Transition, Predictive Maintenance, Sustainability Compliance, Smart Factory Integration)
- Government Regulations
- SWOT Analysis
- Porter's Five Forces Analysis
- PESTLE Analysis
 Thailand Industrial and Process Gas Compressors Market Competitive Analysis
19 Sections
▼
- Market Share of Major Players
- European Premium Brand Market Penetration
- Japanese Industrial Conglomerate Dominance
- Chinese Value-Engineered Equipment Competition
- Local EPC Partnership and Procurement Trends
- Aftermarket Revenue Strategy Competition
- Cross Comparison Parameters (Regional Service Center Coverage, Energy Efficiency Rating Compliance, Mean Time Between Overhaul, IoT Connectivity Integration, Digital Twin Deployment Capability, Supply Chain Lead Time Reliability)
- Competitive Product Benchmarking (Maximum Discharge Pressure, Specific Power Consumption, Noise Level Decibel Rating, Footprint Square Meters, Air Purity ISO Certification, Thermal Management System)
- Financial and Operational Parameters
- SWOT Analysis of Major Players
- Detailed Profiles of Major Companies
- Atlas Copco (1873, Sweden) – Atlas Copco GA, Atlas Copco Z-Series, Chicago Pneumatic
- Ingersoll Rand (1859, USA) – Ingersoll Rand R-Series, Gardner Denver, CompAir
- Kobe Steel / Kobelco (1905, Japan) – Kobelco Emeraude, Kobelco SG-Series
- Mitsubishi Heavy Industries (1884, Japan) – MHI Centrifugal Process, MHI Rotary Gas
- Sullair / Hitachi (1965/1910, USA/Japan) – Sullair LS-Series, Hitachi HISCREW
- KAESER Kompressoren (1919, Germany) – Sigma Profile, Kaeser Mobilair
- Burckhardt Compression (1844, Switzerland) – Laby-Compressor, Hyper Compressor
- FS-Elliott (1962, USA) – Polaris Centrifugal, Regulus Control
 Thailand Industrial and Process Gas Compressors Market End-User Analysis
8 Sections
▼
- Energy Consumption per Cubic Meter
- Average Compressed Air Downtime Frequency
- Typical Compressor Service Interval Length
- Replacement Rate for Aged Assets
- Adoption of ISO 8573 Quality Standards
- Average Annual Compressor Maintenance Budget
- Capital Expenditure Cycles by Sector
- Preference for VFD vs Fixed Speed
 Thailand Industrial and Process Gas Compressors Market Future Size (2026-2035)
3 Sections
▼
- By Market Value (2026-2035)
- By Installed Capacity in Megawatts (2026-2035)
- By Annual Unit Sales Volume (2026-2035)
Frequently Asked Questions
The current market size is USD 0.4824 billion in 2025, projected to reach USD 0.817 billion by 2035 (5.4% CAGR from 2025 to 2035). This growth reflects the expansion of regional petrochemical hubs and the increasing demand for energy-efficient compression solutions across high-output manufacturing zones. The market valuation encompasses all pneumatic, centrifugal, and reciprocating gas compression equipment installed within industrial sites across the country.
The rapid expansion of the Eastern Economic Corridor in provinces like Rayong and Chonburi serves as the primary catalyst for market growth. Increased investment by the Ministry of Industry and the Board of Investment of Thailand in deep-sea port infrastructure and petrochemical processing plants requires significant upgrades to gas handling facilities. Furthermore, the push for cleaner industrial production standards under the 20-Year National Strategy encourages companies to replace obsolete, high-emission compressor units with modernized smart systems.
Key industry incumbents dominating the market include Atlas Copco, founded in 1873 with headquarters in Nacka, Sweden, and Ingersoll Rand, established in 1859 and headquartered in Davidson, North Carolina. Other critical participants include Kaeser Kompressoren, founded in 1919 and based in Coburg, Germany, and Mitsui E&S, founded in 1917 and headquartered in Tokyo, Japan. These corporations maintain localized distribution networks and service centers in Bangkok to support the continuous operation of Thai manufacturing facilities.
Market participants face significant hurdles related to the fluctuating cost of specialized raw materials, such as high-grade steel and advanced alloys required for rotor manufacturing. Compliance with stringent safety regulations mandated by the Department of Industrial Works necessitates frequent, capital-intensive certification processes for new compressor installations. Additionally, the limited availability of local technical labor skilled in maintaining complex oil-free, high-pressure screw compressors forces firms to rely heavily on expensive international maintenance specialists.
The most significant emerging trend is the integration of IoT-enabled remote monitoring software that allows facility managers to track real-time compressor load and energy consumption patterns. Industrial complexes in Map Ta Phut are increasingly adopting variable speed drive technologies to reduce total electricity overheads in volatile energy market conditions. There is also a notable shift toward decentralized compressed air systems, which minimize pipeline pressure drops and reduce the long-term energy footprint of integrated chemical production lines.


 Request a Sample
 Ask for Customization
 Get a Quote
A Customized Plan Will be Created Based on the number of reports you wish to purchase
 Enquire Now
