
 Download PDF
Market Overview
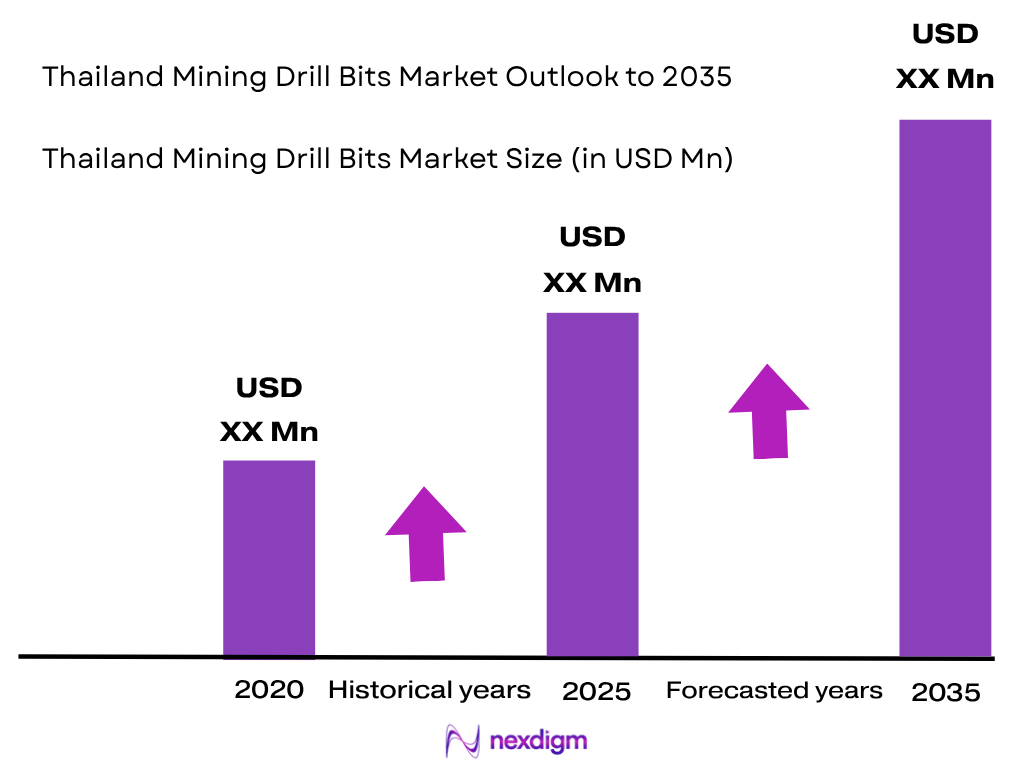
The Thailand Mining Drill Bits Market is estimated at ~USD XX million in 2024, with demand primarily linked to limestone quarrying, cement raw-material extraction, lignite mining, industrial minerals, aggregate production and mineral exploration. Thailand’s Department of Primary Industries and Mines recorded substantial 2023 mineral production, including 106.19 million tonnes of limestone for construction, 50.35 million tonnes of limestone for cement, 12.71 million tonnes of lignite, 7.00 million tonnes of gypsum, 16.17 million tonnes of industrial granite and 9.33 million tonnes of basalt. These production volumes demonstrate the scale of rock-breaking and drilling activity supporting demand for DTH, top-hammer, rotary and carbide drill bits.
Thailand’s drill-bit demand is concentrated in regions with significant limestone, cement, quarrying and industrial-mineral activity. Saraburi is particularly important because of its established limestone and cement ecosystem, while Nakhon Ratchasima, Lopburi, Kanchanaburi, Phetchaburi and Lampang support quarrying, industrial minerals and other extraction activities. DPIM statistics show the scale of Thailand’s rock and mineral base, including 106.19 million tonnes of construction limestone, 50.35 million tonnes of cement limestone, 7.00 million tonnes of gypsum, 9.84 million tonnes of shale and 1.39 million tonnes of rock salt in 2023. The country’s industrial structure also supports downstream consumption of minerals in cement, construction materials, ceramics and manufacturing.
Market Segmentation
By Drill Bit Type
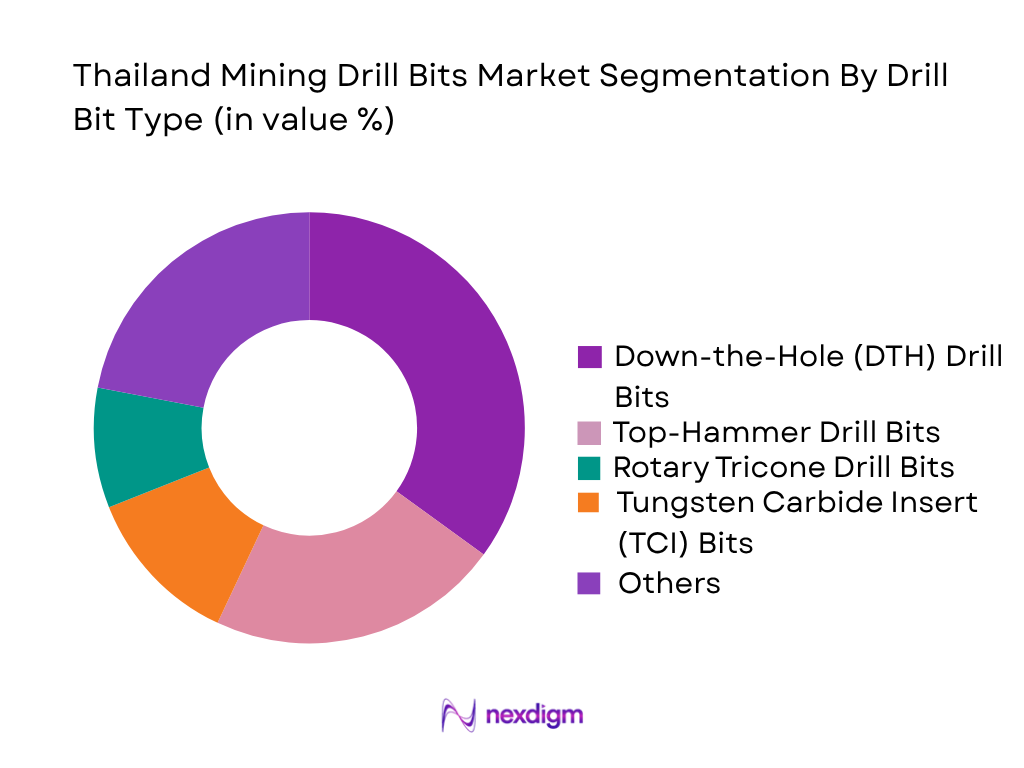
The Thailand Mining Drill Bits Market is segmented by drill bit type into Down-the-Hole (DTH) drill bits, top-hammer drill bits, rotary tricone drill bits, tungsten carbide insert (TCI) bits, milled-tooth drill bits, polycrystalline diamond compact (PDC) bits, diamond core bits, drag bits, button bits and specialty mining drill bits. DTH drill bits are positioned as the leading sub-segment because Thailand’s drilling demand is strongly connected with hard-rock quarrying, limestone extraction, aggregate production and blast-hole applications. DTH systems provide direct hammer impact at the bottom of the hole, making them suitable for hard and abrasive formations encountered in quarrying operations. Thailand produced 106.19 million tonnes of limestone for construction, 50.35 million tonnes of limestone for cement, 16.17 million tonnes of industrial granite and 9.33 million tonnes of basalt in 2023, demonstrating the scale of rock-related activity. The extensive use of drilling and blasting in quarry development, bench preparation and rock fragmentation supports recurring requirements for DTH bits and carbide cutting structures. Increasing emphasis on drilling productivity, hole accuracy and bit life is also encouraging contractors to select application-specific bit designs.
By Mining and Quarrying Application
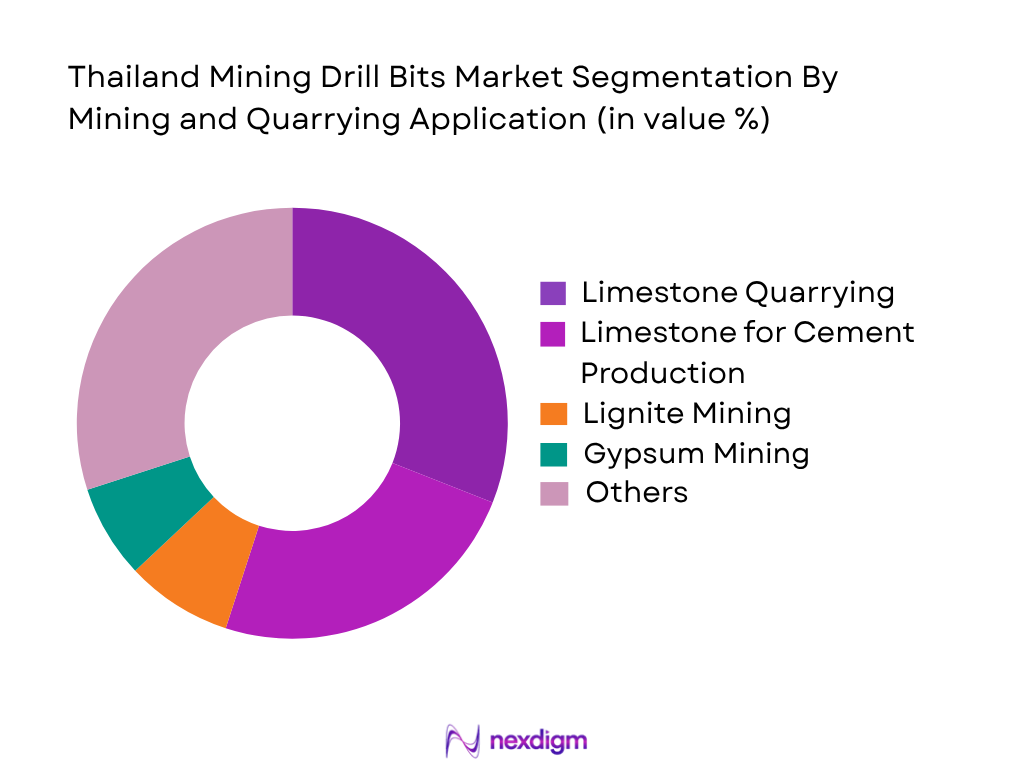
The Thailand Mining Drill Bits Market is segmented by mining and quarrying application into limestone quarrying, limestone for cement production, lignite mining, gypsum mining, rock salt mining, granite quarrying, basalt quarrying, aggregate and crushed stone production, industrial mineral extraction, and mineral exploration and geotechnical drilling. Limestone quarrying represents a major application because limestone is extensively used in construction materials and cement manufacturing, creating continuous requirements for drilling, blasting and rock fragmentation. DPIM recorded 106.19 million tonnes of limestone for construction and 50.35 million tonnes of limestone for cement in 2023. Additional production of 12.71 million tonnes of lignite, 7.00 million tonnes of gypsum, 16.17 million tonnes of industrial granite and 9.33 million tonnes of basalt further expands the addressable drilling base. Quarry operators require DTH and top-hammer systems for bench development, blast-hole drilling and controlled fragmentation, while exploration and geotechnical activities create demand for diamond core and specialized drilling products. The large volume of hard-rock materials means drill-bit wear, penetration rate and replacement intervals remain important procurement considerations for operators and contractors.
Competitive Landscape
The Thailand Mining Drill Bits Market includes international drilling-equipment and tooling companies alongside regional distributors and specialized drilling-service providers. Competition is influenced by DTH technology, carbide cutting structures, rotary drilling capabilities, diamond drilling expertise, product durability, technical support and availability of replacement bits. Global manufacturers such as Sandvik, Epiroc, Komatsu, Boart Longyear and Furukawa Rock Drill participate across drilling equipment, rock tools and mining applications, while Thailand’s extensive quarrying and cement ecosystem creates opportunities for distributors and application specialists. The competitive environment is therefore shaped not only by product portfolios but also by local inventory, contractor relationships, technical service capability and compatibility with installed drilling fleets.
| Company | Established | Headquarters | DTH Capability | Top-Hammer Capability | Rotary Drilling | Diamond Drilling | Carbide Technology | Thailand Service Presence |
| Sandvik AB | 1862 | Stockholm, Sweden | Strong | Strong | Strong | Strong | Strong | Yes |
| Epiroc AB | 2018 | Stockholm, Sweden | Strong | Strong | Strong | Strong | Strong | Yes |
| Boart Longyear Limited | 1890 | Salt Lake City, USA | Moderate | Moderate | Strong | Strong | Strong | Yes |
| Furukawa Rock Drill Co., Ltd. | 1875 | Tokyo, Japan | Strong | Strong | Strong | Moderate | Strong | Yes |
| Komatsu Ltd. | 1921 | Tokyo, Japan | Strong | Strong | Strong | Moderate | Moderate | Yes |
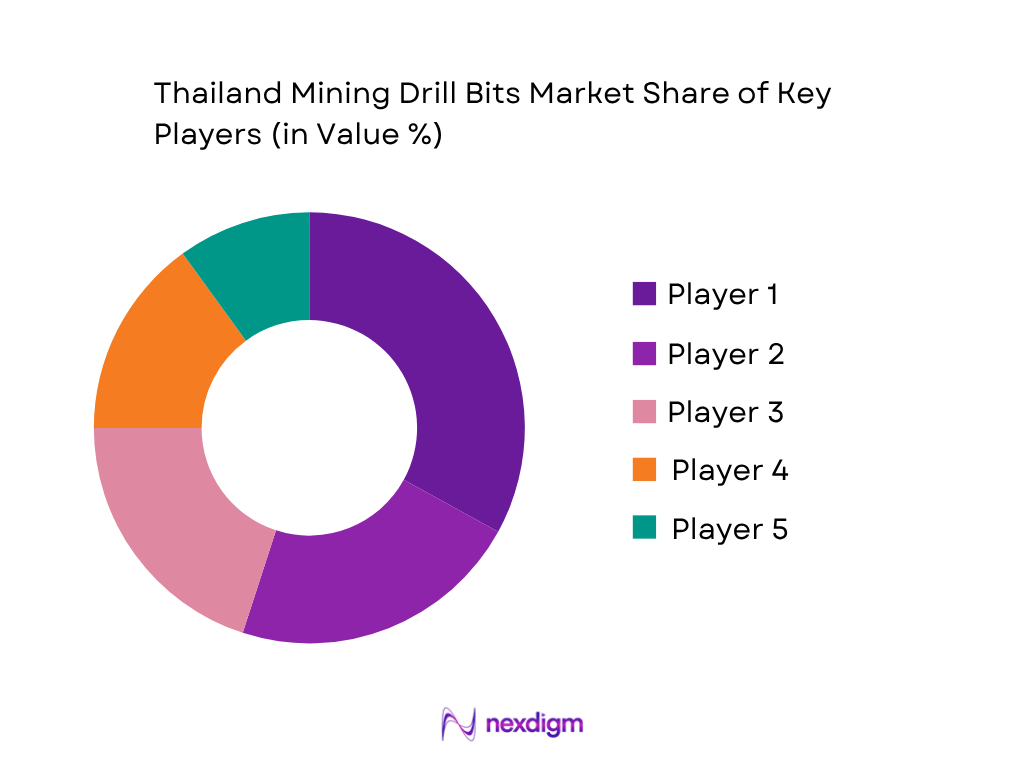
Thailand Mining Drill Bits Market Analysis
Growth Drivers
Expansion of Limestone, Cement, and Construction-Material Extraction
The Thailand Mining Drill Bits Market is strongly supported by the country’s large-scale limestone and industrial-rock extraction base, particularly because drilling and blasting are integral to quarry bench development, fragmentation and raw-material preparation. Thailand’s Department of Primary Industries and Mines recorded 106,192,264 tonnes of limestone for construction, 50,349,959 tonnes of limestone for cement, 7,948,926 tonnes of limestone for other industrial uses, 16,174,776 tonnes of industrial granite, 9,838,403 tonnes of shale, 9,329,000 tonnes of basalt, and 12,713,628 tonnes of lignite in 2024. These production volumes create recurring requirements for DTH, top-hammer and carbide-equipped drilling tools across quarrying and mining operations. The World Bank reports that industry, including construction, represented 32.1 units of Thailand’s GDP structure in 2024, demonstrating the importance of industrial and construction activity to the national economy. The IMF also reported that Thailand’s real GDP expanded by 2.5 units in 2024, while gross fixed investment remained an important component of domestic economic activity. For drill-bit suppliers, this combination of mineral extraction, construction-material production and industrial activity supports sustained requirements for drilling consumables, replacement bits, carbide buttons and application-specific rock tools.
Modernization of Mining Equipment and Industrial Drilling Operations
Modernization of quarrying and mining equipment is creating opportunities for the Thailand Mining Drill Bits Market as operators increasingly focus on drilling productivity, hole accuracy, equipment utilization and compatibility with modern drilling systems. Thailand’s industrial sector accounted for 32.1 units of GDP in 2024, while the IMF reported real GDP growth of 2.5 units and gross fixed investment growth of 0.1 units during the year, indicating continued industrial investment despite a relatively moderate investment environment. The country also maintained substantial mineral production, including 4,034,801 tonnes of dolomite, 7,004,569 tonnes of gypsum, 1,392,649 tonnes of rock salt, 16,174,776 tonnes of industrial granite, and 106,192,264 tonnes of construction limestone. Such applications require drilling systems capable of operating consistently in hard and abrasive formations. Modern drill rigs increasingly require compatible DTH hammers, button bits and engineered carbide configurations rather than standardized tools alone. The IMF has additionally identified digitalization, productivity improvement and upgrading physical infrastructure as important structural priorities for Thailand. These developments create room for suppliers offering technically optimized drill bits, reconditioning services, application engineering and drilling-performance solutions alongside conventional consumable products.
Market Challenges
Concentration of Demand in Quarrying and Industrial Minerals
The Thailand Mining Drill Bits Market faces a structural challenge because a significant portion of drilling activity is concentrated in limestone, construction materials and industrial minerals rather than being distributed across a broad range of large metallic-mining operations. DPIM data show substantial 2024 production of 106,192,264 tonnes of construction limestone, 50,349,959 tonnes of cement limestone, 16,174,776 tonnes of industrial granite, 12,713,628 tonnes of lignite, and 7,004,569 tonnes of gypsum, whereas several metallic minerals recorded comparatively limited domestic production. This concentration makes drill-bit demand particularly sensitive to quarrying, cement and construction-material activity. The IMF reported Thailand’s real GDP growth at 2.5 units in 2024 and subsequently estimated growth at 2.1 units in 2025, reflecting weaker economic momentum. For drilling-tool suppliers, slower construction or industrial activity can therefore affect quarry operating schedules, drilling volumes and replacement requirements. The IMF also identified constrained credit growth and external headwinds as factors affecting economic activity. Consequently, suppliers may face pressure to demonstrate measurable drilling productivity, longer bit life and lower downtime rather than relying solely on incremental consumable replacement.
Dependence on Imported Mining Equipment and Specialized Technologies
Dependence on imported equipment, components and advanced drilling technologies presents another challenge for the Thailand Mining Drill Bits Market, particularly for specialized DTH hammers, high-performance carbide structures, diamond tools and precision drilling systems. DPIM mineral-import statistics illustrate Thailand’s continued international sourcing of mineral-related materials: in the January–September 2024 period, imports included 4,594,809 tonnes of coal, 9,289,844 tonnes of lignite, 12,037 tonnes of manganese ore, 10,769 tonnes of tin ore, and 2,874 tonnes of zinc ore. Although these figures represent minerals rather than drill bits themselves, they demonstrate the country’s integration with international mining-material supply chains. The IMF reported Thailand’s net foreign direct investment at 2.7 units of GDP in 2024, while the World Bank reported government debt at 61.9 units of GDP. These conditions can influence investment decisions, procurement cycles and capital-equipment upgrades. Drill-bit manufacturers therefore need reliable local distribution, inventory availability and technical support to reduce exposure to international logistics disruptions. Maintaining replacement stocks and providing reconditioning or application-engineering services can become important differentiators where imported technology and overseas supply chains remain significant.
Market Opportunities
Advanced Drill Bits for Hard-Rock Quarrying and Cement Applications
The Thailand Mining Drill Bits Market presents an opportunity for manufacturers to develop application-specific products for hard-rock quarrying, cement limestone and aggregate extraction. Thailand recorded 106,192,264 tonnes of construction limestone and 50,349,959 tonnes of cement limestone in 2024, creating a substantial operating base where penetration rate, hole accuracy and wear resistance directly influence drilling productivity. Additional production of 16,174,776 tonnes of industrial granite, 9,838,403 tonnes of shale and 1,392,649 tonnes of rock salt broadens the range of formations requiring specialized drilling configurations. Suppliers can address this opportunity through DTH button profiles, optimized carbide grades, high-pressure air-flow designs and rock-specific face configurations. The opportunity extends beyond selling replacement bits because quarry operators can benefit from technical selection based on formation hardness, abrasiveness, hole diameter and drilling depth. Thailand’s industry and construction sector accounted for 32.1 units of GDP in 2024, according to the World Bank, reinforcing the connection between quarry output and downstream industrial demand. Manufacturers that combine durable drill-bit designs with field testing, performance tracking and technical support can position their products around drilling productivity rather than simply unit replacement.
Digital Drilling, Predictive Maintenance and Application Engineering
Digitalization and productivity improvement create an emerging opportunity for the Thailand Mining Drill Bits Market by enabling suppliers to combine drilling consumables with data-driven performance management. The IMF has specifically identified digitalization, productivity enhancement, physical infrastructure improvement and workforce upskilling as structural priorities for Thailand. These priorities are relevant to drilling operations because modern quarry fleets can increasingly integrate drilling parameters such as penetration rate, operating pressure, drilling time, hole depth and bit utilization into equipment-management systems. Thailand’s 2024 production base included 106,192,264 tonnes of construction limestone, 50,349,959 tonnes of cement limestone, 16,174,776 tonnes of industrial granite and 12,713,628 tonnes of lignite, giving suppliers multiple applications in which performance monitoring can be deployed. The IMF also reported that Thailand’s economy grew by 2.5 units in 2024, while private consumption and tourism supported the recovery. As industrial operators seek productivity improvements, drill-bit suppliers can expand from conventional consumable sales toward application engineering, predictive replacement, bit-condition monitoring and drilling optimization. This approach can help quarry and mining contractors reduce unplanned downtime while improving drilling consistency, particularly in repetitive blast-hole applications.
Future Outlook
Over the forecast period, the Thailand Mining Drill Bits Market is expected to remain closely connected with limestone quarrying, cement manufacturing, aggregate production, industrial minerals and infrastructure-related excavation. Continued modernization of drilling fleets is expected to support demand for high-performance DTH, top-hammer and rotary drill bits. Drill contractors are increasingly focused on penetration efficiency, hole accuracy, bit life and compatibility with automated drilling equipment. Thailand’s mineral-production base also creates opportunities for specialized carbide, diamond and exploration-drilling products. DPIM’s mineral statistics demonstrate a diversified extraction base covering limestone, gypsum, lignite, granite, basalt, shale, rock salt and other industrial minerals, supporting multiple drilling applications rather than dependence on a single commodity.
Future demand is also expected to benefit from greater adoption of digital drilling technologies, predictive maintenance, automated drill rigs and application-specific cutting structures. Suppliers capable of combining drill bits with drilling-performance monitoring and technical services can address contractor requirements beyond basic consumable supply. Thailand’s broader industrial environment remains relevant, with industry including construction accounting for 32.1% of GDP in 2024 and GDP reaching approximately USD 526.5 billion, according to World Bank data.
Major Players
- Sandvik AB
- Epiroc AB
- Boart Longyear Limited
- Komatsu Ltd.
- Furukawa Rock Drill Co., Ltd.
- Caterpillar Inc.
- Mitsubishi Materials Corporation
- Robit Plc
- Mincon Group plc
- Rockmore International
- Sumitomo Electric Industries, Ltd.
- Mitsubishi Materials Thailand Co., Ltd.
- P.V. Mining and Exploration Co., Ltd.
- Rockmaster Asia Co., Ltd.
- C. Melchers & Co. (Thailand) Ltd.
Key Target Audience
- Mining and Quarrying Companies
- Cement and Construction Material Producers
- Mining and Drilling Equipment Manufacturers
- Mining Equipment Distributors and Dealers
- Mining and Drilling Contractors
- Investments and Venture Capitalist Firms
- Government and Regulatory Bodies (Department of Primary Industries and Mines, Ministry of Industry)
- Industrial Manufacturing and Infrastructure Companies
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves constructing a Thailand-specific mining drill-bit ecosystem covering mine operators, limestone quarries, cement producers, drilling contractors, equipment distributors and drill-bit manufacturers. Key variables include mineral production, drilling intensity, blast-hole requirements, drilling methods, bit consumption, replacement cycles and equipment fleets. Particular attention is given to limestone, lignite, gypsum, granite, basalt, aggregates and industrial-mineral applications.
Step 2: Market Analysis and Construction
Historical market information is compiled through mineral-production statistics, mining and quarrying activity, import and export records, equipment deployment and application-level demand assessment. Bottom-up calculations evaluate drill-bit consumption according to drilling applications, equipment type, operating intensity and replacement requirements. Top-down validation compares calculated demand with Thailand’s broader mining, quarrying and industrial-material activity.
Step 3: Hypothesis Validation and Expert Consultation
Market hypotheses are validated through discussions with drilling contractors, quarry operators, mining-equipment distributors and technical specialists. Interviews focus on DTH and top-hammer utilization, drilling depths, rock formations, penetration rates, carbide configurations, bit life and replacement frequency. The collected operational insights are used to validate segment allocation and application-level demand assumptions.
Step 4: Research Synthesis and Final Output
The final research stage integrates secondary statistics, industry interviews, company information and demand-side assessments into a consolidated Thailand Mining Drill Bits Market model. Cross-checks are performed across drill-bit types, mining applications, customer groups and geographic areas. The final output provides historical assessment, current market structure, competitive analysis and forward-looking demand scenarios through the forecast period.

- Executive Summary
- Research Methodology (Market Definition and Scope, Thailand Mining Drill Bits Market Classification, Drill-Bit Technology Mapping, Mining and Quarrying Activity Assessment, Drill-and-Blast Application Framework, Top-Down Market Sizing, Bottom-Up Market Sizing, Production and Consumption Analysis, Demand-Side Assessment, Supply-Side Assessment, Import and Distribution Channel Assessment, Primary Industry Interviews, Data Triangulation, Forecasting Framework, Market Validation)

- Definition and Scope
- Thailand Mining Industry Evolution and Development of Limestone Quarrying, Lignite Mining, Gypsum Extraction, Rock Salt Production, Industrial Mineral Development, Granite and Basalt Quarrying, Mineral Exploration, Construction Aggregate Production, Cement Raw Material Extraction, Underground Mining Development and Mining Equipment Modernization
- Mining Drill Bits Industry Value Chain Analysis
- Mining Drill Bits Supply Chain Analysis
- Drill-Bit Manufacturers, Tungsten Carbide Suppliers, Alloy Steel Suppliers, Drill-Rod Manufacturers, DTH Hammer Suppliers, Rotary Drilling Equipment Providers, Top-Hammer Equipment Providers, Diamond Tool Manufacturers, Mining Equipment Distributors, Quarrying Contractors, Drilling Contractors, Mine Operators, Cement Producers, Industrial Mineral Producers, Construction Aggregate Producers and End-Use Industries

- Growth Drivers (High Limestone Quarrying Activity, Cement Manufacturing Demand, Construction Aggregate Consumption, Industrial Mineral Extraction, Mineral Exploration, Infrastructure Development, Quarry Modernization, Expansion of Drilling Contractors, Demand for High-Penetration Drill Bits)
- Market Challenges (Limited Large-Scale Metallic Mining Activity, Dependence on Imported Drill-Bit Technologies, Drill-Bit Wear in Abrasive Rock Formations, Fluctuating Quarrying Activity, Specialized Equipment Requirements, Skilled Drilling Operator Requirements, Replacement Cycle Variability, Equipment Compatibility Constraints, Environmental Restrictions on Mining and Quarrying, Fragmented Contractor Base)
- Market Opportunities (Advanced DTH Bit Adoption, Premium Carbide Cutting Structures, Automated Drilling Systems, Quarry Digitization, High-Efficiency Blast-Hole Drilling, Mineral Exploration Expansion, Diamond Core Drilling Services, Drill-Bit Reconditioning, Application-Specific Bit Design, Mining Equipment Localization)
- Market Trends (Increasing DTH Adoption, High-Penetration Carbide Bits, Automated Drill Rigs, Digital Drill Monitoring, Predictive Bit Replacement, Quarry Productivity Optimization, Longer-Wear Drill Tools, Precision Blast-Hole Drilling, Sustainable Mining Practices, Integrated Drilling and Crushing Operations)
- Government Regulations and Standards (Department of Primary Industries and Mines Mining Regulations, Mineral Act Requirements, Mining Lease Requirements, Environmental Impact Assessment Requirements, Mine Rehabilitation Requirements, Occupational Safety Regulations, Quarry Operating Requirements, Explosives and Blasting Regulations, Industrial Standards for Mining Equipment, Environmental Monitoring Requirements)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Mining Stakeholder Ecosystem

- By Market Value (2020-2025)
- By Drill Bit Consumption Volume (2020-2025)
- By Average Selling Price (2020-2025)
- By DTH Drill Bit Consumption Volume (2020-2025)
- By Top-Hammer Drill Bit Consumption Volume (2020-2025)
- By Rotary Drill Bit Consumption Volume (2020-2025)
- By Diamond Drill Bit Consumption Volume (2020-2025)
- By Mining and Quarrying Drilling Activity (2020-2025)
- By Mineral Production-Linked Drill Bit Demand (2020-2025)
- By Replacement and Consumable Drill Bit Demand (2020-2025)

- By Drill Bit Type (In Value %)
Down-the-Hole (DTH) Drill Bits
Top-Hammer Drill Bits
Rotary Tricone Drill Bits
Tungsten Carbide Insert (TCI) Bits
Milled-Tooth Drill Bits
Polycrystalline Diamond Compact (PDC) Bits
Diamond Core Bits
Drag Bits
Button Bits
Specialty Mining Drill Bits - By Mining and Quarrying Application (In Value %)
Limestone Quarrying
Limestone for Cement Production
Lignite Mining
Gypsum Mining
Rock Salt Mining
Granite Quarrying
Basalt Quarrying
Aggregate and Crushed Stone Production
Industrial Mineral Extraction
Mineral Exploration and Geotechnical Drilling - By End-Use Industry (In Value %)
Cement Manufacturing
Construction Aggregates
Industrial Minerals
Coal and Lignite Power Generation
Gypsum and Plaster Manufacturing
Ceramics and Glass Manufacturing
Steel and Metallurgical Applications
Infrastructure and Civil Construction
Mineral Exploration
Geotechnical and Foundation Engineering - By Bit Material and Cutting Structure (In Value %)
Tungsten Carbide Button Bits
Tungsten Carbide Insert Bits
Carburized Alloy Steel Bits
Diamond-Impregnated Bits
Surface-Set Diamond Bits
PDC Cutter Bits
Premium Carbide Cutting Structures
Hybrid Cutting Structures - By Customer Type (In Value %)
Large Mining Companies
Limestone Quarry Operators
Cement Manufacturers
Aggregate Quarry Operators
Mining Contractors
Drilling Contractors
Mineral Exploration Contractors
Industrial Mineral Producers
Construction and Geotechnical Contractors
Equipment Rental and Drilling Service Providers - By Region (In Value %)
Saraburi
Lopburi
Nakhon Ratchasima
Phetchaburi
Phichit
Lampang
Suphan Buri
Kanchanaburi
Songkhla
Other Thailand Regions

- Market Share of Major Players (By Thailand Revenue, Drill-Bit Product Portfolio, DTH Bit Capability, Top-Hammer Bit Capability, Rotary Bit Capability, Diamond Drilling Capability, Tungsten Carbide Technology, Application Coverage, Customer Base, Distribution Network, Local Service Capability, Production Capacity, Research and Development Capability, Product Innovation, Import and Supply Chain Reach)
- Cross Comparison Parameters (DTH Drill Bit Portfolio Breadth, Top-Hammer Drill Bit Technology, Rotary Tricone Bit Capability, Tungsten Carbide Grade Portfolio, Diamond Core Bit Capability, Drill-Bit Wear Life, Rock Formation Application Coverage, Thailand After-Sales and Technical Support Capability)
- SWOT Analysis of Major Players
- Competitive Positioning Matrix
- Drill-Bit Technology and Application Benchmarking
- Quarrying and Cement Industry Drill-Bit Demand Assessment
- Mining Equipment Distribution and After-Sales Service Assessment
- Detailed Profiles of Major Companies
Sandvik AB
Epiroc AB
Boart Longyear Limited
Komatsu Ltd.
Furukawa Rock Drill Co., Ltd.
Caterpillar Inc.
Mitsubishi Materials Corporation
Robit Plc
Mincon Group plc
Rockmore International
Sumitomo Electric Industries, Ltd.
Mitsubishi Materials Thailand Co., Ltd.
P.V. Mining and Exploration Co., Ltd.
Rockmaster Asia Co., Ltd.
C. Melchers & Co. (Thailand) Ltd.

- Limestone Quarry Operator Requirement Assessment
- Cement Manufacturer Drilling Requirement Analysis
- Aggregate Producer Demand Assessment
- Lignite Mining Drilling Requirement Analysis
- Gypsum Mining Equipment Requirement Assessment
- Industrial Mineral Producer Demand Analysis
- Mining Contractor Procurement Assessment
- Drilling Contractor Bit Selection Analysis
- Mineral Exploration Contractor Requirement Assessment
- Geotechnical Drilling Contractor Demand Analysis
- Blast-Hole Drilling Requirement Assessment
- DTH Hammer and Bit Compatibility Assessment
- Drill-Bit Replacement Preference Analysis
- Technical Service and After-Sales Requirement Assessment
- Procurement Criteria Analysis (Penetration Rate, Bit Life, Drilling Accuracy, Carbide Quality, Formation Compatibility, Replacement Availability, Technical Support)

- By Market Value (2026-2035)
- By Drill Bit Consumption Volume (2026-2035)
- By Average Selling Price (2026-2035)
- By DTH Drill Bit Consumption Volume (2026-2035)
- By Top-Hammer Drill Bit Consumption Volume (2026-2035)
- By Rotary Drill Bit Consumption Volume (2026-2035)
- By Diamond Drill Bit Consumption Volume (2026-2035)
- By Mining and Quarrying Drilling Activity (2026-2035)
- By Mineral Production-Linked Drill Bit Demand (2026-2035)
- By Replacement and Consumable Drill Bit Demand (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
