
 Download PDF
Market Overview
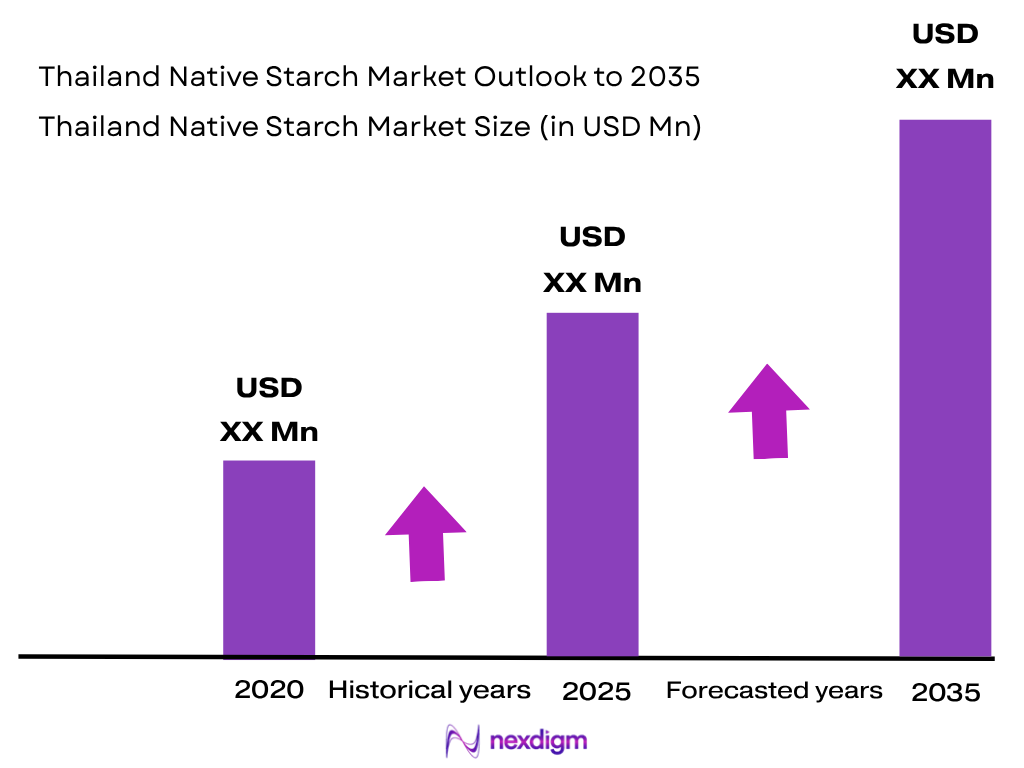
The Thailand Native Starch market is valued at approximately USD ~ bn, supported by the country’s strong cassava cultivation base, established starch processing infrastructure, and export-oriented production ecosystem. Thailand has developed a mature cassava starch industry, with native starch serving as a primary input for food processing, beverages, paper, textiles, and industrial applications. The country’s cassava processing sector includes dedicated starch facilities and downstream industries that utilize native starch for value-added applications.
Thailand Native Starch market growth is primarily driven by the dominance of cassava-based starch production, rising demand from food manufacturers, and increasing utilization in clean-label ingredient applications. Native starch production is closely linked with Thailand’s cassava supply chain, where cultivation, processing facilities, exporters, and industrial users form an integrated ecosystem. Thailand remains one of the leading global suppliers of cassava starch, with exports serving major markets including China, Indonesia, Taiwan, Malaysia, and the Philippines.
Market Segmentation
By Raw Material Type
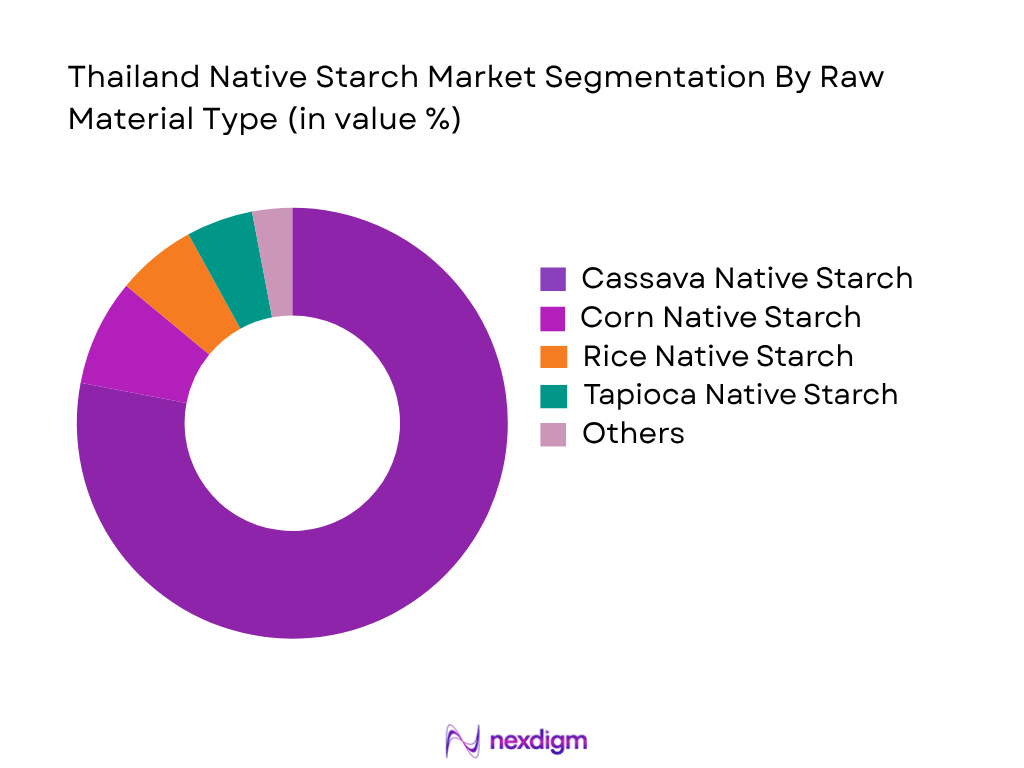
Thailand Native Starch market is segmented by raw material type into cassava native starch, corn native starch, rice native starch, potato native starch, tapioca native starch, and specialty native starches. Cassava Native Starch dominates the Thailand Native Starch market due to Thailand’s extensive cassava cultivation base, established processing infrastructure, and export-oriented starch manufacturing ecosystem. Cassava provides high starch yield and supports multiple downstream applications, including food processing, sweeteners, sauces, pharmaceuticals, paper manufacturing, and industrial products. Thailand’s cassava industry has evolved from primary cassava exports toward higher-value starch production, with native starch acting as a key intermediate product for modified starch and other applications.
By Application Type
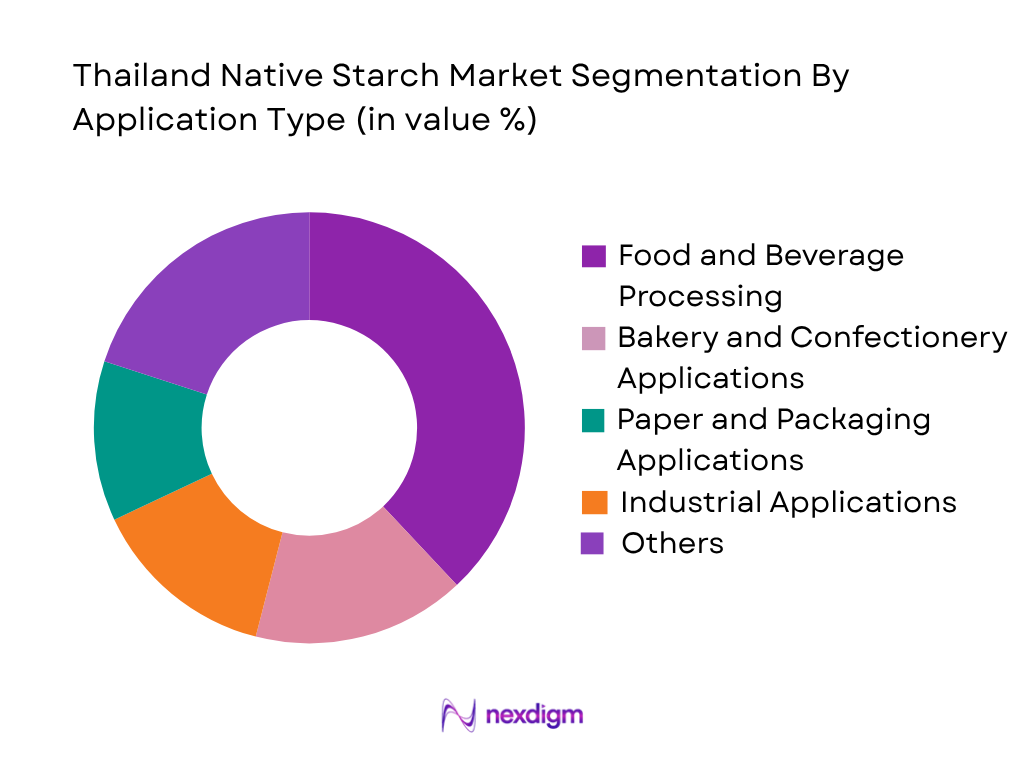
Thailand Native Starch market is segmented by application type into food and beverage processing, bakery and confectionery applications, dairy and frozen food applications, meat and processed food applications, sauces and convenience foods, pharmaceutical and nutraceutical applications, paper and packaging applications, textile and industrial applications, and animal feed applications. Food and Beverage Processing dominates the Thailand Native Starch market due to extensive utilization of native starch as a thickener, stabilizer, texture enhancer, and binding ingredient across processed food categories. Native starch is widely incorporated into sauces, beverages, bakery products, confectionery items, and convenience foods because of its functional properties and natural ingredient positioning. Growth in processed food manufacturing and demand for clean-label ingredients continues to support the adoption of native starch within food applications.
Competitive Landscape
The Thailand Native Starch market is characterized by the presence of domestic cassava starch producers and multinational ingredient companies. Thai manufacturers maintain strong positions due to access to cassava raw materials, established processing facilities, and export networks. Global starch companies participate through specialized products, technology capabilities, and international distribution channels.
| Company | Establishment Year | Headquarters | Primary Raw Material Capability | Product Portfolio | Food Application Presence | Industrial Application Presence | Export Network | Processing Capability |
| Thai Wah Public Company Limited | 1947 | Bangkok, Thailand | ~ | ~ | ~ | ~ | ~ | ~ |
| Asia Modified Starch Co., Ltd. | 1987 | Bangkok, Thailand | ~ | ~ | ~ | ~ | ~ | ~ |
| Ingredion Incorporated | 1906 | Westchester, Illinois, USA | ~ | ~ | ~ | ~ | ~ | ~ |
| Cargill Incorporated | 1865 | Minnesota, USA | ~ | ~ | ~ | ~ | ~ | ~ |
| Tate & Lyle PLC | 1921 | London, UK | ~ | ~ | ~ | ~ | ~ | ~ |
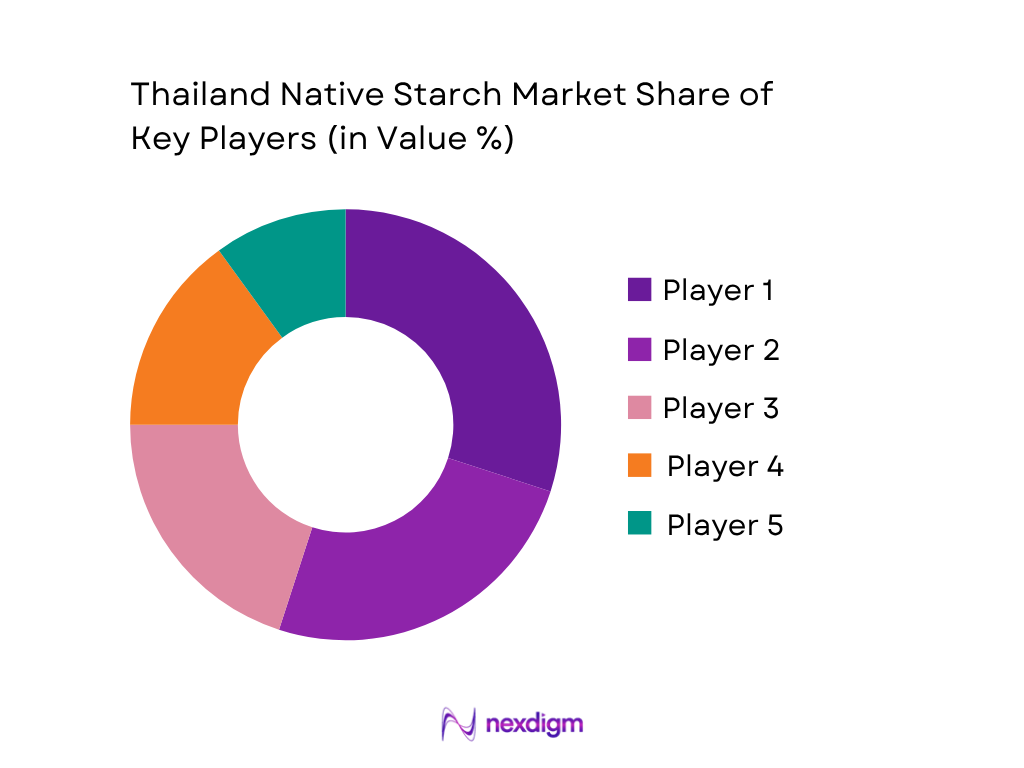
Thailand Native Starch Market Analysis
Growth Drivers
Expansion of Food Processing and Export-Oriented Manufacturing
The Thailand Native Starch Market is supported by the continuous expansion of the country’s food processing ecosystem, where native starch is widely used as a functional ingredient for improving texture, stability, viscosity, and product quality. Thailand’s food manufacturing sector benefits from its strong agricultural foundation, particularly cassava production, which provides a consistent raw material base for starch processors. According to World Bank data, Thailand’s GDP reached approximately USD 512 billion in 2024, reflecting the scale of economic activity supporting industrial manufacturing and food production investments. The country recorded agricultural value addition of around USD 40 billion, highlighting the importance of agriculture-linked industries. Thailand remains one of the world’s leading cassava producers, with annual cassava root output exceeding 30 million tonnes, supporting large-scale native starch production. The increasing requirement for starch ingredients in processed foods, beverages, bakery products, confectionery, and ready-to-eat meals is strengthening demand from domestic and export-oriented manufacturers. Additionally, Thailand exported food products worth more than USD 35 billion in recent years, creating opportunities for ingredient suppliers to serve manufacturers producing internationally competitive food products.
Rising Demand for Natural and Clean-Label Food Ingredients
The Thailand Native Starch Market is benefiting from increasing adoption of natural food ingredients as manufacturers shift toward clean-label formulations and plant-based ingredient solutions. Native starch derived from cassava, corn, rice, and other crops is increasingly preferred as a natural thickener, stabilizer, and texture enhancer across food applications. According to International Monetary Fund data, Thailand’s economy continued to expand in 2024, supported by domestic consumption and manufacturing activities, creating favourable conditions for food ingredient demand. The country recorded a population of more than 71 million people, creating a substantial consumer base for processed food, bakery, beverage, and convenience food products. Thailand’s urban population exceeded 36 million people, increasing demand for packaged and ready-to-consume food products requiring functional ingredients. The growth of plant-based food categories, gluten-free products, and natural formulations is encouraging manufacturers to incorporate native starch into product development. The increasing focus on ingredient transparency and reduced reliance on synthetic additives is expected to support the adoption of native starch solutions among food manufacturers.
Market Challenges
Dependence on Agricultural Raw Material Availability and Climate Conditions
The Thailand Native Starch Market faces challenges due to its dependence on agricultural commodities, particularly cassava, where production levels are influenced by weather conditions, farming practices, and crop cycles. Native starch manufacturers require stable raw material supply to maintain production efficiency and meet customer requirements. According to World Bank climate indicators, Thailand continues to experience climate-related risks affecting agricultural productivity, including fluctuations in rainfall patterns and temperature conditions. Thailand’s agricultural sector employs approximately 30% of the country’s workforce, making agricultural performance a significant factor influencing industrial raw material availability. Cassava cultivation is concentrated in northeastern provinces, increasing dependence on specific farming regions for starch production. Variations in crop yields can influence raw material procurement conditions and operational planning for starch processors. Additionally, farmers may shift cultivation decisions based on commodity prices, affecting long-term supply stability. Manufacturers need to strengthen farmer partnerships, improve sourcing strategies, and adopt efficient inventory management practices to reduce supply-related risks.
Competition from Modified Starch and Alternative Functional Ingredients
The Thailand Native Starch Market faces competition from modified starch products and alternative functional ingredients that provide enhanced performance characteristics for specialized applications. While native starch remains widely used due to its natural origin and cost efficiency, some food and industrial manufacturers require improved stability under temperature, acidity, and processing conditions. According to global food manufacturing trends reported by international economic institutions, processed food production continues to increase, encouraging manufacturers to seek customized ingredient solutions. Thailand’s manufacturing sector contributed more than USD 100 billion to economic output, indicating strong industrial demand for advanced ingredient technologies. Native starch producers must continuously improve product functionality and develop application-specific solutions to compete with modified starch alternatives. Regulatory requirements related to food safety, product consistency, and quality certification also create additional operational requirements for manufacturers. Companies operating in the native starch industry need to invest in processing technology, quality management systems, and product innovation to maintain competitiveness across food, pharmaceutical, and industrial applications.
Market Opportunities
Growth of Plant-Based Food and Clean-Label Product Applications
The Thailand Native Starch Market has significant opportunities through increasing demand for plant-based foods and natural ingredient formulations. Food manufacturers are expanding product portfolios involving vegetarian foods, gluten-free products, and minimally processed food categories, where native starch provides functional benefits while maintaining natural ingredient positioning. Thailand’s food processing industry continues to expand due to strong agricultural resources and export capabilities. According to World Bank data, Thailand’s merchandise exports exceeded USD 280 billion, supporting opportunities for ingredient suppliers serving export-focused manufacturers. The country’s growing urban population, exceeding 36 million people, is increasing demand for convenient food products requiring texture-enhancing ingredients. Native starch can support applications including plant-based meat alternatives, dairy alternatives, sauces, snacks, and bakery products. Manufacturers focusing on clean-label product development can utilize cassava and rice starch solutions to replace synthetic additives. The opportunity is further supported by Thailand’s established agricultural supply chain and increasing interest in sustainable, plant-derived ingredients across regional food markets.
Expansion of Specialty Starch Applications Across Pharmaceutical and Industrial Industries
The Thailand Native Starch Market presents opportunities through increasing adoption of starch-based solutions beyond traditional food applications. Native starch is gaining attention in pharmaceutical excipients, biodegradable materials, paper processing, adhesives, and other industrial applications due to its renewable and biodegradable characteristics. According to World Bank industrial indicators, Thailand maintains a diversified manufacturing sector with industrial value addition exceeding USD 100 billion, supporting demand for bio-based materials and functional ingredients. The pharmaceutical sector in Thailand continues to develop, supported by healthcare expenditure growth and increasing domestic manufacturing capabilities. Native starch can serve as a natural excipient material in tablet formulations and pharmaceutical production processes. Additionally, sustainability initiatives are encouraging industries to explore renewable alternatives to petroleum-based materials. Growth in environmentally responsible packaging and bio-based industrial solutions creates additional application opportunities for starch manufacturers. Companies developing specialty native starch grades with improved functionality can address emerging requirements from pharmaceutical, packaging, and industrial customers.
Future Outlook
The Thailand Native Starch Market is expected to experience continued expansion supported by increasing food processing activities, rising demand for natural ingredients, and Thailand’s strong agricultural supply base. The market outlook is influenced by growing adoption of clean-label starch solutions, expansion of processed food manufacturing, and increasing applications across pharmaceutical and industrial sectors. Development of specialty starch products, improvement in processing technologies, and increasing demand from export markets are expected to create additional opportunities for manufacturers. Companies are focusing on value-added starch solutions, sustainable sourcing practices, and application-specific product development to strengthen their market position.
Major Players
- Thai Wah Public Company Limited
- Asia Modified Starch Co., Ltd.
- Chaiyaphum Plant Products Co., Ltd.
- Bangkok Starch Industrial Co., Ltd.
- Sanguan Wongse Industries Co., Ltd.
- Ingredion Incorporated
- Cargill Incorporated
- Archer Daniels Midland Company (ADM)
- Tate & Lyle PLC
- Roquette Frères
- Tereos
- Agrana Beteiligungs-AG
- Emsland Group
- Avebe
- Royal Cosun
Key Target Audience
- Native Starch Manufacturers and Processing Companies
- Food and Beverage Manufacturers
- Bakery and Confectionery Product Manufacturers
- Pharmaceutical and Nutraceutical Ingredient Companies
- Paper and Packaging Manufacturing Companies
- Investments and Venture Capitalist Firms
- Government and Regulatory Bodies (Thailand Food and Drug Administration, Ministry of Agriculture and Cooperatives, Office of Industrial Economics Thailand)
- Food Ingredient Importers, Distributors, and Trading Companies
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves developing a comprehensive ecosystem map covering stakeholders operating across the Thailand Native Starch Market. This includes analysis of cassava farmers, starch processors, ingredient manufacturers, food producers, industrial users, distributors, and regulatory bodies. Secondary research is conducted to identify critical market variables including raw material availability, processing infrastructure, application demand, import-export dynamics, and industry development factors influencing market performance.
Step 2: Market Analysis and Construction
This stage focuses on analysing historical market trends, consumption patterns, production capabilities, and application-based demand across Thailand’s native starch ecosystem. The assessment includes evaluation of cassava cultivation trends, starch processing capacity, domestic consumption, export activities, and end-user industry requirements. Supply-side and demand-side indicators are integrated to develop a structured understanding of market dynamics and competitive conditions.
Step 3: Hypothesis Validation and Expert Consultation
Market assumptions are validated through discussions with industry participants including starch manufacturers, food processors, distributors, and application specialists. These interactions provide insights into production challenges, customer preferences, product innovation, procurement practices, and future demand patterns. Expert inputs are used to verify market observations and strengthen the accuracy of the analysis framework.
Step 4: Research Synthesis and Final Output
The final stage involves consolidating findings from primary and secondary research to develop a comprehensive Thailand Native Starch Market assessment. Data points related to raw material sourcing, product segmentation, application industries, competitive positioning, and future opportunities are analysed to create a detailed market intelligence report. The final output integrates market trends, strategic insights, and industry-level observations.

- Executive Summary
- Research Methodology (Market Definition and Scope, Thailand Native Starch Market Classification, Cassava Native Starch Demand Assessment, Corn Native Starch Consumption Analysis, Rice Native Starch Application Evaluation, Tapioca Native Starch Production Assessment, Native Starch Processing Capacity Mapping, Cassava Supply Chain Analysis, Food Processing Industry Demand Assessment, Bakery and Confectionery Starch Requirement Analysis, Dairy and Beverage Starch Utilization Assessment, Processed Food Starch Demand Evaluation, Pharmaceutical and Nutraceutical Starch Application Assessment, Paper and Packaging Industry Starch Consumption Analysis, Textile and Industrial Starch Application Assessment, Export Market Demand Analysis, Raw Material Availability and Pricing Assessment)

- Definition and Scope
- Thailand Native Starch Industry Evolution and Development of Cassava Cultivation, Starch Processing and Export Infrastructure
- Cassava Native Starch, Tapioca Native Starch, Corn Native Starch, Rice Native Starch, Potato Native Starch, Specialty Native Starch Varieties
- Thailand Native Starch Value Chain Analysis
- Thailand Native Starch Supply Chain Analysis
- Cassava Farmers and Agricultural Suppliers, Raw Material Aggregators, Starch Processing Companies, Refining Facilities, Food Ingredient Manufacturers, Industrial Users, Exporters, Distributors, End-Use Industries
- Native Starch Integration Across Food Processing, Bakery Products, Confectionery Products, Dairy Applications, Processed Foods, Sauces and Dressings, Meat Processing, Pharmaceutical Manufacturing, Paper Production, Textile Processing, Bio-Based Industrial Applications

- Growth Drivers (Abundant Cassava Production Base, Expansion of Food Processing Industry, Increasing Tapioca Starch Export Demand, Growth of Bakery and Confectionery Manufacturing, Rising Demand for Clean Label Ingredients, Expansion of Plant-Based Food Products, Increasing Pharmaceutical Excipient Applications, Development of Sustainable Bio-Based Ingredients)
- Market Challenges (Dependence on Cassava Crop Yield Conditions, Agricultural Commodity Price Volatility, Competition from Modified Starch Alternatives, Energy Intensive Processing Requirements, Export Market Dependency, Supply Chain Disruptions, Weather Impact on Cassava Cultivation, Regulatory Compliance Requirements)
- Market Opportunities (Expansion of Functional Food Applications, Increasing Demand for Natural Food Additives, Growth of Gluten-Free Food Manufacturing, Expansion of Plant-Based Meat and Dairy Alternatives, Sustainable Packaging Material Development, Bio-Based Industrial Material Growth, Specialty Native Starch Innovation, Increasing Regional Export Opportunities)
- Market Trends (Clean Label Ingredient Adoption, Natural Starch Preference, Non-GMO Starch Demand, Sustainable Cassava Sourcing, Premium Food Ingredient Development, Plant-Based Food Application Growth, Advanced Starch Processing Technologies, Functional Native Starch Innovation, Sustainable Industrial Ingredient Usage)
- Regulatory and Standards Landscape (Thailand Food and Drug Administration Food Ingredient Regulations, Thai Industrial Standards Requirements, Agricultural Commodity Standards, Food Safety Management System Requirements, Export Quality Standards, Halal Certification Requirements, Packaging and Labeling Standards, International Food Ingredient Compliance Requirements)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Competition Ecosystem

- By Market Value (2020-2025)
- By Native Starch Production Volume (2020-2025)
- By Native Starch Consumption Volume (2020-2025)
- By Cassava Native Starch Production Volume (2020-2025)
- By Tapioca Native Starch Export Volume (2020-2025)
- By Rice Native Starch Consumption Volume (2020-2025)
- By Corn Native Starch Consumption Volume (2020-2025)
- By Food Processing Industry Native Starch Consumption Volume (2020-2025)

- By Raw Material Type (In Value %)
Cassava Native Starch
Corn Native Starch
Rice Native Starch
Potato Native Starch
Tapioca Native Starch
Other Specialty Native Starches - By Application Type (In Value %)
Food and Beverage Processing
Bakery and Confectionery Applications
Dairy and Frozen Food Applications
Meat and Processed Food Applications
Sauces, Dressings and Convenience Foods
Pharmaceutical and Nutraceutical Applications
Paper and Packaging Applications
Textile and Industrial Applications
Animal Feed Applications
Bio-Based Industrial Applications - By Functionality Type (In Value %)
Thickening Starch
Binding Starch
Gelling Starch
Stabilizing Starch
Texture Enhancement Starch
Moisture Retention Starch
Film Forming Starch
Coating and Surface Treatment Starch - By End-Use Industry (In Value %)
Food Manufacturing Industry
Beverage Industry
Bakery Industry
Confectionery Industry
Dairy Processing Industry
Pharmaceutical Industry
Nutraceutical Industry
Paper Manufacturing Industry
Textile Industry
Chemical and Industrial Processing Industry - By Distribution Channel (In Value %)
Direct Manufacturer Supply
Food Ingredient Distributors
Industrial Ingredient Distributors
Export Trading Companies
Wholesale Distribution Channels
Specialty Ingredient Suppliers
Online Ingredient Platforms
Contract Manufacturing Supply Networks - By Region (In Value %)
Northern Thailand
Northeastern Thailand
Central Thailand
Eastern Thailand
Western Thailand
Southern Thailand

- Market Share of Major Players (By Thailand Revenue, Native Starch Production Volume, Cassava Starch Sales Volume, Tapioca Starch Export Volume, Food Application Exposure, Industrial Application Exposure, Processing Capacity, Manufacturing Facility Network, Distribution Network Coverage, Product Portfolio Breadth, Customer Industry Coverage, Certification Coverage)
- Cross Comparison Parameters (Native Starch Revenue, Cassava Processing Capability, Native Starch Production Capacity, Export Market Reach, Food Application Portfolio Breadth, Industrial Application Capability, Advanced Starch Processing Technology, Food Safety and Sustainability Certification Coverage)
- SWOT Analysis of Major Players
- Competitive Positioning Matrix
- Native Starch Product Portfolio and Application Benchmarking
- Cassava Processing, Extraction, Refining and Drying Technology Assessment
- Detailed Profiles of Major Companies
Thai Wah Public Company Limited
Asia Modified Starch Co., Ltd.
Tate & Lyle PLC
Ingredion Incorporated
Cargill Incorporated
Archer Daniels Midland Company (ADM)
Roquette Frères
Tereos
Emsland Group
Avebe
Royal Cosun
Kerry Group
Global Bio-Chem Technology Group Company Limited
Chaiyaphum Plant Products Co., Ltd.
Sunshine International Co., Ltd.

- Food Manufacturer Native Starch Procurement Assessment
- Bakery Product Manufacturer Ingredient Requirement Analysis
- Confectionery Manufacturer Starch Application Assessment
- Dairy Processing Industry Texture Ingredient Analysis
- Beverage Manufacturer Stabilizer Requirement Analysis
- Processed Food Manufacturer Binding Ingredient Assessment
- Pharmaceutical Manufacturer Excipient Requirement Analysis
- Nutraceutical Industry Starch Application Assessment
- Paper Manufacturing Industry Starch Consumption Analysis
- Textile Industry Starch Application Assessment
- Industrial Manufacturer Bio-Based Ingredient Assessment
- Export-Oriented Food Processor Procurement Analysis
- Ingredient Distributor Inventory and Procurement Assessment

- By Market Value (2026-2035)
- By Native Starch Production Volume (2026-2035)
- By Native Starch Consumption Volume (2026-2035)
- By Cassava Native Starch Production Volume (2026-2035)
- By Tapioca Native Starch Export Volume (2026-2035)
- By Rice Native Starch Consumption Volume (2026-2035)
- By Corn Native Starch Consumption Volume (2026-2035)
- By Food Processing Industry Native Starch Consumption Volume (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
