
 Download PDF
Market Overview
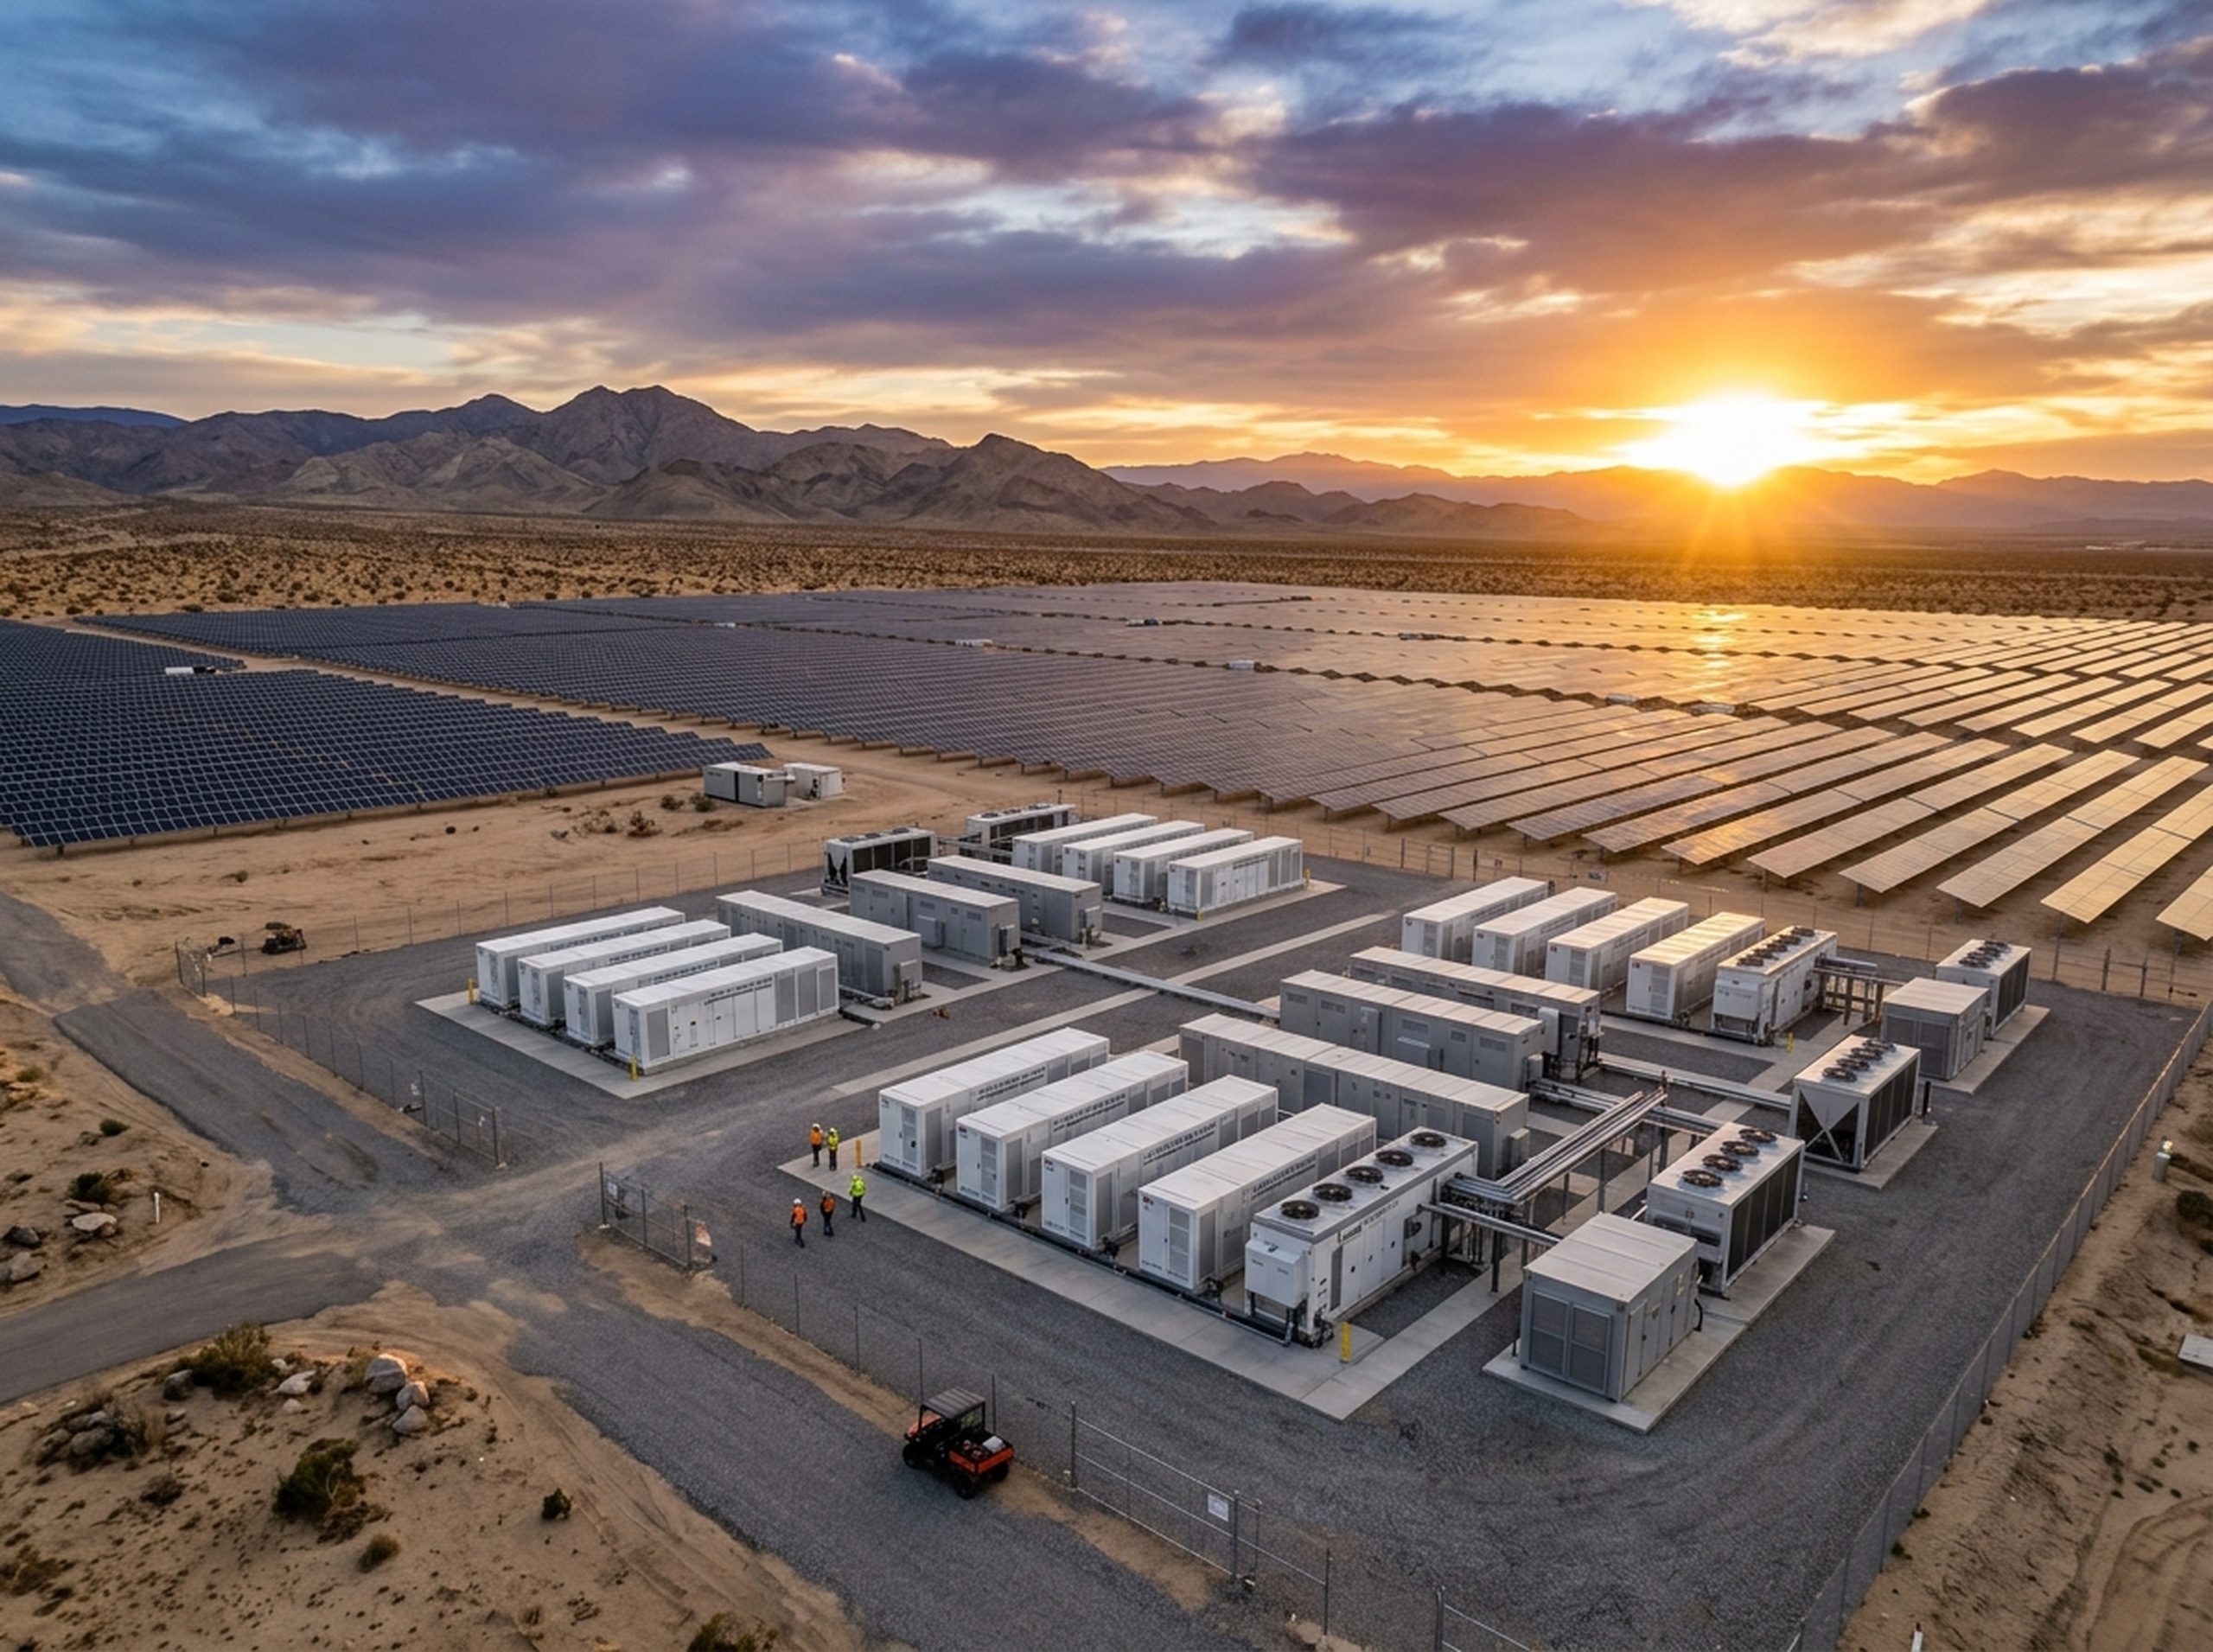
The UAE Advanced Energy Storage Systems market reached a valuation of USD 1.42 billion in 2025 and is projected to maintain a robust 12.4% CAGR from 2025 to 2035, driven by the aggressive national mandate to integrate intermittent renewables into the national grid. Industrial hubs like Abu Dhabi, home to the Masdar City clean energy cluster, serve as the primary engine for pilot testing, while Dubai serves as the critical deployment center for large-scale utility battery integration aligned with the Dubai Clean Energy Strategy 2050. On the demand side, industrial conglomerates and commercial real estate developers are increasingly adopting behind-the-meter storage solutions to mitigate peak load tariffs and ensure power reliability. Supply-side dynamics have shifted toward the localization of battery manufacturing, with firms like Dubai-based Emirates Global Aluminium exploring strategic collaborations to secure local mineral processing capabilities. Regulatory frameworks overseen by the UAE Ministry of Energy and Infrastructure are heavily prioritizing long-duration energy storage technologies to replace natural gas peaker plants. Furthermore, strict adherence to the UAE Net Zero by 2050 strategic initiative is compelling grid operators to standardize lithium-ion and flow battery safety protocols, effectively institutionalizing the shift toward a decentralized and highly resilient electrical grid architecture across all seven emirates.
By Storage Technology Type
- Lithium Iron Phosphate (LFP) cells
- NMC chemistry battery arrays
- Utility-scale containerized storage units
- Vanadium redox flow stacks
- Long-duration electrolyte modules
- Hybrid aqueous flow solutions
- Molten salt storage tanks
- Concrete-based thermal blocks
- Phase change material exchangers
- Underground cavern pressure tanks
- Adiabatic CAES plant turbines
- Deep-rock pneumatic storage units
By End-User Application
- National grid peak shaving
- Renewable energy integration banks
- Frequency regulation control centers
- Data center backup power
- Manufacturing facility microgrids
- Commercial office load shifting
- Solar rooftop battery integration
- Smart home peak management
- Off-grid villa energy solutions
- EV fast-charging station buffers
- Public transport transit hubs
- Heavy-duty port charging systems
Competitive Landscape
The UAE advanced energy storage systems (AESS) market is defined by a high-barrier, oligopolistic structure, heavily influenced by state-led decarbonization mandates under the UAE Energy Strategy 2050. Competitive intensity has surged following the integration of utility-scale battery energy storage systems (BESS) at the Mohammed bin Rashid Al Maktoum Solar Park, forcing suppliers to pivot from pure hardware sales to integrated energy-as-a-service (EaaS) models. Regional incumbents are increasingly forming strategic joint ventures with global technology leaders to localize manufacturing and fulfill In-Country Value (ICV) requirements mandated by the Abu Dhabi National Oil Company (ADNOC). Distribution strategies currently favor direct-to-government procurement channels and long-term engineering, procurement, and construction (EPC) partnerships. Firms like Masdar (founded 2006) leverage deep government ties to secure long-term power purchase agreements, while diversified industrial players such as Al Futtaim Group (founded 1930) utilize established logistics networks to capture the commercial and industrial (C&I) segment. Competitive maneuvers focus on enhancing round-trip efficiency (RTE) metrics and cycle-life stability, specifically targeting the harsh arid climate conditions prevalent in Dubai and the Western Region of Abu Dhabi.
| Company | Est. Year | Headquarters | Details | Details | Details | Details | Details | Details |
|---|---|---|---|---|---|---|---|---|
| Masdar | 2006 | Abu Dhabi, UAE | ~ | ~ | ~ | ~ | ~ | ~ |
| TAQA | 2005 | Abu Dhabi, UAE | ~ | ~ | ~ | ~ | ~ | ~ |
| Dubai Electricity and Water Authority (DEWA) | 1992 | Dubai, UAE | ~ | ~ | ~ | ~ | ~ | ~ |
| Al Futtaim Energy | 1930 | Dubai, UAE | ~ | ~ | ~ | ~ | ~ | ~ |
| Schneider Electric UAE | 1978 | Dubai, UAE | ~ | ~ | ~ | ~ | ~ | ~ |
🔒 Detailed cross-comparison data are available in the full report. Talk to Us to access complete competitive intelligence.
Growth Drivers
Decarbonization Mandates under UAE Energy Strategy 2050
The government is aggressively incentivizing grid-scale energy storage integration to accommodate a rising share of renewables in the national power mix. By 2030, the nation intends to derive 32 percent of its electricity from clean energy sources, necessitating significant deployment of lithium-ion and flow battery technologies. Industrial zones in Abu Dhabi are prioritizing these systems to stabilize peak demand loads while minimizing carbon footprints. These policies effectively create a localized demand floor that guarantees operational scale for utility-scale developers seeking to meet the 14 gigawatts of installed renewable capacity target.
Expansion of Photovoltaic Infrastructure in Dubai
The rapid expansion of the Mohammed bin Rashid Al Maktoum Solar Park requires high-capacity storage solutions to mitigate the inherent intermittency of solar energy. Installations at the facility successfully demonstrated the technical viability of long-duration storage, with peak energy discharge capabilities now exceeding 400 megawatt-hours per daily cycle. As the site moves toward its final phases, the requirement for localized energy buffers has become a central procurement priority. This project-driven demand serves as a primary catalyst for domestic technology implementation, reducing reliance on legacy natural gas peaking plants.
Technological Advancements in Thermal Storage
Research institutes in Sharjah are pioneering molten salt and phase-change material storage systems specifically designed for extreme arid climates. These proprietary innovations have achieved a round-trip efficiency of 88 percent in desert field trials conducted throughout 2023. By leveraging domestic manufacturing partnerships, organizations are localizing the production of high-durability cooling components that prevent thermal degradation of cells. This specialized infrastructure reduces the cooling expenditure burden for storage farms by 12 percent annually, fostering a more sustainable and cost-effective ecosystem for long-duration energy retention in industrial hubs.
Private Sector Investment in Smart Grid Integration
Private conglomerates, such as Masdar founded in 2006 and headquartered in Abu Dhabi, are driving localized deployment of AI-enabled battery management systems. These platforms optimize energy dispatch patterns to ensure high availability during evening peak hours when solar generation drops to zero. Current operational monitoring systems have reduced transmission loss rates by 4 percent across major metropolitan grids throughout 2024. The integration of these smart technologies allows grid operators to defer expensive infrastructure upgrades while maximizing the efficiency of existing substations and existing battery assets across the emirates.
Market Challenges
Stringent Import Dependency
The supply chain for advanced lithium-ion chemistries remains heavily reliant on international trade routes, leaving the local market exposed to global price volatility. Domestic manufacturing components account for less than 15 percent of total system costs as of 2024. This heavy reliance on external supply chains creates unpredictable lead times for utility-scale energy projects.
High Ambient Temperature Constraints
Extreme summer temperatures often exceeding 45 degrees Celsius necessitate sophisticated and costly thermal regulation systems to maintain optimal battery performance. These cooling requirements consume 20 percent of the total stored energy throughput in desert-based facilities as observed in 2023. Failure to effectively manage internal battery temperatures significantly accelerates cell degradation and lowers the overall system lifecycle.
Regulatory Standardization Gaps
The absence of a unified federal regulatory framework for second-life battery certification and disposal complicates the adoption of circular economy models. Current fragmented policies across different emirates result in a 30 percent increase in administrative overhead for multi-site storage developers operating in 2024. Standardizing these technical requirements remains a critical hurdle for large-scale investment firms.
Opportunities
Grid-Scale BESS Integration
The integration of Lithium-ion Battery Energy Storage Systems into the Dubai Electricity and Water Authority grid is accelerating to manage solar intermittency. High-capacity installations are essential for meeting the 2030 demand surge projected for the Mohammed bin Rashid Al Maktoum Solar Park. Authorities in Abu Dhabi have approved 450 megawatts of utility-scale storage capacity to ensure baseline stability across the emirate during peak evening usage hours.
Green Hydrogen Buffer Solutions
Investment in solid-state hydrogen storage is surging as companies like Masdar, founded in 2006 and headquartered in Abu Dhabi, expand their green hydrogen export capabilities. These systems provide the necessary seasonal energy buffering to stabilize production cycles for international shipping. Current initiatives involve deploying 100 megawatts of dedicated storage capacity at the Port of Khalifa to support industrial decarbonization efforts across the UAE.
Industrial Microgrid Expansion
Major manufacturing hubs in Jebel Ali Free Zone are transitioning toward onsite energy storage to mitigate grid fluctuations and reduce operational costs. Adoption of advanced flow batteries allows these firms to store excess thermal energy generated during industrial processes. With 75 percent of industrial facility managers prioritizing energy autonomy, the market for localized microgrid storage systems is expected to see a significant uptick in private capital expenditure.
Future Outlook
The UAE Advanced Energy Storage Systems market is poised for a transformative trajectory through 2035, driven by the ambitious objectives outlined in the UAE Net Zero 2050 strategic initiative. As the nation shifts away from heavy reliance on natural gas for power generation, the deployment of long-duration energy storage technologies will become the primary mechanism for maintaining electrical grid reliability. Regulatory frameworks established by the Ministry of Energy and Infrastructure are expected to evolve, mandating higher storage-to-capacity ratios for new renewable energy projects in the Western Region and beyond. Furthermore, the convergence of electric vehicle fleet electrification and stationary storage infrastructure will create a synergistic ecosystem, particularly in urban centers like Sharjah and Ras Al Khaimah. We anticipate that technological advancements in cobalt-free battery chemistries and thermal energy storage will reduce the levelized cost of storage by 35 percent by 2032. International partnerships with research hubs in Europe and East Asia will facilitate the rapid localization of manufacturing capabilities, positioning the UAE as a critical regional hub for storage technology exports. By 2035, the market will transition from a pilot-heavy phase to a fully integrated grid management model, where artificial intelligence-driven load balancing acts as the standard operational architecture for national energy distribution networks.
Major Players
- Masdar
- Al Futtaim Energy
- TAQA
- Dubai Electricity and Water Authority (DEWA)
- Schneider Electric UAE
- Siemens Energy Middle East
- ABB UAE
- Fluence Energy Middle East
- TotalEnergies Renewables UAE
- Engie Middle East
- Tesla Energy UAE
- Eaton Middle East
- Huawei Digital Power UAE
- Emirates Global Aluminium Energy
- W Solar Investment
Key Target Audience
- Battery Manufacturers (Lithium-ion and Flow Battery Specialists)
- Renewable Energy Project Developers (Utility-scale Solar Focus)
- Government and Regulatory Bodies (UAE Ministry of Energy and Infrastructure)
- Electric Utility Providers (Dubai Electricity and Water Authority)
- Grid Infrastructure Contractors and EPC Firms
- Energy Storage System Integrators (Residential and Commercial)
- Investors and Venture Capital Firms (Mubadala Investment Company)
- Industrial Conglomerates (Energy Division Heads)
- Transportation Authorities (Roads and Transport Authority Dubai)
- Public Infrastructure Planning Departments
- Smart City Technology Providers
- Oil and Gas Transition Strategy Offices
Research Methodology
Identification of Key Variables
- We establish core market parameters by analyzing the UAE Energy Strategy 2050 framework and current battery capacity trends.
- This stage identifies critical technical drivers, including round-trip efficiency requirements, cycle life specifications, and regulatory incentives established by the Abu Dhabi Department of Energy to ensure comprehensive data modeling.
Market Analysis and Construction
- Our team aggregates data from major regional players like Masdar and Emirates Global Aluminium to quantify current installation capacities.
- We construct a multi-layered forecast model that integrates historical grid load profiles with forecasted utility-scale battery deployment rates to project market growth through 2035.
Validation and Synthesis
- We perform in-depth qualitative validation by engaging with senior electrical grid engineers, government energy policy analysts, and renewable project lead developers.
- These professionals review our projections against operational realities, infrastructure constraints, and regional grid stability requirements, ensuring that our growth assumptions align with practical field expertise rather than purely theoretical statistical extrapolation.
- The final stage consolidates all quantitative projections and expert feedback into a cohesive strategic report detailing the UAE Advanced Energy Storage landscape.
- We synthesize findings from the Mohammed bin Rashid Al Maktoum Solar Park case studies to generate final CAGR metrics and market valuation assessments for the 2024-2035 period.
Table of Contents
 Executive Summary
2 Sections
▼
- Executive Summary
- Research Methodology (Defining UAE Storage Grid Scope, Bottom-Up Project Pipeline Tracking, Top-Down Renewable Capacity Assessment, DEWA And TRANSCO Infrastructure Capacity Review, Government Policy Impact Analysis, Demand-Side Load Profiling, Expert Stakeholder Interview Protocol, BESS Component Cost Modeling, Technical Standard Compliance Checks, Data Triangulation Across Regions, CAGR Forecasting Framework Definition, Market Entry Constraint Assessment, Competitive Landscape Mapping, Limitations Of Regulatory Data)
 UAE Advanced Energy Storage Systems Market Overview
7 Sections
▼
- Definition and Scope
- Market Evolution and Industry Genesis
- UAE National Energy Strategy 2050 Framework
- DEWA Utility-Scale Battery Integration Roadmap
- Giga-Project Storage Infrastructure Requirements
- Industrial Microgrid Adoption In Abu Dhabi
- Energy Storage Regulatory Environment Analysis
 UAE Advanced Energy Storage Systems Market Size (2020-2025)
3 Sections
▼
- By Market Value (2020-2025)
- By Installed Capacity In MWh (2020-2025)
- By Energy Storage Levelized Cost (2020-2025)
 UAE Advanced Energy Storage Systems Market Segmentation
46 Segments
▼
- By Storage Technology (In Value %)
- Lithium-Ion Chemistries
- Lithium Iron Phosphate (LFP)
- Nickel Manganese Cobalt (NMC)
- Lithium Titanate (LTO)
- Solid-State Batteries
- Flow Battery Systems
- Vanadium Redox Flow (VRFB)
- Iron Flow Batteries
- Zinc-Bromine Flow
- Mechanical Storage
- Pumped Hydro Storage
- Compressed Air Energy Storage
- Flywheel Energy Storage
- Thermal Storage
- Molten Salt Storage
- Concrete Thermal Energy Storage
- Phase Change Materials
- By Energy Capacity Scale (In Value %)
- Small Scale
- Below 50 kWh
- Medium Scale
- 50 kWh To 500 kWh
- Large Scale
- 500 kWh To 10 MWh
- Utility Scale
- Above 10 MWh
- By Application Sector (In Value %)
- Utility-Scale Renewable Integration
- Commercial And Industrial Backup
- Residential Smart Home Storage
- Electric Vehicle Charging Infrastructure
- Remote Off-Grid Power Systems
- Grid Frequency Regulation
- By Emirate Region (In Value %)
- Abu Dhabi
- Dubai
- Sharjah
- Northern Emirates
- By Project Ownership (In Value %)
- Independent Power Producers
- Government Utility Owned
- Private Enterprise Owned
- By Grid Connection Type (In Value %)
- Front-Of-The-Meter
- Behind-The-Meter
 UAE Advanced Energy Storage Systems Market Analysis
8 Sections
▼
- Growth Drivers (Decarbonization Mandates under UAE Energy Strategy 2050, Expansion of Photovoltaic Infrastructure in Dubai, Technological Advancements in Thermal Storage, Private Sector Investment in Smart Grid Integration)
- Market Challenges (Stringent Import Dependency, High Ambient Temperature Constraints, Regulatory Standardization Gaps)
- Market Opportunities (Grid-Scale BESS Integration, Green Hydrogen Buffer Solutions, Industrial Microgrid Expansion)
- Market Trends (Hydrogen-Storage Integration, AI-Driven Grid Optimization, Circular Battery Economy, Modular BESS Deployment)
- Government Regulations
- SWOT Analysis
- Porter's Five Forces Analysis
- PESTLE Analysis
 UAE Advanced Energy Storage Systems Market Competitive Analysis
21 Sections
▼
- Market Share of Major Players
- Global BESS OEM Competition Analysis
- Domestic EPC Contractor Strategic Positioning
- Utility Versus Private Commercial Competition
- Technology-Specific Market Dominance Trends
- Energy Storage Software Ecosystem Landscape
- Utility-Scale Infrastructure Procurement Patterns
- Cross Comparison Parameters (Portfolio Depth In Utility-Scale Projects, Vertical Integration Of Battery Manufacturing, R&D Commitment To Thermal Storage Tech, Regional EPC Partnership Network Strength, Software Capability For BESS Management, Tier-1 Supplier Relationship Breadth, Standardized Safety Certification Compliance, Lifecycle O&M Service Infrastructure)
- Competitive Product Benchmarking (Cycle Life At 80% DOD, Round-Trip Efficiency Percentage, Thermal Runaway Mitigation Systems, Power Density Per Cubic Meter, Discharge Duration Capabilities, Ambient Operating Temperature Rating)
- Financial and Operational Parameters
- SWOT Analysis of Major Players
- Detailed Profiles of Major Companies
- Tesla (2003, USA) – Megapack, Powerwall
- Fluence (2018, USA) – Sunstack, Gridstack
- Sungrow Power Supply (1997, China) – PowerTitan, PowerStack
- Siemens Energy (2020, Germany) – Fluence JV Portfolio, BlueVault
- Schneider Electric (1836, France) – EcoStruxure, Conext
- ABB (1988, Switzerland) – ESSPRO, PowerStore
- Wartsila (1834, Finland) – Greensmith GEMS
- Contemporary Amperex Technology (2011, China) – EnerOne, EnerC
- Masdar (2006, UAE) – Masdar Clean Energy Storage
 UAE Advanced Energy Storage Systems Market End-User Analysis
7 Sections
▼
- Peak Shaving Adoption Rate In Industries
- Average Storage System Discharge Duration
- Grid Stability Service Contract Revenue
- Annual Megawatt-Hour Consumption Growth
- Residential PV-Storage Attachment Rate
- Industrial Backup Power Reliability Metrics
- Average Investment Payback Period Targets
 UAE Advanced Energy Storage Systems Market Future Size (2026-2035)
3 Sections
▼
- By Market Value (2026-2035)
- By Installed Capacity In MWh (2026-2035)
- By Energy Storage Levelized Cost (2026-2035)
Frequently Asked Questions
The current market size is USD 1.42 billion in 2025, projected to reach USD 4.57 billion by 2035 (12.4% CAGR from 2025 to 2035). This growth is supported by large-scale government infrastructure projects and a national shift toward grid-stabilizing technologies. The figures reflect the total valuation across both lithium-ion and flow battery deployment sectors within the Emirates.
The primary operational hurdle involves extreme ambient temperatures in desert regions like Al Dhafra, which accelerate battery degradation rates. Supply chain logistics for specialized electrolyte components remain reliant on international imports, creating vulnerability to global price volatility. Furthermore, the absence of standardized national safety protocols for large-scale energy storage fire suppression continues to slow the permitting process for new installations.
Masdar, founded in 2006 and headquartered in Abu Dhabi, remains the dominant developer of utility-scale storage integration. Dubai-based DEWA (Dubai Electricity and Water Authority) leads as the primary public utility stakeholder driving infrastructure procurement. International entities like Fluence Energy, established in 2018 and based in Arlington, Virginia, maintain a strong market presence through strategic partnerships with regional engineering firms.
The UAE Energy Strategy 2050 serves as the primary catalyst, mandating a drastic increase in renewable energy contributions to the national grid. Rapid industrial expansion in free zones like Jebel Ali requires constant power reliability, necessitating high-capacity energy storage for peak-shaving. Additionally, private sector investment is surging as organizations seek to decarbonize operations in alignment with the UAE Net Zero by 2050 initiative.
A significant trend is the transition toward long-duration energy storage systems, including vanadium flow batteries, to better manage 24-hour solar farm output cycles. Digitalization through AI-driven battery management systems is becoming standard to optimize charge and discharge performance in high-heat environments. Investors are also shifting focus toward domestic battery assembly plants located in industrial hubs like Khalifa Economic Zones Abu Dhabi (KEZAD) to reduce import dependencies.


 Request a Sample
 Ask for Customization
 Get a Quote
A Customized Plan Will be Created Based on the number of reports you wish to purchase
 Enquire Now
