
 Download PDF
Market Overview
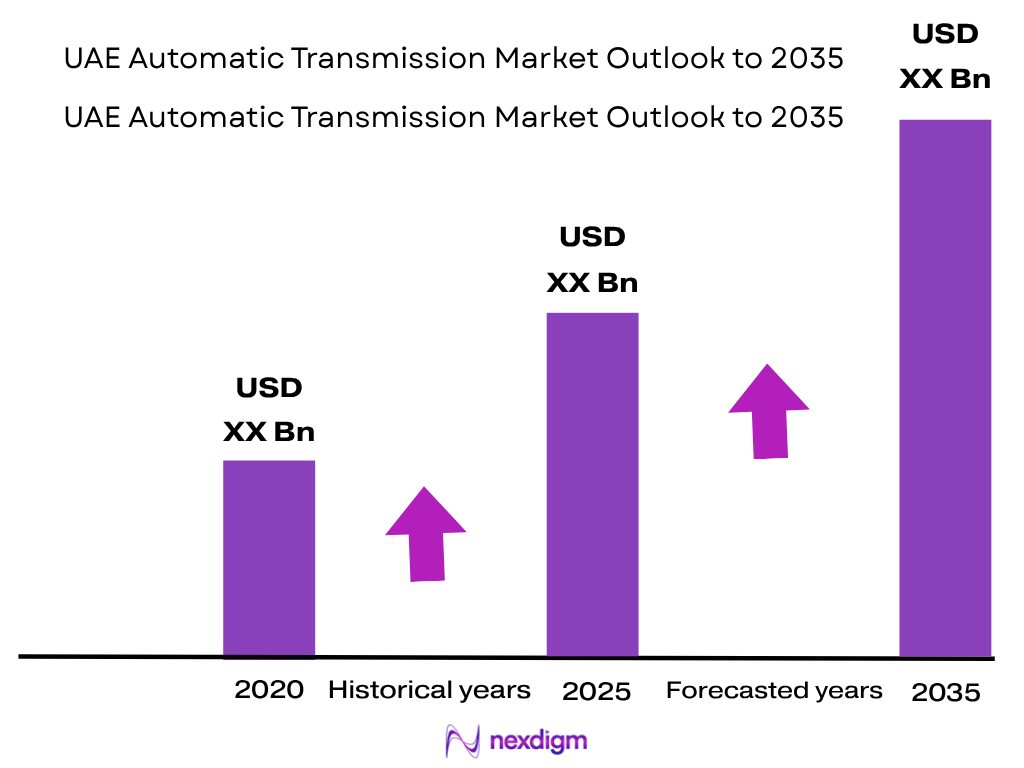
The UAE Automatic Transmission Market is valued at approximately ~USD XX billion, based on historical vehicle-fleet, replacement and transmission-fitment analysis. New-vehicle sales increased from 277,525 units in the preceding annual cycle to 330,532 units in the latest cycle. Dubai’s rental fleet simultaneously expanded from 49,725 vehicles to 71,040 vehicles, supporting recurring demand for automatic gearboxes, replacement assemblies, valve bodies, torque converters, CVT components and transmission servicing.
Dubai, Abu Dhabi and Sharjah dominate the UAE Automatic Transmission Market because they concentrate vehicle ownership, dealerships, fleets, workshops, spare-parts distribution and re-export activity. Dubai alone has approximately 2.5 million registered vehicles, representing around half of the UAE vehicle fleet, while its luxury-transport fleet expanded from 12,602 vehicles to 16,396 vehicles between consecutive annual periods. The emirate’s extensive logistics, rental, luxury and automotive-service ecosystem reinforces automatic-transmission replacement and maintenance demand.
Market Segmentation
By Transmission Technology
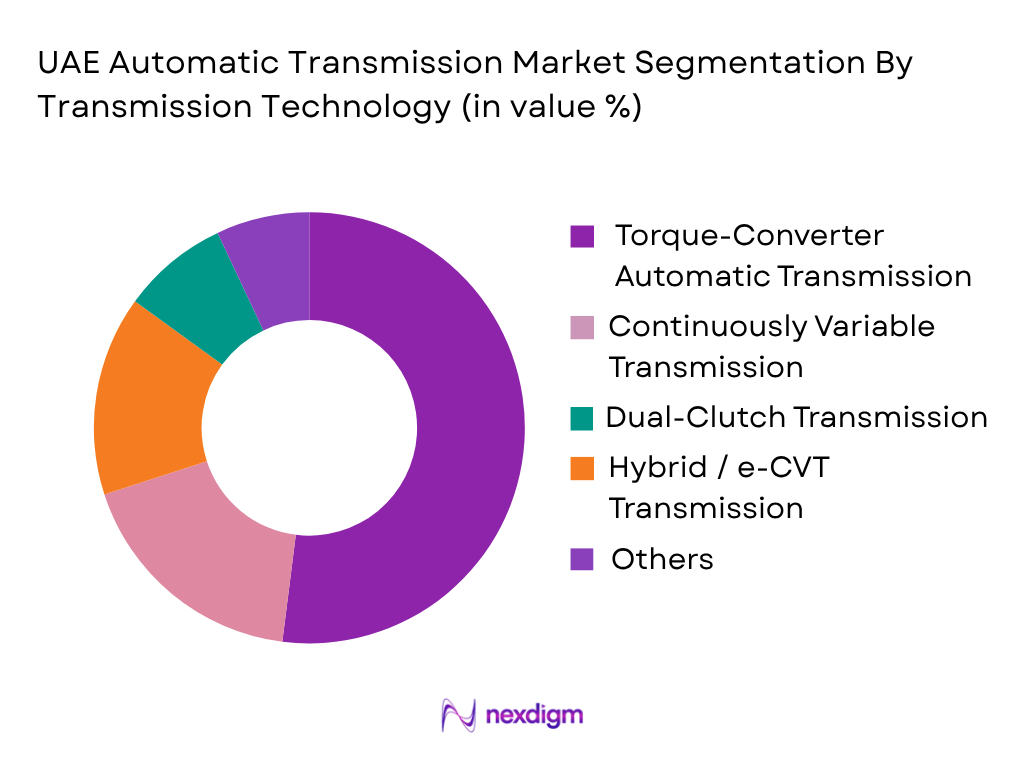
The UAE Automatic Transmission Market is segmented into conventional torque-converter automatic transmissions, continuously variable transmissions, dual-clutch transmissions, automated manual transmissions, hybrid/e-CVT transmissions and other advanced architectures. Conventional torque-converter automatic transmissions hold the dominant position because the UAE vehicle fleet contains a large concentration of SUVs, 4x4s, luxury vehicles, pickups and high-powered passenger vehicles requiring smooth torque delivery and robust thermal performance. Six-speed, eight-speed, nine-speed and ten-speed torque-converter systems are particularly well suited to high-torque gasoline engines and demanding desert-driving applications. Japanese and American SUVs strengthen this category, while European luxury models support sophisticated multi-speed automatic systems. CVTs remain important across Japanese sedans and crossovers because of their smooth operation, whereas DCTs are concentrated in European, Korean and performance-oriented vehicles. Hybrid e-CVT and dedicated hybrid architectures are emerging as electrified Toyota, Lexus and other hybrid models broaden their UAE presence. AISIN’s portfolio itself spans 6-speed, 8-speed and 10-speed AT systems alongside CVTs and hybrid transmissions, illustrating the technology breadth relevant to the local fleet.
By Vehicle Type
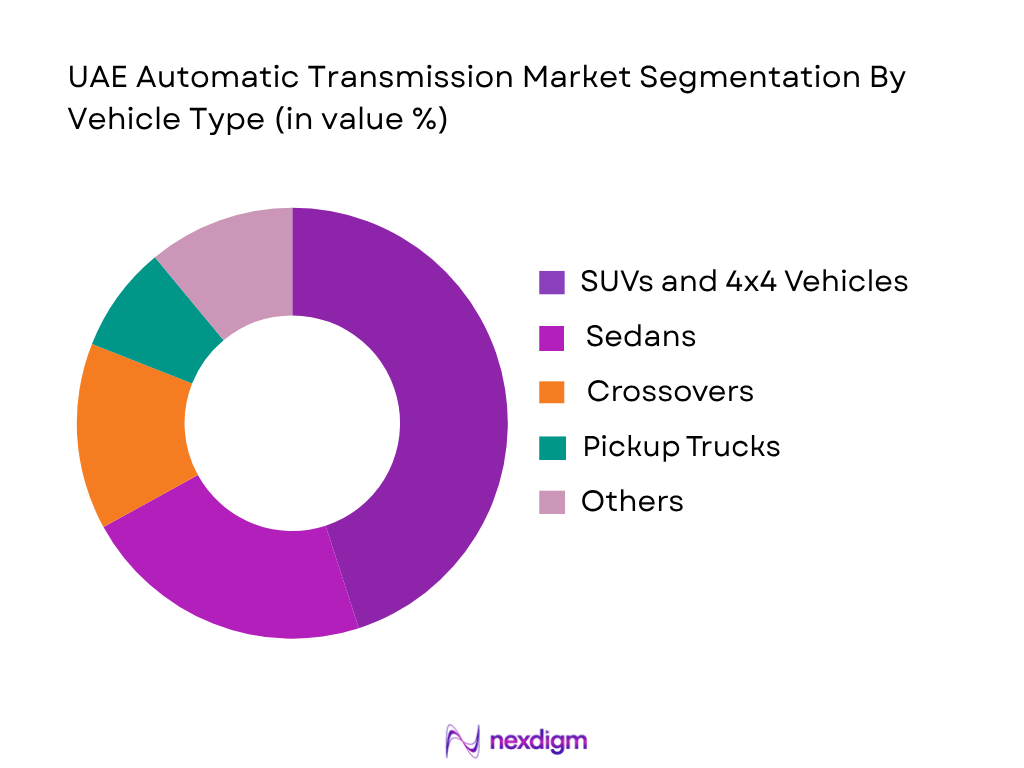
The UAE Automatic Transmission Market is segmented into SUVs and 4×4 vehicles, sedans, crossovers, pickups, light commercial vehicles and other vehicle categories. SUVs and 4x4s hold the dominant position because UAE driving patterns combine urban mobility with highway travel, towing, desert recreation and off-road usage. These vehicles commonly require high-torque torque-converter transmissions with strong cooling systems, broad ratio spreads and AWD or 4WD compatibility. Toyota Land Cruiser-type platforms illustrate the relevance of advanced 10-speed automatic architectures designed around reliability, durability and demanding off-road operation. Premium SUVs additionally strengthen demand for electronically controlled 8-speed and 9-speed units, while pickups create requirements for towing-oriented transmission calibration and thermal management. Dubai’s registered vehicle base of approximately 2.5 million vehicles further provides a large installed fleet supporting long-term replacement and servicing requirements. Crossovers broaden CVT and DCT demand, whereas commercial fleets provide additional opportunities for heavy-duty automatic systems.
Competitive Landscape
The UAE Automatic Transmission Market is characterized by global transmission manufacturers supplying through vehicle OEMs, regional distributors, authorized service networks and independent aftermarket channels. AISIN has a direct regional operation in Dubai through AISIN Asia Middle East & Africa FZCO, handling automotive parts and OE import, export and sales. ZF, Allison, JATCO and Hyundai Transys strengthen competition across passenger vehicles, SUVs, commercial vehicles, CVTs, conventional automatics and electrified drivetrains. Competitive differentiation increasingly depends on UAE/GCC distribution, harsh-climate durability, vehicle fitment breadth, diagnostic capability and replacement-parts support.
| Major Player | Establishment Year | Headquarters | Core Transmission Architecture | UAE / GCC Position | SUV & High-Torque Capability | CVT / DCT Capability | Hybrid / Electrified Readiness | Aftermarket & Technical Support |
| AISIN Corporation | 1965 | Kariya, Japan | ~ | ~ | ~ | ~ | ~ | ~ |
| ZF Friedrichshafen AG | 1915 | Friedrichshafen, Germany | ~ | ~ | ~ | ~ | ~ | ~ |
| Allison Transmission Holdings | 1915 | Indianapolis, USA | ~ | ~ | ~ | ~ | ~ | ~ |
| JATCO Ltd. | 1999 | Fuji, Japan | ~ | ~ | ~ | ~ | ~ | ~ |
| Hyundai Transys | 1999 | Seosan, South Korea | ~ | ~ | ~ | ~ |
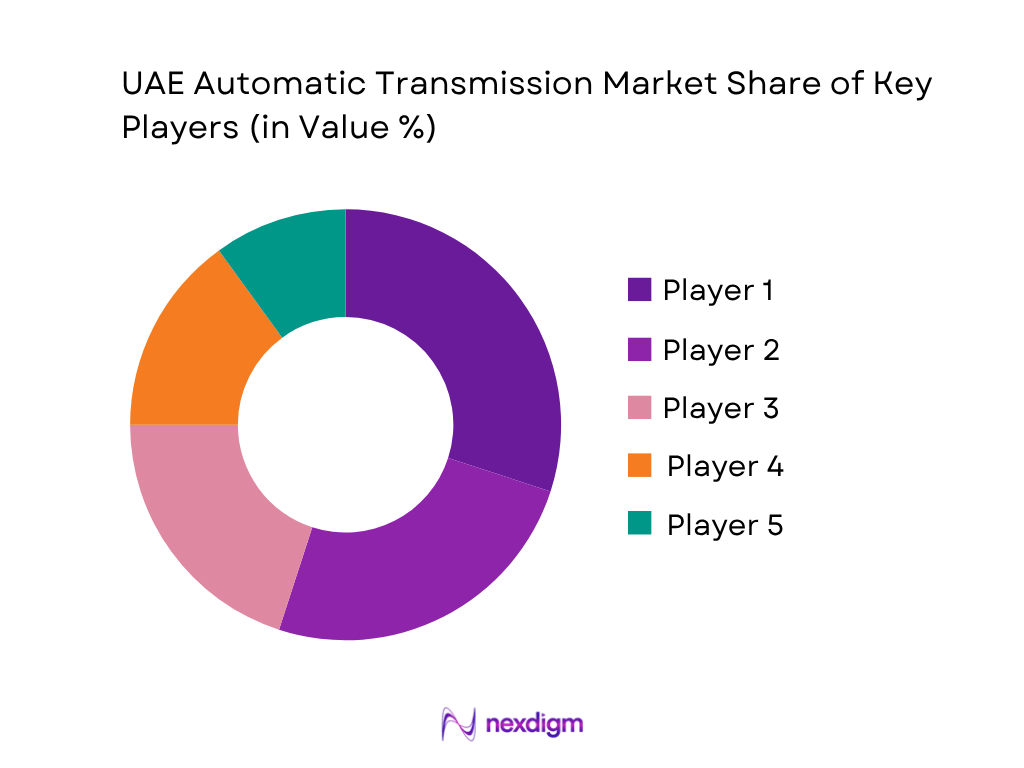
UAE Automatic Transmission Market Analysis
Growth Drivers
Expanding Vehicle Parc and High-Utilization Fleet Demand
The UAE Automatic Transmission Market is supported by a large and intensively utilized vehicle base, particularly in Dubai, where automatic transmissions dominate passenger cars, SUVs, luxury vehicles, rental fleets and commercial transport applications. Dubai Roads and Transport Authority reported 2.5 million registered vehicles in Dubai in 2024, accounting for roughly half of vehicles registered across the UAE. The rental-car fleet expanded from 49,725 vehicles to 71,040 vehicles, while active rental companies increased from 2,627 to 3,494 during the same reporting period. High vehicle utilization is particularly relevant to automatic transmissions because repeated urban stop-start operation increases operating cycles for torque converters, clutch packs, valve bodies, CVT assemblies, solenoids and transmission-control systems. Dubai’s luxury-transport fleet also expanded from 12,602 vehicles to 16,396 vehicles, while luxury-transport trips reached 43,443,678 and passengers carried reached 75,592,000. These operating volumes support demand for multi-speed AT, DCT and electronically controlled drivetrain servicing. At the macro level, the International Monetary Fund recorded UAE nominal GDP at AED 2,028 billion, equivalent to USD 552.3 billion, in 2024, providing a strong economic base for vehicle ownership, fleet activity and advanced drivetrain adoption.
Commercial Transport and Logistics Fleet Expansion
Expansion of commercial transportation and logistics activity is another direct growth driver for the UAE Automatic Transmission Market, particularly for light-commercial, delivery, municipal and heavy-duty transmission applications. Dubai Roads and Transport Authority reported that the number of licensed commercial-transport companies increased from 12,100 in 2024 to 16,917 in 2025. The number of vehicles registered within Dubai’s commercial-transport sector subsequently exceeded 500,000 vehicles in 2025, creating an extensive operating base for automatic and automated transmissions used in delivery vans, buses, trucks, logistics fleets and specialized commercial vehicles. Commercial vehicles generally accumulate greater operating hours and shift cycles than privately owned cars, increasing requirements for torque-converter assemblies, planetary gearsets, clutch packs, valve bodies, transmission coolers, solenoids and diagnostic services. Fleet operators also place greater emphasis on transmission reliability and predictable maintenance because drivetrain downtime directly affects fleet availability. The expanding logistics ecosystem therefore strengthens both original-fit and replacement transmission demand. The International Monetary Fund recorded UAE nominal GDP of AED 2,028 billion, or USD 552.3 billion, in 2024, while the country’s substantial non-hydrocarbon economic activity supports transportation, logistics, tourism and distribution sectors that depend heavily on high-utilization vehicle fleets.
Market Challenges
Growing Electric Vehicle Base Reducing Conventional Multi-Speed Transmission Content
The accelerating adoption of battery-electric vehicles presents a structural challenge to conventional automatic transmissions because most battery-electric passenger vehicles use single-speed reduction gearing rather than torque-converter AT, CVT or multi-clutch automatic architectures. Dubai Electricity and Water Authority reported 37,486 electric vehicles in Dubai at the end of 2024, with the number increasing to 47,944 vehicles at the end of 2025. Supporting infrastructure has expanded simultaneously: Dubai had more than 740 EV charging points in December 2024, more than 1,270 charging points in August 2025, and more than 1,860 charging points by January 2026. At UAE level, the Ministry of Energy and Infrastructure reported approximately 1,000 electric-vehicle charging points at the end of 2024, demonstrating that electrified mobility is developing beyond isolated vehicle introductions. This transition changes transmission content per vehicle because EVs replace torque converters, CVT pulley systems, DCT clutch modules and complex planetary gearboxes with reduction gears and integrated electric-drive systems. Conventional transmission suppliers therefore face pressure to diversify into hybrid transaxles, e-axles, reducers, bearings and electronic drivetrain controls. The International Monetary Fund recorded UAE nominal GDP at AED 2,028 billion, equivalent to USD 552.3 billion, in 2024, showing that this drivetrain transition is occurring within a substantial automotive-consuming economy.
High Vehicle Utilization Increasing Transmission Durability and Service Complexity
The UAE Automatic Transmission Market faces significant durability and servicing challenges because a substantial portion of the vehicle fleet operates under intensive rental, luxury-transport, e-hail, logistics and commercial-duty cycles. Dubai Roads and Transport Authority recorded 71,040 vehicles in the rental fleet in 2024, compared with 49,725 vehicles in the preceding reporting period. Luxury-transport vehicles increased from 12,602 to 16,396, while e-hail trips reached 32,556,975 in 2024, compared with 24,616,527 previously. Luxury-transport trips reached 43,443,678, while the sector transported 75,592,000 passengers during the same year. These operating volumes translate into repeated acceleration, deceleration, gear selection and low-speed operation, placing sustained duty cycles on transmission fluid, torque converters, wet and dry clutch assemblies, hydraulic pumps, valve bodies and electronic control modules. Modern 8-speed, 9-speed and 10-speed automatics, CVTs and DCTs also require specialized diagnostic equipment and model-specific calibration, making repair more technically demanding than conventional gearbox servicing. Dubai’s broader base of 2.5 million registered vehicles amplifies this service challenge. The International Monetary Fund reported UAE nominal GDP of AED 2,028 billion, or USD 552.3 billion, in 2024, supporting a vehicle-intensive economy but also increasing the technical burden placed on the transmission aftermarket.
Market Opportunities
Specialized Transmission Repair, Rebuilding and Remanufacturing
A major future opportunity for the UAE Automatic Transmission Market lies in specialized repair, rebuilding and remanufacturing as the country’s large vehicle fleet accumulates mileage and increasingly incorporates electronically controlled AT, CVT and DCT technologies. Dubai Roads and Transport Authority recorded 2.5 million registered vehicles in Dubai in 2024, providing a substantial installed base for transmission-related maintenance and replacement. The rental fleet alone reached 71,040 vehicles, supported by 3,494 active rental companies, while the luxury-transport fleet expanded to 16,396 vehicles. These high-utilization fleets create recurring requirements for valve-body rebuilding, torque-converter refurbishment, CVT pulley and bearing replacement, DCT clutch servicing, mechatronic-module repair, solenoid replacement, transmission-control diagnostics and fluid-management services. The opportunity extends beyond complete gearbox replacement because sophisticated diagnostic and remanufacturing capability can recover high-value assemblies and address imported-vehicle specifications across Japanese, European, Korean and American platforms. Dubai’s concentration of dealerships, workshops, parts traders and fleet operators provides the ecosystem required for specialist transmission businesses to scale operations. The International Monetary Fund recorded UAE nominal GDP at AED 2,028 billion, equivalent to USD 552.3 billion, in 2024, supporting continued vehicle ownership and aftermarket expenditure across a technologically diverse vehicle fleet.
Hybrid Drivetrains and Electrified Transmission Systems
Hybridization creates a forward-looking opportunity for the UAE Automatic Transmission Market because hybrid vehicles retain substantial transmission and drivetrain content even as the country moves toward greater electrification. Dubai Electricity and Water Authority reported 49,300 electric and hybrid vehicles in Dubai during 2024, demonstrating an established electrified vehicle base alongside conventional gasoline vehicles. Pure electric vehicles reached 37,486 units at the end of 2024 and increased to 47,944 units at the end of 2025, while charging infrastructure expanded to more than 1,860 charging points by January 2026. This transition creates room for transmission suppliers and service providers to move beyond conventional AT repair into power-split transaxles, hybrid e-CVT systems, integrated electric motors, reduction gear assemblies, electrically driven oil pumps, bearings, thermal-management systems and drivetrain electronics. Hybrid SUVs are particularly relevant to the UAE because they combine electrification with vehicle formats traditionally associated with automatic transmissions, AWD systems and higher torque requirements. Workshops capable of diagnosing both mechanical transmission components and high-voltage electrified drivetrains can therefore address an expanding technical niche. The International Monetary Fund recorded UAE nominal GDP of AED 2,028 billion, equivalent to USD 552.3 billion, in 2024, providing a strong economic foundation for continued adoption of advanced hybrid and electrified vehicle technologies.
Future Outlook
The UAE Automatic Transmission Market is expected to expand at an indicative ~X.X% CAGR during 2026–2035, supported by continued vehicle-fleet expansion, SUV and 4×4 demand, premium-vehicle ownership, commercial transport activity and growth in hybrid powertrains. The market will gradually shift from conventional transmission replacement toward more sophisticated mechatronics, electronically controlled multi-speed units, hybrid transaxles and advanced diagnostic services. Torque-converter automatic transmissions are expected to remain strategically important because the UAE vehicle mix favors SUVs, large crossovers, pickups and luxury vehicles. Eight-speed and ten-speed systems provide the ratio spread, highway efficiency, low-speed smoothness and torque-handling characteristics required by these applications. High ambient temperatures and demanding off-road usage will simultaneously make cooling capacity, fluid performance and transmission calibration important product-selection variables.
CVT demand will remain closely linked to the large Japanese passenger-car and crossover parc. The opportunity will extend beyond complete replacement units into valve bodies, solenoids, push belts, pulleys, bearings, transmission control electronics and specialized rebuilding. As vehicles age, workshops able to accurately diagnose CVT pressure, temperature and ratio-control problems can capture a larger share of high-value transmission service work.
Major Players
- AISIN Corporation / AISIN Asia Middle East & Africa FZCO
- ZF Friedrichshafen AG
- Allison Transmission Holdings, Inc.
- JATCO Ltd.
- Hyundai Transys Inc.
- BorgWarner Inc.
- Magna International Inc. / Magna Powertrain
- Schaeffler AG
- Eaton Corporation plc
- Dana Incorporated
- Toyota Motor Corporation
- Nissan Motor Co., Ltd.
- Mercedes-Benz Group AG
- BMW Group
- Ford Motor Company
Key Target Audience
- Automatic Transmission Manufacturers and Drivetrain Suppliers
- Automotive OEMs and Authorized Vehicle Distributors
- Transmission Parts Importers, Distributors and Re-Exporters
- Transmission Repair, Rebuilding and Remanufacturing Companies
- Vehicle Rental, Leasing, Logistics and Commercial Fleet Operators
- Automotive Aftermarket and Workshop Networks
- Investments and Venture Capitalist Firms
- Government and Regulatory Bodies (Ministry of Energy and Infrastructure, Ministry of Industry and Advanced Technology, Roads and Transport Authority Dubai, Integrated Transport Centre Abu Dhabi, Dubai Customs, Federal Authority for Identity, Citizenship, Customs and Port Security)
Research Methodology
Step 1: Identification of Key Variables
The initial phase develops an ecosystem map covering transmission manufacturers, automotive OEMs, authorized vehicle distributors, transmission-parts importers, free-zone traders, specialist workshops, rebuilders, fleet operators and regulatory authorities in the UAE Automatic Transmission Market. Critical variables include transmission architecture, vehicle type, gear count, torque capacity, vehicle origin, fleet composition, import dependency, replacement frequency, workshop capability and re-export activity.
Step 2: Market Analysis and Construction
Historical UAE vehicle sales, registration, fleet, import and aftermarket indicators are analyzed using top-down and bottom-up frameworks. Transmission fitment is mapped across SUVs, sedans, crossovers, pickups, commercial vehicles and premium vehicles, followed by technology-level assessment of torque-converter AT, CVT, DCT, hybrid transmissions and other architectures. Replacement and remanufacturing demand is incorporated through vehicle-parc and service-channel analysis.
Step 3: Hypothesis Validation and Expert Consultation
Market hypotheses are validated through computer-assisted telephone interviews with transmission distributors, vehicle dealers, automotive-parts importers, workshop operators, fleet managers and transmission specialists. Discussions evaluate transmission failure patterns, replacement-versus-repair decisions, technology preferences, component availability, harsh-climate performance, diagnostic capability, parts sourcing, remanufacturing potential and regional re-export activity to refine the market model.
Step 4: Research Synthesis and Final Output
The final phase triangulates demand-side vehicle data with transmission supplier, distributor, service-network and aftermarket information. Technology-level estimates are reconciled with vehicle-fitment patterns, transmission imports, replacement activity and fleet characteristics. This process generates the final market segmentation, competitive landscape, import-dependency assessment, aftermarket analysis and long-term outlook for the UAE Automatic Transmission Market.

- Executive Summary
- Research Methodology (Market Definition and Scope, UAE Automatic Transmission Taxonomy, Torque-Converter Automatic Transmission Classification, Continuously Variable Transmission Mapping, Dual-Clutch Transmission Mapping, Automated Manual Transmission Assessment, Hybrid Transmission Classification, Vehicle Fitment Mapping, Torque Capacity Assessment, Gear-Speed Configuration Assessment, Import and Re-Export Assessment, Vehicle Parc Analysis, Replacement Demand Assessment, Market Sizing Framework)

- Definition and Scope
- UAE Automatic Transmission Industry Evolution and Technology Development
- Automatic Transmission Manufacturing and Assembly Process
- Automatic Transmission Value Chain Analysis
- UAE Automatic Transmission Supply Chain Analysis
- Transmission Component, Mechatronics and Control-System Ecosystem Analysis
- UAE Automatic Transmission Import Dependency and Re-Export Assessment
- OEM, Authorized Distributor and Independent Aftermarket Framework

- Growth Drivers (High Automatic Transmission Fitment Across Passenger Vehicles, SUV and 4×4 Vehicle Demand, Premium and Luxury Vehicle Fleet Expansion, High-Torque Pickup and Off-Road Applications, Commercial Vehicle Fleet Activity, Increasing 8-Speed and 10-Speed AT Fitment, Growing Hybrid Vehicle Adoption, Large Replacement and Repair Base)
- Market Challenges (Complete Transmission Import Dependency, High Ambient Temperature and Thermal Stress, Sand and Dust Operating Conditions, Complex Mechatronic Repair Requirements, High Variety of Imported Vehicle Specifications, Limited Local Transmission Manufacturing, Counterfeit and Non-Genuine Parts Exposure, Increasing Battery-Electric Vehicle Substitution)
- Market Opportunities (High-Torque SUV Transmission Systems, Hybrid Automatic Transmissions, Premium Vehicle Transmission Remanufacturing, CVT Rebuilding, DCT Mechatronics Repair, Heavy-Duty Fully Automatic Transmissions, Transmission Cooling and Thermal Management, Regional Transmission Re-Export)
- Market Trends (8-Speed and 10-Speed Automatic Adoption, CVT Penetration in Japanese Vehicles, DCT Adoption in European and Performance Vehicles, Hybrid e-CVT Expansion, Shift-by-Wire Systems, Adaptive Shift Control, Connected Transmission Diagnostics, Specialized Transmission Remanufacturing)
- Regulatory and Standards Landscape (UAE Vehicle Registration Requirements, Emirates Authority for Standardization Requirements, GCC Vehicle Conformity Requirements, Vehicle Inspection Requirements, Roadworthiness Regulations, Imported Used Vehicle Requirements, Automotive Spare Parts Conformity, Workshop Licensing Requirements)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Competition Ecosystem

- By Market Value (2020-2025)
- By Automatic Transmission Unit Demand (2020-2025)
- By OEM-Fitted Automatic Transmission Volume (2020-2025)
- By Imported Automatic Transmission Volume (2020-2025)
- By Re-Exported Automatic Transmission Volume (2020-2025)
- By Replacement Transmission Volume (2020-2025)
- By Remanufactured and Rebuilt Transmission Volume (2020-2025)
- By Passenger Vehicle Automatic Transmission Demand (2020-2025)
- By SUV and 4×4 Automatic Transmission Demand (2020-2025)

- By Transmission Technology (In Value %)
Conventional Torque-Converter Automatic Transmission
Continuously Variable Transmission
Dual-Clutch Transmission
Automated Manual Transmission
Hybrid Automatic Transmission
Power-Split / e-CVT Hybrid Transmission
Dedicated Hybrid Transmission
High-Torque Heavy-Duty Fully Automatic Transmission
Single-Speed Electrified Reduction Transmission
Other Advanced Automatic Transmission Architectures - By Number of Forward Speeds (In Value %)
4-Speed and Below Automatic Transmission
5-Speed Automatic Transmission
6-Speed Automatic Transmission
7-Speed Dual-Clutch Transmission
8-Speed Automatic Transmission
9-Speed Automatic Transmission
10-Speed Automatic Transmission
Above 10-Speed and Multi-Ratio Systems
Continuously Variable Ratio Systems
Hybrid Power-Split Systems - By Vehicle Type (In Value %)
Sedans
Hatchbacks and Compact Cars
Crossovers
Compact SUVs
Mid-Size SUVs
Full-Size SUVs
Luxury SUVs
Pickup Trucks
Sports and Performance Vehicles
Light Commercial Vehicles
Medium-Duty Trucks
Heavy-Duty Trucks
Buses and Coaches
Construction and Vocational Vehicles
Specialty and Government Fleet Vehicles - By Sales Channel (In Value %)
OEM Vehicle Fitment
Authorized Vehicle Distributor Channel
Authorized Transmission Distributor Channel
Independent Spare Parts Distributor
Transmission Specialist Workshops
Dealer Service Centres
Independent Automotive Workshops
Transmission Rebuilders and Remanufacturers
Fleet Maintenance Operators
Online Automotive Parts Platforms
Used and Reconditioned Transmission Importers
Re-Export and Free-Zone Trading Channels - By Emirate (In Value %)
Dubai
Abu Dhabi
Sharjah
Ajman
Ras Al Khaimah
Fujairah
Umm Al Quwain

- Market Share of Major Players (By Revenue, Transmission Unit Volume, Transmission Technology, Vehicle Segment, OEM Fitment, Torque Class, Sales Channel, Aftermarket Presence)
- Cross Comparison Parameters (Automatic Transmission Architecture and Gear-Speed Portfolio, UAE and GCC Distribution and Service Footprint, SUV-4×4 and High-Torque Vehicle Fitment Capability, Premium and Luxury Vehicle Transmission Coverage, CVT-DCT-Torque Converter Technology Breadth, Hybrid and Electrified Transmission Readiness, Desert-Duty Thermal Performance and Heavy-Load Capability, Aftermarket Diagnostics-Remanufacturing and Parts Support)
- SWOT Analysis of Major Players
- Competitive Positioning Matrix
- Transmission Architecture and Product Portfolio Benchmarking
- Distribution and Aftermarket Support Benchmarking
- Market Entry Strategy Assessment
- Detailed Profiles of Major Companies
AISIN Corporation / AISIN Asia Middle East & Africa FZCO
ZF Friedrichshafen AG
Allison Transmission Holdings, Inc.
JATCO Ltd.
Hyundai Transys Inc.
BorgWarner Inc.
Magna International Inc. / Magna Powertrain
Schaeffler AG
Eaton Corporation plc
Dana Incorporated
Toyota Motor Corporation
Nissan Motor Co., Ltd.
Mercedes-Benz Group AG
BMW Group
Ford Motor Company

- Buyer Segmentation
- OEM and Distributor Procurement Behaviour
- Supplier Selection Criteria
- Buyer Pain Points
- Technology Adoption Assessment
- Replacement and Repurchase Behaviour

- By Market Value (2026-2035)
- By Automatic Transmission Unit Demand (2026-2035)
- By OEM-Fitted Automatic Transmission Volume (2026-2035)
- By Imported Automatic Transmission Volume (2026-2035)
- By Re-Exported Automatic Transmission Volume (2026-2035)
- By Replacement Transmission Volume (2026-2035)
- By Remanufactured and Rebuilt Transmission Volume (2026-2035)
- By Passenger Vehicle Automatic Transmission Demand (2026-2035)
- By SUV and 4×4 Automatic Transmission Demand (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
