
 Download PDF
Market Overview
The UAE Calcium Chloride Market is valued at ~USD XX million in 2024, compared with ~USD XX million in 2023, with demand supported by the country’s large oil and gas ecosystem, industrial water-treatment requirements, construction activity, food processing, refrigeration and chemical manufacturing. The UAE economy recorded GDP of USD 552.32 billion and real GDP growth of 4.0 in 2024, while industry including construction represented 44.3 of GDP, creating a broad industrial base for calcium chloride applications.
Abu Dhabi and Dubai represent the principal demand centers for the UAE Calcium Chloride Market because they combine oilfield operations, petrochemical manufacturing, industrial infrastructure, construction activity, logistics and water-treatment facilities. Abu Dhabi is particularly important because of its hydrocarbon and industrial base, while Dubai provides extensive trading, distribution, construction and logistics infrastructure. Domestic manufacturing capability also supports supply: Al Ghaith Industries reports 43,750 MT of calcium chloride granules and 720,000 BBL of calcium chloride brine capacity, while Union Chlorine manufactures anhydrous calcium chloride granules at 94–97% concentration.
Market Segmentation
By Product Form
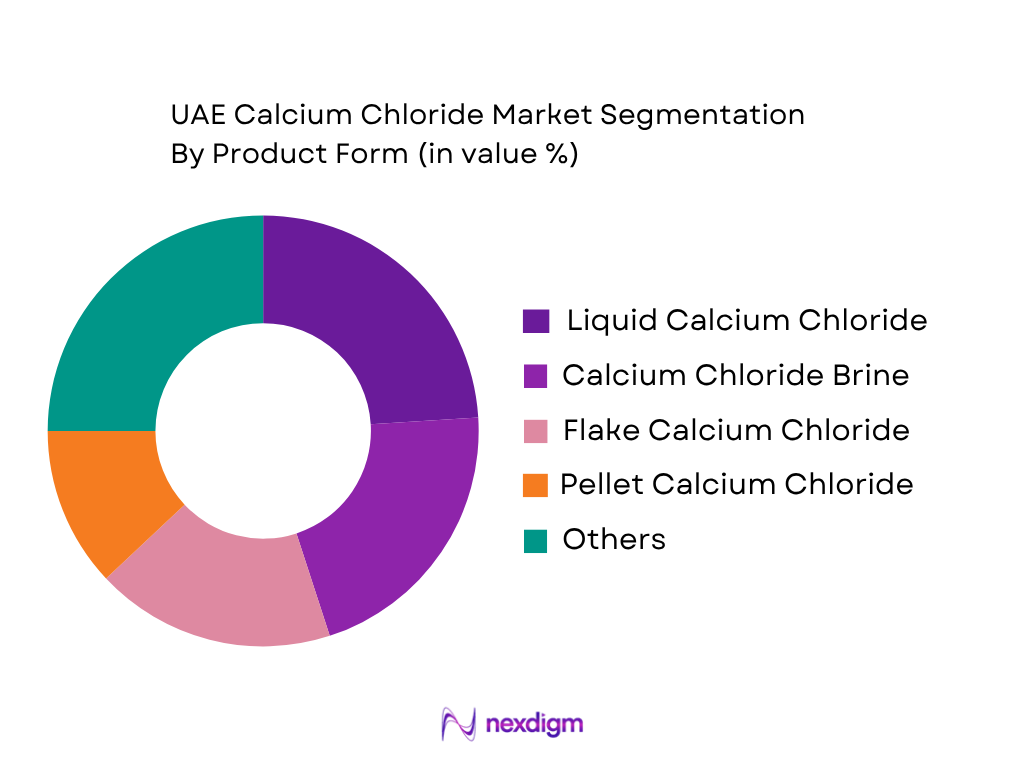
The UAE Calcium Chloride Market is segmented by product form into liquid calcium chloride, calcium chloride brine, flake calcium chloride, pellet calcium chloride, granulated calcium chloride, briquette calcium chloride, anhydrous calcium chloride and powdered calcium chloride. Liquid calcium chloride is expected to represent the dominant product form because industrial consumers can directly use liquid solutions in oilfield, water-treatment, dust-suppression and process applications without additional dissolution. The UAE’s arid climate also supports applications requiring rapid moisture management and dust control. Domestic manufacturing strengthens availability of liquid and granular formats, with Al Ghaith Industries reporting calcium chloride granules capacity of 43,750 MT and calcium chloride brine capacity of 720,000 BBL. Union Chlorine separately produces anhydrous calcium chloride granules at 94–97%, demonstrating the availability of higher-concentration products for industrial applications.
By Application
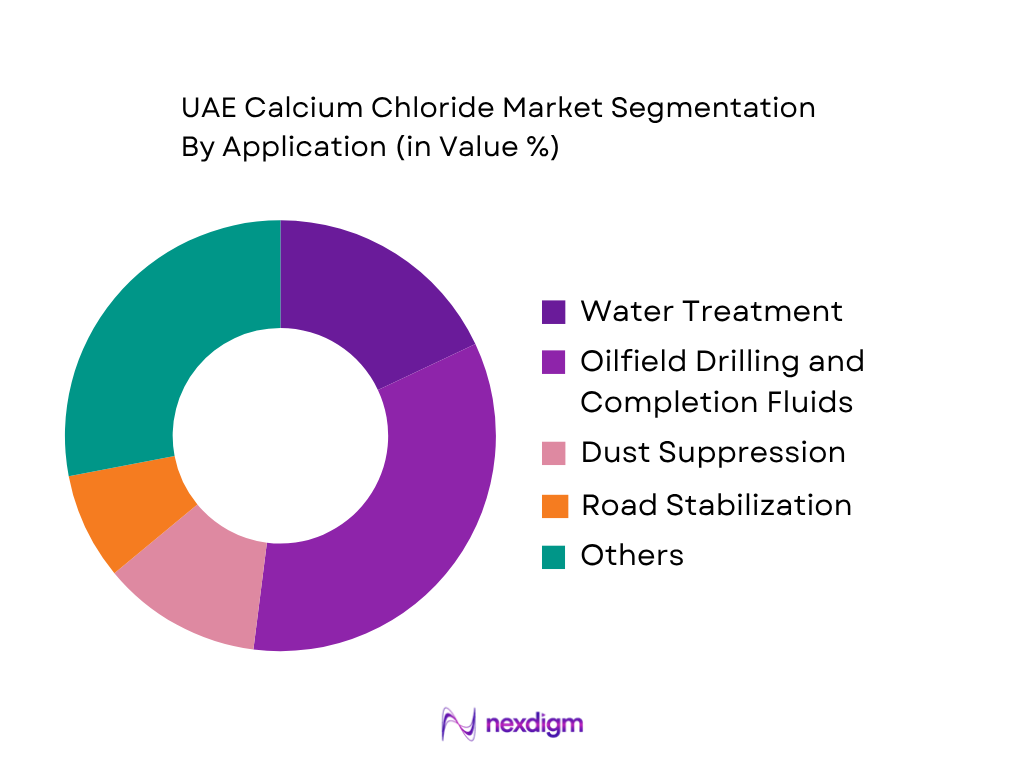
The UAE Calcium Chloride Market is segmented by application into oilfield drilling and completion fluids, water treatment, dust suppression, road stabilization, concrete acceleration, food processing, refrigeration brine, chemical processing, mining and mineral processing, and other industrial applications. Oilfield drilling and completion fluids represent a key application because calcium chloride provides high-density brine solutions used in drilling, completion and workover operations. The UAE’s petroleum industry creates recurring demand for oilfield chemicals, while domestic suppliers such as Energenix list calcium chloride within their drilling mud and completion chemical portfolio. The application also benefits from the UAE’s integrated energy infrastructure and concentration of oilfield service activities around Abu Dhabi. Calcium chloride is additionally used in production chemicals, water treatment and cementing-related applications, creating demand across several stages of oil and gas operations.
Competitive Landscape
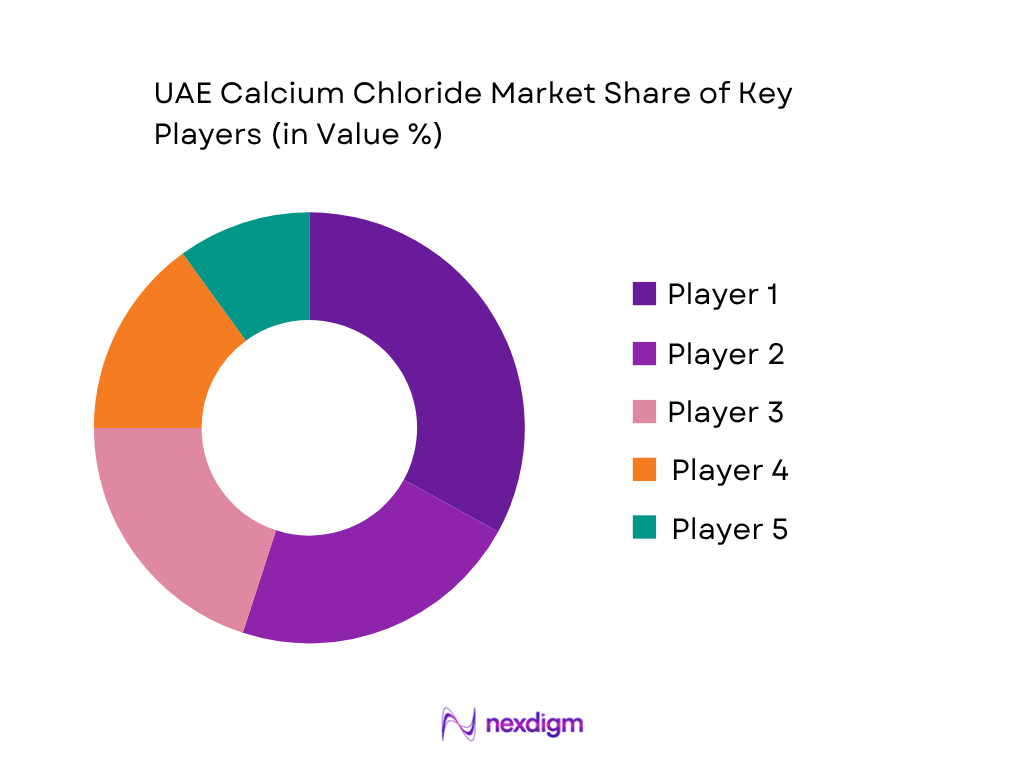
The UAE Calcium Chloride Market comprises domestic chlor-alkali manufacturers, specialty chemical suppliers, oilfield chemical providers and international chemical companies serving industrial customers. Domestic producers such as Al Ghaith Industries and Union Chlorine provide locally manufactured calcium chloride, while specialized suppliers address oilfield, water-treatment, construction, food and industrial requirements. Al Ghaith operates a UAE chlor-alkali plant and reports calcium chloride production alongside hydrochloric acid, sodium hypochlorite and other chlor-alkali products. Union Chlorine operates from Abu Dhabi and combines calcium chloride manufacturing with hydrochloric acid and other chlor-alkali products.
| Company | Establishment Year | Headquarters | Calcium Chloride Portfolio | Oilfield Applications | Water Treatment | Product Grades | UAE Supply Capability |
| Al Ghaith Industries | 2007 | Abu Dhabi, UAE | ~ | ~ | ~ | ~ | ~ |
| Union Chlorine LLC | 2013 | Abu Dhabi, UAE | ~ | ~ | ~ | ~ | ~ |
| Gulfchem Solutions | ~ | UAE | ~ | ~ | ~ | ~ | ~ |
| Energenix Oilfield & Gas Technologies | ~ | Abu Dhabi, UAE | ~ | ~ | ~ | ~ | ~ |
| NCH / Chem-Aqua | 1919 | USA / UAE operations | ~ | ~ | ~ | ~ | ~ |
UAE Calcium Chloride Market Analysis
Growth Drivers
Oil and Gas Drilling and Completion Activity
The UAE Calcium Chloride Market is strongly supported by the country’s extensive oil and gas production and associated drilling, completion, workover and well-servicing activities. ADNOC reported approximately 4.85 million barrels per day of current production capacity and around 11.5 billion standard cubic feet per day of gas capacity in its 2024 sustainability reporting. Calcium chloride is relevant to this ecosystem because concentrated calcium chloride brines are used in drilling and completion fluids where controlled density and compatibility with formation conditions are required. ADNOC also reported operations across 35 producing fields, demonstrating the breadth of the upstream asset base. Continued investment across production, gas processing and oilfield infrastructure therefore creates recurring requirements for completion-grade brines and supporting oilfield chemicals. The UAE’s broader industrial expansion further reinforces this driver: official statistics recorded AED 1.776 trillion of real GDP in 2024, with oil-related activities contributing AED 434 billion. The combination of substantial hydrocarbon operations, multiple producing assets and supporting oilfield-service activity provides a diversified demand base for calcium chloride products used in well construction and production-related applications. Source: ADNOC Sustainability Report 2024; UAE Federal Competitiveness and Statistics Centre.
Industrial Water Treatment Demand
Industrial water treatment represents another important demand driver for the UAE Calcium Chloride Market because the country’s manufacturing, construction, energy and utility infrastructure requires chemical treatment across process-water and wastewater systems. UAE official statistics reported that manufacturing contributed 13.5% of total GDP in 2024, while construction contributed 11.7%, illustrating the scale of industrial and built-environment activity that can generate requirements for water-treatment chemicals. The country’s non-oil GDP reached AED 1.342 trillion, while the overall real economy reached AED 1.776 trillion, supporting continued industrial diversification and infrastructure development. Calcium chloride is used in selected water-treatment applications including wastewater conditioning, hardness adjustment and process-water treatment, depending on system chemistry and treatment objectives. Its hygroscopic properties and ability to supply calcium ions also make it relevant to specific industrial processes where controlled calcium concentration is required. Expansion of manufacturing facilities, industrial utilities and construction-related infrastructure consequently broadens the addressable customer base beyond oilfield applications. This creates demand from industrial water-treatment operators, chemical processors, utilities and manufacturing plants while supporting recurring chemical consumption associated with continuous industrial operations. Source: UAE Federal Competitiveness and Statistics Centre.
Market Challenges
Regional Import Dependency
The UAE Calcium Chloride Market faces supply-chain challenges where certain specialized grades, concentrations and physical forms depend on international sourcing, particularly when local production does not match a customer’s technical specification or required grade. This exposure can increase procurement complexity because industrial users may require consistent concentration, low impurity levels, specific particle sizes or application-specific certification. The UAE’s position as a major international trading hub partly offsets this constraint through extensive logistics infrastructure. Official statistics recorded 147.8 million travelers through UAE airports in 2024 and 9.6% growth in transport and storage activity, reflecting the country’s substantial connectivity and logistics ecosystem. However, chemical supply chains still require controlled handling because calcium chloride is hygroscopic and can absorb atmospheric moisture during storage and transportation. Dependence on external supply for selected grades can therefore create additional requirements for inventory planning, import scheduling, warehouse protection and supplier qualification. Local manufacturers provide an important counterbalance: domestic producers manufacture calcium chloride in granular, brine and anhydrous formats. Nevertheless, differences between standard industrial grades and specialized oilfield, food or high-purity specifications mean that regional sourcing remains relevant to the market structure. Source: UAE Federal Competitiveness and Statistics Centre; UAE calcium chloride manufacturers’ published production information.
Chloride Discharge Management
Environmental management of chloride-containing streams presents a challenge for the UAE Calcium Chloride Market because industrial users must manage wastewater and process discharges according to applicable environmental requirements. Calcium chloride itself is highly soluble, meaning that applications involving significant quantities can introduce elevated chloride concentrations into wastewater streams when material is discharged rather than recovered or reused. This consideration is particularly relevant for industrial water treatment, oilfield operations, chemical processing and other applications involving brines. The UAE’s industrial base makes the issue commercially relevant: official statistics indicate that manufacturing contributed AED 239.76 billion when applying its reported 13.5% contribution to the country’s AED 1.776 trillion real GDP, while construction represented 11.7%. These activities involve extensive industrial utilities and water-management systems. Environmental controls can consequently influence chemical-selection procedures, wastewater treatment requirements, monitoring practices and operating protocols for calcium chloride users. Companies may also need to optimize dosing to avoid unnecessary chemical consumption and manage concentrated brine streams appropriately. As industrial facilities become more focused on resource efficiency and environmental compliance, suppliers with application expertise, dosing optimization and treatment-support capabilities can become increasingly important to calcium chloride customers. Source: UAE Federal Competitiveness and Statistics Centre.
Market Opportunities
Domestic Calcium Chloride Manufacturing Expansion
Domestic production expansion presents an opportunity for the UAE Calcium Chloride Market by reducing dependence on imported grades and improving responsiveness to local oilfield, industrial and water-treatment customers. Existing domestic capacity demonstrates that calcium chloride manufacturing is already integrated with the UAE’s broader chlor-alkali chemical ecosystem. Al Ghaith Industries reports 43,750 MT of calcium chloride granules capacity and 720,000 barrels of calcium chloride brine capacity, while Union Chlorine reports anhydrous calcium chloride granules at 94–97% concentration. The opportunity is supported by the scale of the country’s industrial economy: real GDP reached AED 1.776 trillion in 2024, while non-oil GDP reached AED 1.342 trillion. Manufacturing contributed 13.5% of GDP, reinforcing the industrial customer base available to domestic chemical producers. Additional local production could focus on application-specific grades, consistent concentration, improved packaging formats and products suited to oilfield brines, water treatment, food processing and construction chemicals. Greater domestic availability could also shorten procurement lead times and support technical service relationships with major industrial customers. As the UAE continues economic diversification and industrial development, expanding local calcium chloride production can strengthen integration between upstream chemical feedstocks, manufacturing, distribution and downstream industrial applications. Sources: Al Ghaith Industries; Union Chlorine; UAE Federal Competitiveness and Statistics Centre.
Oilfield Brine Applications
Oilfield brine applications provide a significant opportunity for the UAE Calcium Chloride Market because calcium chloride can be formulated into high-density brines for drilling, completion and well-intervention requirements. The opportunity is supported by the scale of UAE hydrocarbon operations. ADNOC reported approximately 4.85 million barrels per day of production capacity, around 11.5 billion standard cubic feet per day of gas capacity and 35 producing fields in its 2024 sustainability reporting. Such an extensive upstream asset base creates recurring requirements for completion fluids, workover chemicals and other production-support materials. Calcium chloride is particularly relevant where oilfield operators require brines with controlled density and predictable chemical characteristics. The opportunity extends beyond direct consumption because specialized oilfield grades can support higher-value supply arrangements involving formulation, blending, technical support and field delivery. UAE-based chemical suppliers already market calcium chloride within drilling and completion chemical portfolios, demonstrating an established application ecosystem. Expansion of upstream activity, well maintenance and production optimization can therefore create opportunities for suppliers capable of meeting oilfield specifications consistently. Local availability of suitable grades can also improve response times for operators and oilfield service companies while reducing reliance on ad hoc imports for specialized brine requirements. Source: ADNOC Sustainability Report 2024; UAE oilfield chemical suppliers.
Future Outlook
Over the forecast period, the UAE Calcium Chloride Market is expected to benefit from continued activity across oil and gas, water treatment, construction, food processing and industrial manufacturing. The country’s industrial base provides multiple demand channels rather than reliance on a single end-use industry. World Bank data show UAE GDP of USD 552.32 billion in 2024, while industry including construction accounted for 44.3 of GDP. The World Bank also identified tourism, real estate, construction, transportation and manufacturing as important contributors to UAE non-oil activity.
The market is also positioned around a combination of domestic manufacturing and imported specialty grades. Local production of calcium chloride supports industrial and oilfield requirements, while distributors provide access to additional product forms and specifications. The UAE’s role as an energy and logistics hub further supports regional redistribution of chemical products. Opportunities are expected to be particularly relevant in high-purity calcium chloride, oilfield brines, industrial water treatment, concrete applications, food processing and refrigeration.
Major Players
- Al Ghaith Industries
- Union Chlorine LLC
- Gulfchem Solutions
- Energenix Oilfield & Gas Technologies
- NCH / Chem-Aqua
- Dubi Chem Marine International
- Al Khowahir Chemicals
- OGT
- Waterline Chemicals
- Alrama Chemicals
- V Coat General Trading
- Wilco Prime
- Trice Chemicals
- SCT Chemicals FZE
- Bisley Chemicals Trading LLC
Key Target Audience
- Oil and Gas Exploration and Production Companies
- Oilfield Services and Drilling Chemical Suppliers
- Industrial Water and Wastewater Treatment Operators
- Construction Chemical and Concrete Producers
- Food and Beverage Processing Companies
- Refrigeration and Cold Chain Operators
- Investments and Venture Capitalist Firms (Industrial Chemicals, Oilfield Services and Water Infrastructure)
- Government and Regulatory Bodies (Ministry of Climate Change and Environment, Abu Dhabi Department of Energy, Dubai Municipality)
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves constructing an ecosystem map covering calcium chloride manufacturers, importers, distributors and major consuming industries across the UAE. Desk research is used to identify product forms, grades, production capabilities, import dependence and end-use applications. Particular attention is given to oilfield chemicals, water treatment, construction, food processing and refrigeration demand.
Step 2: Market Analysis and Construction
This phase involves compiling historical information on calcium chloride production, imports, exports, consumption and application-level demand. The analysis connects supply volumes with oil and gas activity, industrial water treatment, construction, food processing and other consuming sectors. Product-form and grade-level demand are subsequently reconciled to establish the market structure.
Step 3: Hypothesis Validation and Expert Consultation
Market hypotheses are developed around product-form adoption, domestic production, imported grades, oilfield demand and industrial consumption patterns. These hypotheses are validated through consultations with manufacturers, distributors, oilfield chemical suppliers, water-treatment companies and industrial purchasers. Industry feedback is used to validate supply-chain dynamics and application-specific demand assumptions.
Step 4: Research Synthesis and Final Output
The final stage integrates demand-side and supply-side findings into a consolidated UAE Calcium Chloride Market assessment. Manufacturer capabilities, distribution networks, application requirements and end-use demand are cross-checked to improve consistency. The resulting analysis supports segmentation, competitive benchmarking, market forecasting and strategic assessment of domestic production versus imported supply.

- Executive Summary
- Research Methodology (Market Definition and Scope, UAE Calcium Chloride Market Classification, Domestic Production Assessment, Import Dependency Analysis, Product Grade Mapping, Application-Level Demand Assessment, End-Use Industry Assessment, Supply Chain Mapping, Demand-Side Assessment, Supply-Side Assessment, Primary Industry Interviews, Top-Down Analysis, Bottom-Up Analysis, Data Triangulation, Forecasting Framework, Assumptions and Limitations)

- Definition and Scope
- UAE Calcium Chloride Industry Evolution
- UAE Calcium Chloride Value Chain Analysis
- UAE Calcium Chloride Supply Chain Analysis

- Growth Drivers (Oil and Gas Drilling and Completion Activity, Chlor-Alkali Chemical Manufacturing, Industrial Water Treatment Demand, Construction and Infrastructure Development, Oilfield Service Expansion, Food Processing Activity, Industrial Dust Suppression Requirements, Refrigeration and Cold Chain Infrastructure)
- Market Challenges (Regional Import Dependency, Product Grade Availability, Raw Material and Hydrochloric Acid Supply, Chloride Discharge Management, Moisture-Sensitive Storage Requirements, Logistics and Bulk Transportation, Product Quality Consistency, Competition from Sodium Chloride and Magnesium Chloride)
- Market Opportunities (Domestic Calcium Chloride Manufacturing Expansion, High-Purity Grade Development, Oilfield Brine Applications, Industrial Water Treatment, Food Grade Calcium Chloride, Construction and Concrete Applications, Mining and Mineral Processing, Refrigeration and Thermal Management)
- Market Trends (Anhydrous Calcium Chloride Adoption, Oilfield Brine Utilization, Food Grade Applications, Industrial Water Treatment Integration, Bulk Chemical Distribution, High-Purity Grade Demand, Dust Suppression Applications, Application-Specific Calcium Chloride Formulations)
- Government Regulations and Standards (UAE Federal Chemicals Management Requirements, Ministry of Climate Change and Environment Requirements, Environmental Protection Requirements, Industrial Chemical Handling Regulations, Abu Dhabi Environmental Regulations, Dubai Municipality Chemical Requirements, Food Safety Standards, Occupational Health and Safety Requirements, Hazardous Materials Transportation Requirements)

- By Market Value (2020-2025)
- By Calcium Chloride Consumption Volume (2020-2025)
- By Domestic Calcium Chloride Production Volume (2020-2025)
- By Calcium Chloride Import Volume (2020-2025)
- By Calcium Chloride Export Volume (2020-2025)

- By Product Form (In Value %)
Liquid Calcium Chloride
Calcium Chloride Brine
Flake Calcium Chloride
Pellet Calcium Chloride
Granulated Calcium Chloride
Briquette Calcium Chloride
Anhydrous Calcium Chloride
Powdered Calcium Chloride - By Grade (In Value %)
Industrial Grade Calcium Chloride
Food Grade Calcium Chloride
Technical Grade Calcium Chloride
Oilfield Grade Calcium Chloride
High-Purity Calcium Chloride
Pharmaceutical Grade Calcium Chloride
Water Treatment Grade Calcium Chloride - By Application (In Value %)
Oilfield Drilling and Completion Fluids
Water Treatment
Dust Suppression
Road Stabilization
Concrete Acceleration
Food Processing
Refrigeration Brine
Chemical Processing
Mining and Mineral Processing - By End-Use Industry (In Value %)
Oil and Gas
Petrochemicals and Chemical Manufacturing
Water and Wastewater Treatment
Construction and Infrastructure
Food and Beverage Processing
Mining and Mineral Processing
Refrigeration and Cold Chain
Road Maintenance
Pharmaceutical Manufacturing
Agriculture and Horticulture - By Distribution Channel (In Value %)
Direct Manufacturer Sales
Industrial Chemical Distributors
Chemical Importers and Traders
Oilfield Chemical Suppliers
Water Treatment Chemical Suppliers
Food Ingredient Distributors
Construction Chemical Distributors
Specialty Chemical Suppliers
Online Industrial Chemical Platforms

- Market Share of Major Players (By Revenue, Sales Volume, Product Form, Grade, Application, End-Use Industry, Domestic Manufacturing, Import and Distribution Activity)
- Cross Comparison Parameters (Calcium Chloride Product Portfolio Breadth, Domestic Production and Import Capability, Product Grade Availability, Oilfield Brine and Drilling Chemical Capability, Industrial Water Treatment Coverage, Bulk Storage and Logistics Capacity, Distribution Network Across UAE and GCC, Technical Support and Application-Specific Formulation Capability)
- SWOT Analysis of Major Players
- Detailed Profiles of Major Companies
Al Ghaith Industries
Union Chlorine LLC
Dubi Chem Marine International
Al Khowahir Chemicals
Gulfchem Solutions
OGT
Energenix Oilfield and Gas Technologies
Waterline Chemicals
Alrama Chemicals
V Coat General Trading
Wilco Prime
Trice Chemicals
SCT Chemicals FZE
Bisley Chemicals Trading LLC
Petronoc Worldwide FZE

- Oilfield Drilling and Completion Chemical Procurement Assessment
- Oil and Gas Production Chemical Requirement Analysis
- Industrial Water Treatment Procurement Assessment
- Construction Chemical Requirement Analysis
- Food Processing Calcium Chloride Requirement Assessment
- Refrigeration and Cold Chain Requirement Analysis
- Mining and Mineral Processing Requirement Assessment

- By Market Value (2026-2035)
- By Calcium Chloride Consumption Volume (2026-2035)
- By Domestic Calcium Chloride Production Volume (2026-2035)
- By Calcium Chloride Import Volume (2026-2035)
- By Calcium Chloride Export Volume (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
