
 Download PDF
Market Overview
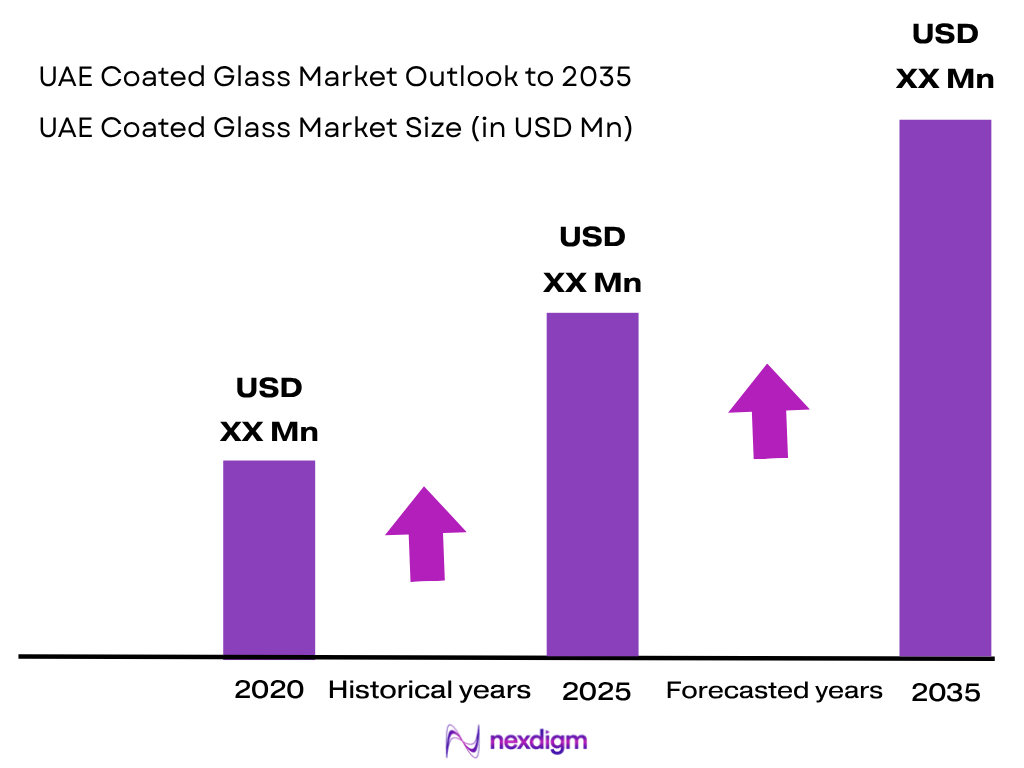
The UAE coated glass market is valued at approximately USD ~ billion, based on historical market assessment, supported by strong demand from commercial buildings, high-rise developments, hospitality infrastructure, and energy-efficient façade systems. The market size is driven by increasing adoption of low-E glass, solar control coatings, and advanced glazing solutions required for reducing cooling loads in extreme climatic conditions. The UAE construction sector recorded strong activity, with Dubai and Abu Dhabi contributing significantly through large-scale real estate and infrastructure projects.
The UAE coated glass market is dominated by major urban centers including Dubai, Abu Dhabi, and Sharjah due to their concentration of high-rise buildings, luxury hospitality developments, commercial towers, and government infrastructure projects. Dubai leads demand due to extensive skyscraper construction, premium façade applications, and large-scale mixed-use developments. Abu Dhabi contributes through government-led infrastructure expansion, institutional buildings, and sustainable construction initiatives, while Sharjah supports demand through residential and commercial development activities.
Market Segmentation
By Coating Technology Type
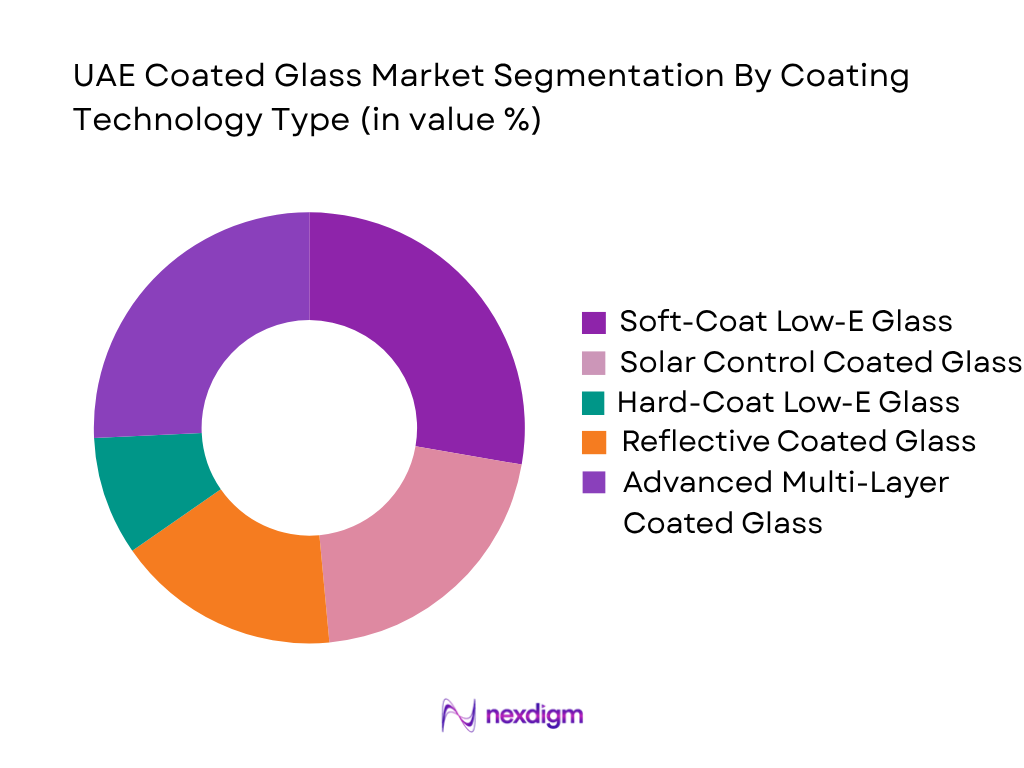
The UAE coated glass market is segmented by coating technology type into soft-coat low-E glass, hard-coat low-E glass, solar control coated glass, reflective coated glass, and advanced multi-layer coated glass. Soft-coat low-E glass holds a dominant market share in the UAE coated glass market due to its superior thermal insulation capability and growing adoption in premium commercial buildings and high-rise developments. The technology provides improved energy efficiency by reducing heat transfer through building envelopes, which is highly relevant in the UAE’s hot climate conditions. Solar control coated glass also maintains strong demand due to the requirement for reducing solar heat gain and improving indoor comfort. The increasing focus on green buildings and energy-efficient construction continues to support demand for advanced coating technologies.
By Application System
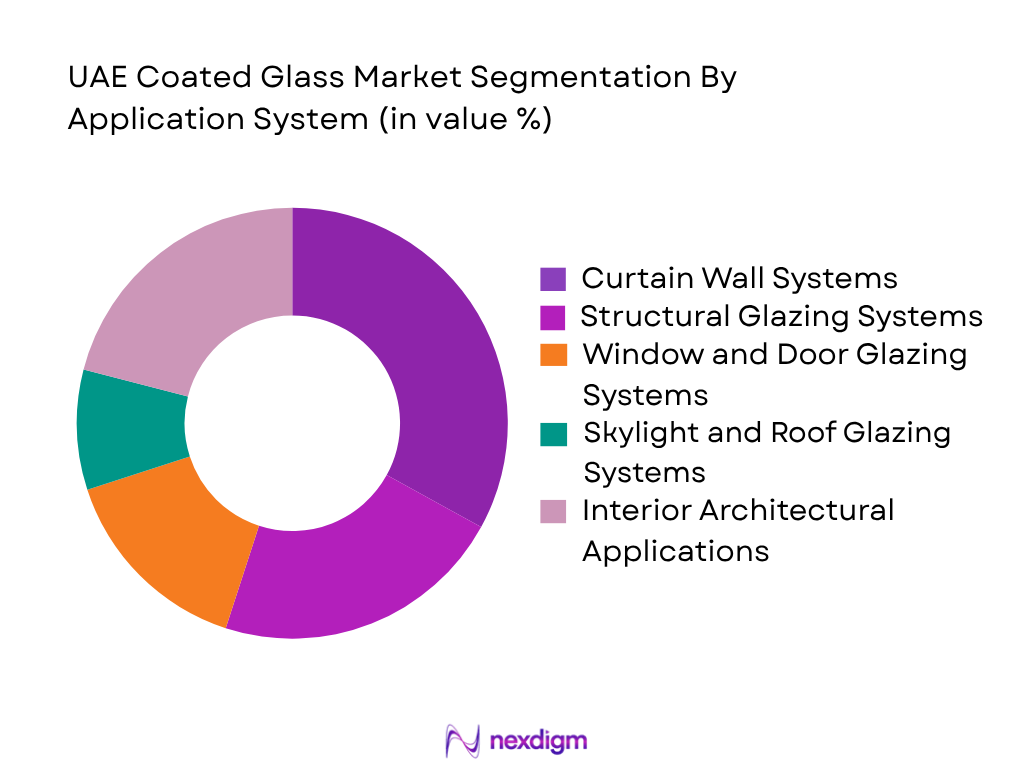
The UAE coated glass market is segmented by application system into curtain wall systems, structural glazing systems, window and door glazing systems, skylight glazing systems, and interior architectural applications. Curtain wall systems account for the dominant market share due to extensive utilization in commercial towers, hotels, shopping malls, and premium residential buildings across Dubai and Abu Dhabi. High-rise construction projects require advanced façade solutions that provide thermal performance, aesthetic appeal, and durability, increasing coated glass adoption. Structural glazing systems are also gaining importance due to modern architectural designs requiring seamless glass façades. The expansion of mixed-use developments and luxury hospitality projects continues to increase demand for high-performance coated glass applications across the UAE construction industry.
Competitive Landscape
The UAE coated glass market is characterized by the presence of global glass manufacturers, regional suppliers, and domestic glass processors. Major players compete through coating technology capabilities, product portfolio strength, façade project experience, and regional supply networks. International companies dominate advanced coated glass technologies, while local processors play an important role in fabrication, customization, and project execution.
| Company | Establishment Year | Headquarters | Low-E Glass Portfolio | Solar Control Glass Capability | UAE Project Presence | Coating Technology | Distribution Network | Façade Glass Solutions |
| Saint-Gobain | 1665 | France | ~ | ~ | ~ | ~ | ~ | ~ |
| AGC Inc. | 1907 | Japan | ~ | ~ | ~ | ~ | ~ | ~ |
| Guardian Industries | 1932 | USA | ~ | ~ | ~ | ~ | ~ | ~ |
| NSG Group | 1918 | Japan | ~ | ~ | ~ | ~ | ~ | ~ |
| Emirates Float Glass | 2009 | UAE | ~ | ~ | ~ | ~ | ~ | ~ |
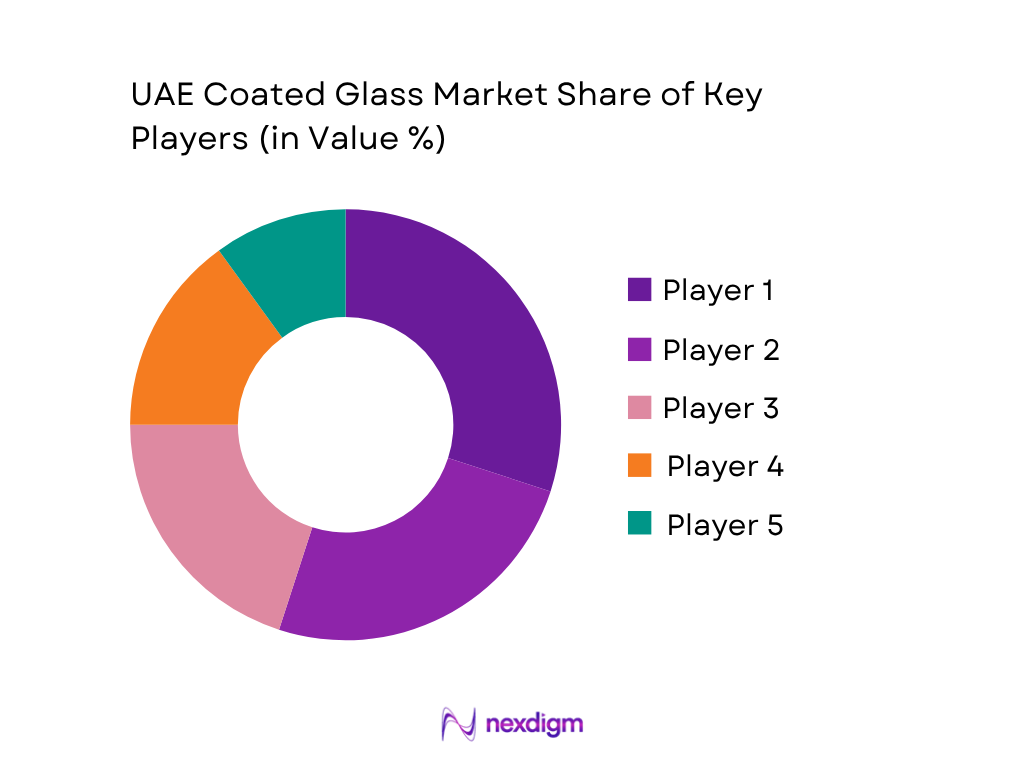
UAE Coated Glass Market Analysis
Growth Drivers
Expansion of Construction and Sustainable Building Infrastructure
The UAE coated glass market is supported by continuous expansion in construction activities, particularly in commercial towers, residential developments, hospitality assets, and infrastructure projects requiring high-performance glazing solutions. The UAE construction sector remains a major contributor to coated glass demand, with the World Bank reporting that the UAE economy recorded GDP growth of approximately 3.6 trillion AED in current prices, reflecting continued economic activity supporting infrastructure investments. According to the UAE Ministry of Energy and Infrastructure, the country has implemented multiple sustainable building initiatives focused on improving energy efficiency and reducing building energy consumption. Dubai Municipality’s green building regulations encourage the adoption of energy-efficient materials, including advanced glazing systems such as low-E and solar control coated glass. The UAE population exceeded 11 million residents, according to Federal Competitiveness and Statistics Centre data, increasing demand for residential and commercial infrastructure. The concentration of construction projects in Dubai and Abu Dhabi, including high-rise buildings, airports, hotels, and mixed-use developments, continues to create demand for coated glass solutions that improve thermal performance, daylight management, and façade efficiency.
Rising Demand for Energy-Efficient Glass Due to Extreme Climatic Conditions
The UAE coated glass market is driven by increasing demand for solar control and low-emissivity glazing solutions due to the country’s high cooling requirements caused by elevated temperatures throughout the year. According to the UAE National Center of Meteorology, several UAE regions experience summer temperatures exceeding 45°C, increasing the importance of technologies that reduce solar heat gain in buildings. The International Energy Agency highlights that buildings account for a significant portion of global energy consumption, encouraging countries to improve building envelope efficiency through advanced materials. The UAE Energy Strategy focuses on improving energy efficiency and reducing emissions intensity across sectors, supporting adoption of efficient construction materials. The UAE electricity consumption reached more than 150 TWh, according to International Energy Agency energy statistics, reflecting substantial energy demand from residential and commercial cooling systems. Coated glass technologies such as low-E glass and solar control glass help reduce heat transmission through façades, supporting lower cooling loads and improved indoor comfort. These factors are increasing adoption across commercial buildings, hospitality projects, and premium residential developments.
Market Challenges
Dependence on Imported Coated Glass and Limited Domestic Coating Capacity
The UAE coated glass market faces challenges due to dependence on international suppliers for advanced coated glass products, particularly specialized low-E glass, triple silver coatings, and high-performance architectural glazing solutions. Although the UAE has domestic float glass and glass processing capabilities, advanced coating technologies remain concentrated among global manufacturers. According to the UAE Ministry of Economy industrial statistics, the country’s manufacturing sector contributes significantly to GDP, but specialized glass production remains a smaller industrial segment compared with metals, chemicals, and construction materials. The UAE imported significant volumes of glass and glass products, with international trade data from the United Nations Comtrade database showing continued reliance on imported glass materials for construction applications. Dependence on imports exposes the coated glass supply chain to logistics disruptions, international freight fluctuations, and global raw material availability. The requirement for specialized coating equipment, controlled manufacturing environments, and technical expertise creates barriers for establishing additional local coating facilities. This dependency increases procurement complexity for large-scale façade projects requiring customized coated glass specifications.
Complex Installation Requirements and Technical Specification Challenges
The UAE coated glass market experiences challenges associated with complex installation requirements, technical approvals, and performance specifications required for advanced façade systems. Coated glass applications require precise handling, fabrication, and installation procedures to maintain coating integrity and achieve expected thermal performance. According to the UAE Building Code framework implemented through government authorities, construction materials must comply with safety, performance, and durability requirements before being approved for building applications. The UAE construction sector employs more than 500,000 workers according to International Labour Organization estimates, highlighting the scale of workforce involved in construction activities; however, specialized façade installation requires additional technical expertise. Large commercial and high-rise developments require coordination between architects, façade consultants, contractors, glass processors, and developers, increasing project complexity. Improper specification or installation can affect factors such as solar heat gain performance, insulation efficiency, and long-term durability. These technical requirements create challenges for smaller contractors and increase the importance of specialized fabrication and installation capabilities within the coated glass ecosystem.
Market Opportunities
Growth of Green Buildings and Energy-Efficient Construction Projects
The UAE coated glass market has significant opportunities from increasing investment in sustainable buildings and energy-efficient construction practices. Government initiatives promoting sustainable development are encouraging the use of advanced building materials that improve energy performance. Dubai Municipality’s green building regulations require improved environmental performance in new developments, supporting demand for materials such as low-E coated glass and solar control glazing. The UAE Net Zero 2050 strategic initiative further strengthens focus on reducing emissions from buildings and infrastructure. According to the UAE Ministry of Climate Change and Environment, the country continues to expand sustainability programs across urban development and infrastructure sectors. The UAE recorded more than 10 million international visitors according to Dubai Department of Economy and Tourism statistics, supporting continued development of hotels, resorts, and commercial facilities requiring premium façade solutions. Increasing construction of energy-efficient offices, luxury hotels, and smart buildings creates opportunities for manufacturers offering advanced coated glass technologies with improved thermal insulation, daylight optimization, and sustainability performance.
Expansion of High-Performance Façade Systems and Advanced Architectural Glass Applications
The UAE coated glass market presents opportunities through increasing adoption of advanced façade systems in skyscrapers, commercial complexes, airports, and premium residential projects. The UAE continues to develop large-scale architectural projects requiring innovative building envelope solutions. According to the UAE General Civil Aviation Authority, passenger traffic through major airports exceeded tens of millions of travelers, supporting continued infrastructure modernization and expansion projects requiring advanced glazing systems. Dubai and Abu Dhabi remain major hubs for high-value construction projects, including mixed-use developments, hospitality assets, and commercial towers that require specialized coated glass applications. Advances in glazing technologies, including double silver low-E coatings, triple silver coatings, and multifunctional glass solutions, create opportunities for suppliers to provide customized performance-based products. Increasing emphasis on reducing operational energy consumption, improving occupant comfort, and achieving sustainability certifications is encouraging architects and developers to specify higher-performance glazing materials. These trends support future demand for premium coated glass solutions across UAE construction and infrastructure sectors.
Future Outlook
Over the next decade, the UAE coated glass market is expected to show significant growth driven by increasing adoption of energy-efficient building materials, expansion of high-rise construction, and rising demand for sustainable façade solutions. Growth will be supported by green building regulations, advanced glazing technologies, and increasing investment in premium commercial and residential infrastructure. The market is expected to witness greater adoption of low-E coatings, solar control glass, and smart glazing solutions. The UAE coated glass market is forecasted to grow at a CAGR of approximately ~% during the forecast period.
Major Players
- Saint-Gobain
- AGC Inc.
- Guardian Industries
- NSG Group
- Şişecam
- Vitro Architectural Glass
- Xinyi Glass Holdings
- Kibing Group
- Emirates Float Glass
- Glass LLC
- Al Abbar Aluminium
- Dubai Glass Industry
- Gulf Glass Industries
- Saudi American Glass
- Oman Glass LLC
Key Target Audience
- Real Estate Developers and Construction Companies
- Façade Engineering and Building Envelope Companies
- Architectural Glass Fabricators and Processors
- Aluminium Façade System Manufacturers
- Investments and Venture Capitalist Firms (Real Estate Investment Funds, Infrastructure Investment Funds, Private Equity Firms)
- Government and Regulatory Bodies (Dubai Municipality, Abu Dhabi Department of Municipalities and Transport, Ministry of Energy and Infrastructure UAE)
- Commercial Building Owners and Facility Management Companies
- Glass Manufacturing and Building Material Companies
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves developing a comprehensive ecosystem map covering manufacturers, glass processors, façade contractors, developers, regulatory bodies, and end users operating within the UAE coated glass market. This stage involves extensive secondary research through industry databases, construction reports, trade publications, and company information to identify major market variables influencing demand, supply, and technology adoption.
Step 2: Market Analysis and Construction
In this phase, historical market information related to coated glass consumption, application demand, product categories, and construction activities is analyzed. The assessment includes evaluation of architectural glass demand, façade installation trends, import dependency, processing capacity, and pricing patterns to develop a structured market estimation framework.
Step 3: Hypothesis Validation and Expert Consultation
Market assumptions are validated through primary interviews with industry participants including coated glass manufacturers, façade contractors, glass processors, developers, and procurement specialists. These discussions provide operational insights related to product preferences, competitive positioning, technology adoption, and future market opportunities.
Step 4: Research Synthesis and Final Output
The final stage integrates quantitative and qualitative findings from primary and secondary research sources. Data obtained from manufacturers, distributors, and end users is analyzed to validate market sizing, segmentation, competitive analysis, and future growth projections for the UAE coated glass market.

- Executive Summary
- Research Methodology (Market Definition and Scope, UAE Coated Glass Market Classification, Architectural Glass Demand Assessment, Low-E Glass Consumption Mapping, Solar Control Glass Demand Assessment, High-Rise Façade Glazing Requirement Analysis, Commercial Building Energy Efficiency Assessment, Residential and Hospitality Glazing Demand Mapping, Curtain Wall and Building Envelope Glass Consumption Assessment, Domestic Glass Processing and Fabrication Capacity Assessment, Coated Glass Import Dependency Analysis, Magnetron Sputtering, Pyrolytic Coating, Silver Coating and Advanced Low-E Glass Technology Assessment)

- Definition and Scope
- UAE Coated Glass Industry Evolution and Development of Energy Efficient Glazing, Solar Control Glass Adoption, Low-E Glass Integration, Façade Engineering, Sustainable Building Envelope and High Performance Architectural Glass Ecosystem
- Soft-Coat Low-E Glass, Hard-Coat Low-E Glass, Solar Control Coated Glass, Reflective Coated Glass, Double Silver Low-E Glass, Triple Silver Low-E Glass
- UAE Coated Glass Value Chain Analysis
- UAE Coated Glass Supply Chain Analysis
- Silica Sand Supplier, Float Glass Manufacturer, Coating Technology Provider, Glass Processor, Architectural Glass Fabricator, Façade Contractor, Aluminium System Supplier, Real Estate Developer, Building Material Distributor, Project Procurement Company

- Growth Drivers (Expansion of High-Rise Construction Projects, Increasing Demand for Energy Efficient Buildings, Growth of Commercial Real Estate Development, Extreme Solar Heat Conditions Driving Solar Control Glass Adoption, Green Building Certification Requirements, Expansion of Luxury Hospitality Projects, Government Infrastructure Investments, Sustainable Building Envelope Requirements, Increasing Façade Modernization Activities)
- Market Challenges (High Dependence on Imported Coated Glass Products, Limited Domestic Coating Manufacturing Capacity, High Initial Cost Compared with Conventional Glass, Volatility in Float Glass Prices, Complex Installation Requirements, Dependence on Skilled Façade Installation Workforce, Long Project Approval Cycles)
- Market Opportunities (Growth of Net Zero Buildings, Energy Efficient Retrofit Projects, Expansion of Premium Low-E Glass Demand, Increasing Adoption of Triple Silver Coated Glass, Smart Glass Integration, Sustainable Construction Material Demand, Local Coating Facility Development, Advanced Façade System Expansion)
- Market Trends (Low-E Glass Adoption, Triple Silver Coating Technology Growth, High Performance Curtain Wall Systems, Energy Performance Based Building Design, Digital Façade Engineering, Sustainable Glass Procurement, Large Format Architectural Glass Usage, Smart Glass Integration, Vacuum Insulated Glass Adoption, Customized Coated Glass Solutions)
- Regulatory and Standards Landscape (UAE Building Code Requirements, Dubai Green Building Regulations, Estidama Pearl Rating Requirements, Energy Efficiency Standards, Façade Performance Regulations, Glass Safety Standards, Sustainability Certification Requirements, Building Envelope Thermal Performance Standards)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Competition Ecosystem

- By Market Value (2020-2025)
- By Coated Glass Consumption Volume (2020-2025)
- By Low-E Glass Consumption Volume (2020-2025)
- By Solar Control Glass Consumption Volume (2020-2025)
- By Curtain Wall and Façade Glass Consumption Volume (2020-2025)
- By Insulating Glass Unit (IGU) Coated Glass Consumption Volume (2020-2025)
- By Commercial Building Coated Glass Consumption Volume (2020-2025)

- By Coating Technology Type (In Value %)
Magnetron Sputtered Coated Glass
Soft-Coat Low-E Glass
Hard-Coat Low-E Glass
Solar Control Coated Glass
Reflective Coated Glass
Pyrolytic Coated Glass
Double Silver Low-E Glass
Triple Silver Low-E Glass
Anti-Reflective Coated Glass
Self-Cleaning Coated Glass - By Glass Product Type (In Value %)
Clear Float Glass
Tinted Float Glass
Low Iron Glass
Tempered Coated Glass
Laminated Coated Glass
Heat Strengthened Coated Glass
Insulating Glass Units (IGU)
Double Glazed Units
Triple Glazed Units
Vacuum Insulated Glass - By Application System (In Value %)
Curtain Wall Systems
Structural Glazing Systems
Unitized Façade Systems
Window and Door Glazing Systems
Skylight and Roof Glazing Systems
Canopy and Atrium Glazing
Interior Architectural Glazing
Solar Control Building Envelope Systems
Energy Efficient Building Glazing Systems - By End-Use Industry (In Value %)
Commercial Buildings
Residential Towers and Villas
Hospitality and Tourism Infrastructure
Retail and Shopping Malls
Airports and Transportation Infrastructure
Healthcare Facilities
Educational Institutions
Industrial and Manufacturing Facilities
Government Buildings
Renewable Energy Projects - By Region (In Value %)
Dubai
Abu Dhabi
Sharjah
Ras Al Khaimah
Ajman
Fujairah
Other Emirates

- Market Share of Major Players (By UAE Revenue, Coated Glass Sales Volume, Low-E Glass Sales Volume, Solar Control Glass Sales Volume, Façade Project Exposure, End-Use Industry, UAE Processing and Fabrication Footprint, Distribution and Technical Support Coverage)
- Cross Comparison Parameters (UAE Coated Glass Revenue, Low-E and Solar Control Glass Portfolio Breadth, Magnetron Sputtering and Coating Technology Capability, High-Rise Façade and Curtain Wall Project Exposure, UAE Glass Processing and Fabrication Capacity, Large Format Architectural Glass Availability, Energy Performance and Sustainability Certification Capability, UAE Distribution Network and Technical Support Footprint)
- SWOT Analysis of Major Players
- Competitive Positioning Matrix
- Pricing and Coated Glass Category Benchmarking
- Detailed Profiles of Major Companies
Saint-Gobain
AGC Inc.
Guardian Industries
NSG Group
Şişecam
Vitro Architectural Glass
Xinyi Glass Holdings
Kibing Group
Emirates Float Glass
Glass LLC
Al Abbar Aluminium
Dubai Glass Industry
Gulf Glass Industries
Saudi American Glass
Oman Glass LLC

- High-Rise Commercial Building Coated Glass Requirement Assessment
- Residential Tower and Villa Glazing Preference Analysis
- Hospitality Project Façade Glass Specification Assessment
- Retail Mall Architectural Glass Procurement Analysis
- Airport and Transportation Infrastructure Glazing Requirement Analysis
- Real Estate Developer Energy Efficiency Requirement Assessment
- Architect and Façade Consultant Glass Specification Analysis
- Aluminium Façade Contractor Coated Glass Procurement Assessment
- Government Infrastructure Sustainable Glass Procurement Analysis
- Industrial Building Energy Efficient Glazing Requirement Assessment

- By Market Value (2026-2035)
- By Coated Glass Consumption Volume (2026-2035)
- By Low-E Glass Consumption Volume (2026-2035)
- By Solar Control Glass Consumption Volume (2026-2035)
- By Curtain Wall and Façade Glass Consumption Volume (2026-2035)
- By Insulating Glass Unit (IGU) Coated Glass Consumption Volume (2026-2035)
- By Commercial Building Coated Glass Consumption Volume (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
