
 Download PDF
Market Overview
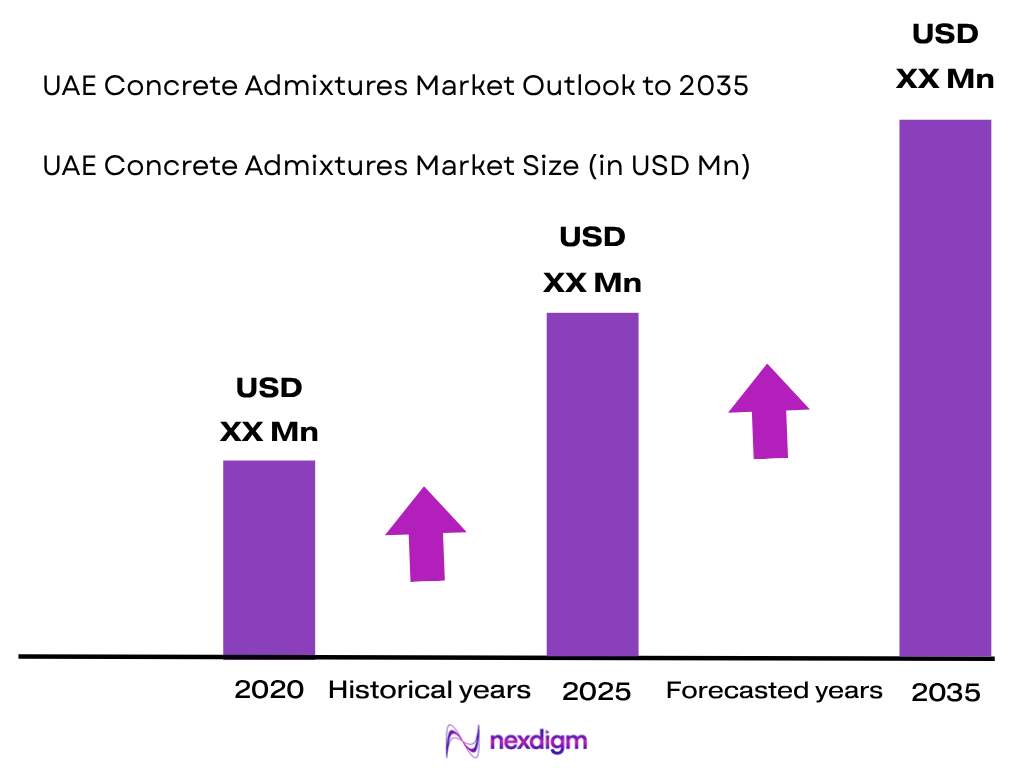
The UAE Concrete Admixtures Market is valued at approximately USD ~XX million, supported by high concrete consumption across buildings and infrastructure. Abu Dhabi construction value added increased from more than AED97 billion to AED107.4 billion across the latest two annual observations, while the UAE construction sector reached approximately AED150 billion in the latest period. This activity sustains demand for superplasticizers, retarders, waterproofing systems and durability-enhancing admixtures used in high-performance concrete.
Dubai and Abu Dhabi dominate UAE admixture demand because they concentrate high-rise construction, residential communities, transport infrastructure and major concrete-intensive developments. Dubai real-estate transactions increased from AED634 billion to AED761 billion across the latest two annual observations, while Abu Dhabi construction value added rose from more than AED97 billion to AED107.4 billion. Their project scale favours ready-mix concrete, pumped concrete, high-strength mixes, long-slump-retention systems and marine-durability admixtures.
Market Segmentation
By Admixture Type
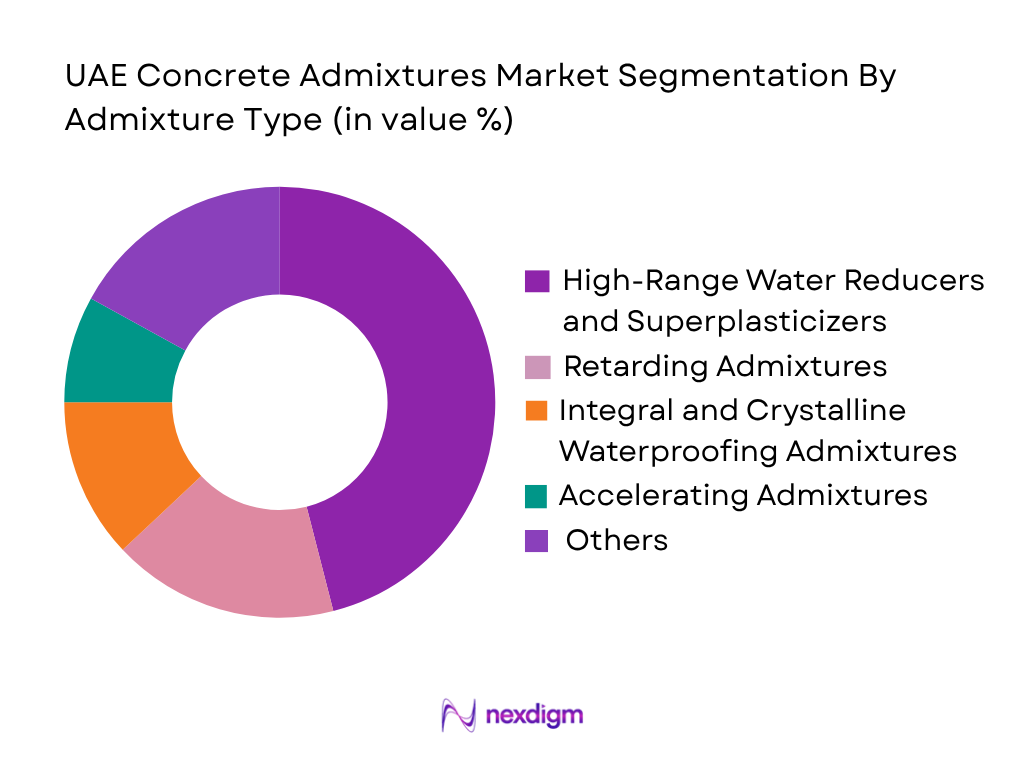
The UAE Concrete Admixtures Market is segmented by admixture type into high-range water reducers and superplasticizers, retarders, integral and crystalline waterproofing admixtures, accelerators, viscosity-modifying admixtures, corrosion and shrinkage-control products, and other specialty admixtures. High-range water reducers and superplasticizers dominate this segmentation because UAE concrete frequently requires low water-cement ratios while retaining sufficient workability for long transport times and high-rise pumping under hot climatic conditions. PCE-based technologies are particularly suitable for high-strength, high-performance and self-compacting concrete because they combine substantial water reduction with adjustable slump retention. Their role is also increasing as producers incorporate GGBS, silica fume and other supplementary cementitious materials into durable and lower-carbon mixes. Suppliers operating in the UAE offer dedicated superplasticizer systems for pumpability, workability retention and high-performance concrete, confirming the category’s central role in modern mix design.
By Application
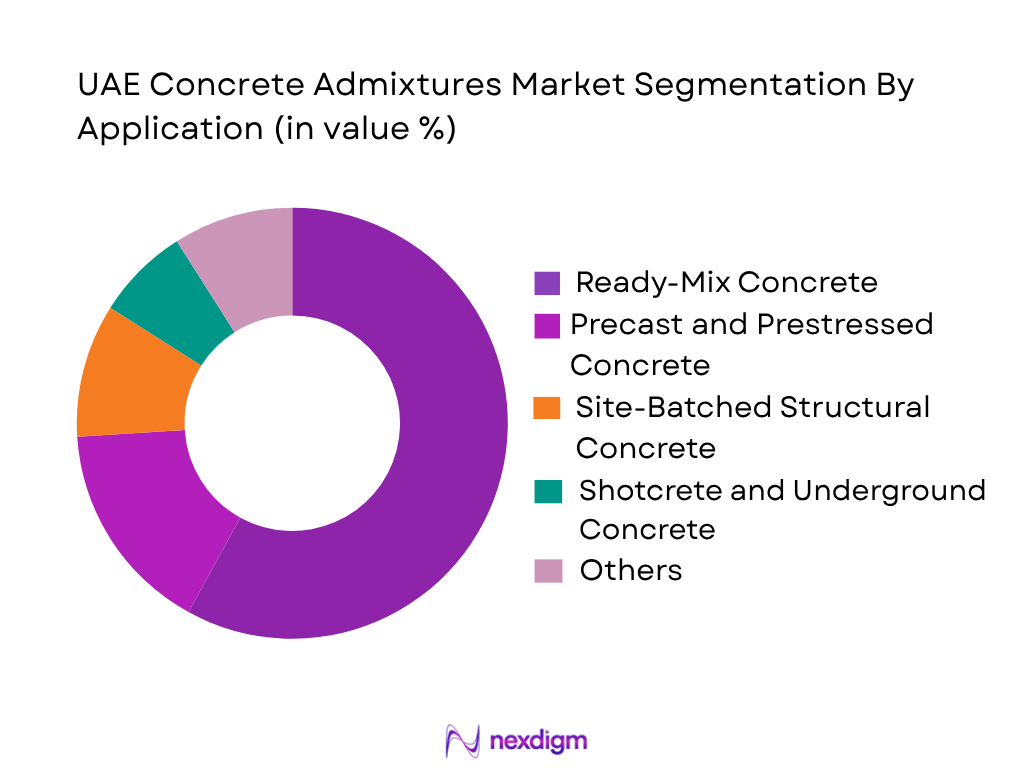
The UAE Concrete Admixtures Market is segmented by application into ready-mix concrete, precast and prestressed concrete, site-batched structural concrete, shotcrete and underground concrete, marine and water-retaining structures, and other applications. Ready-mix concrete dominates the market because the UAE’s urban construction model relies heavily on centralized batching plants supplying residential towers, commercial developments, hotels, infrastructure and large foundations. Dubai Municipality requires ready-mix factories, precast factories and central batching units to obtain conformity certification, reinforcing the importance of controlled plant production and accurate admixture dosing. Ready-mix operations also face demanding slump-retention requirements because concrete may travel through dense urban areas before being pumped vertically or placed in large pours. Superplasticizers and retarders therefore become integral to daily production rather than specialty additions. High-strength towers and mass foundations further increase admixture intensity because concrete performance must be maintained from batching through pumping, placement and curing under high ambient temperatures.
Competitive Landscape
The UAE Concrete Admixtures Market combines global construction-chemical groups with companies possessing long-established local manufacturing and technical-service capabilities. Sika, Al Gurg Fosroc, CHRYSO, GCP/Saint-Gobain and Mapei compete across ready-mix, precast, infrastructure and specialty concrete applications. Competition centres on PCE formulation, hot-weather slump retention, local raw-material compatibility, laboratory support, bulk delivery and sustainable mix optimisation. Industry consolidation has intensified: Saint-Gobain acquired CHRYSO, completed GCP Applied Technologies in 2022 and completed Fosroc in February 2025, creating a particularly broad construction-chemicals platform.
| Company | Establishment Year | Headquarters | PCE / Superplasticizer Capability | Hot-Weather & Slump-Retention Capability | Waterproofing & Durability Portfolio | Low-Carbon / SCM Compatibility | UAE Manufacturing Presence | Technical & Field Support |
| Sika | 1910 | Baar, Switzerland | ~ | ~ | ~ | ~ | ~ | ~ |
| Al Gurg Fosroc | 1975 | Dubai, UAE | ~ | ~ | ~ | ~ | ~ | ~ |
| GCP Applied Technologies / Saint-Gobain | 2015 | Alpharetta, Georgia, US | ~ | ~ | ~ | ~ | ~ | ~ |
| CHRYSO | 1942 | Courbevoie, France | ~ | ~ | ~ | ~ | ~ | ~ |
| Mapei | 1937 | Milan, Italy | ~ | ~ | ~ | ~ | ~ | ~ |
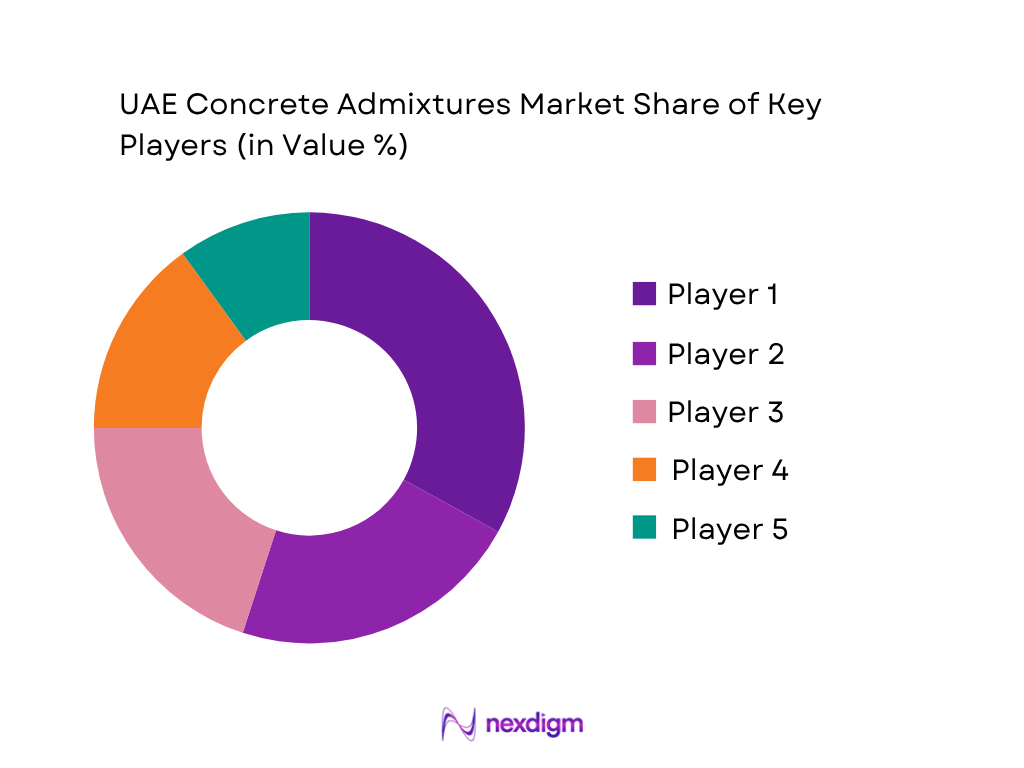
UAE Concrete Admixtures Market Analysis
Growth Drivers
Expanding Construction Activity Increasing Ready-Mix and Admixture Consumption
The UAE Concrete Admixtures Market is being supported by sustained construction activity across residential, commercial, infrastructure and industrial developments, which directly raises ready-mix concrete output and chemical-admixture consumption. The Ministry of Energy and Infrastructure valued the UAE construction sector at approximately AED150 billion in 2024, demonstrating the scale of concrete-intensive activity. Dubai Municipality and Digital Dubai recorded 18,114 buildings under construction in 2024, including 9,297 private villas, 6,277 investment villas, 1,024 multi-storey buildings, 969 public buildings and 547 industrial buildings. This project mix creates recurring requirements for PCE superplasticizers, retarders, pumping aids, waterproofing additives and viscosity modifiers because concrete must satisfy different strength, placement and durability specifications. High-rise and public-building construction also increases demand for low water-cement ratios and extended workability. The macroeconomic environment reinforces this construction demand: World Bank data place UAE GDP at US$552.32 billion in 2024, with GDP per capita of US$50,273.5. The combination of a large construction pipeline and a high-value economy therefore strengthens consumption of performance-oriented concrete admixtures across centralized batching plants and project-specific concrete supply chains.
Abu Dhabi Building Expansion Supporting High-Performance Concrete Demand
Abu Dhabi’s accelerating built-environment development is another major growth driver for the UAE Concrete Admixtures Market because large-scale housing, commercial, infrastructure and industrial projects require durable and highly workable concrete formulations. Statistics Centre – Abu Dhabi reported construction-sector value added of AED107.4 billion in 2024, while the emirate added 29,415 new residential and commercial units, bringing the total stock to 783,970 units. Total buildings increased to 299,360, illustrating the continuing expansion of the physical asset base requiring ready-mix, precast and structural concrete. These conditions support demand for superplasticizers that improve water reduction and pumpability, retarders designed for long delivery and placement cycles, corrosion inhibitors for aggressive exposure conditions and integral waterproofing technologies used in basements, foundations and infrastructure. Concrete admixtures become increasingly important where contractors must balance strength, workability and service-life requirements without excessive cement or water usage. At the national level, World Bank data record US$552.32 billion of GDP in 2024 and US$50,273.5 of GDP per capita, indicating an economic base capable of sustaining sophisticated construction specifications and major capital projects. Abu Dhabi’s construction scale therefore supports continued adoption of technically advanced admixture systems.
Market Challenges
Extreme Ambient Temperatures Increasing Slump-Retention and Setting-Control Complexity
The UAE Concrete Admixtures Market faces a significant technical challenge from high ambient temperatures because elevated concrete temperatures accelerate cement hydration, reduce workable time and increase the risk of rapid slump loss during transport and pumping. National Center of Meteorology forecasts for Dubai during August 2024 showed maximum temperatures reaching 43°C, 45°C, 45°C, 44°C and 46°C across a five-day period, with minimum temperatures remaining between 31°C and 34°C. These conditions are especially demanding for ready-mix concrete serving high-rise and large infrastructure projects, where concrete can remain in transit before undergoing prolonged pumping and placement. Admixture suppliers must therefore tailor PCE molecular structures, retardation packages and slump-retention systems to different cement types, supplementary cementitious materials and aggregate moisture conditions. Over-retardation can delay finishing and strength development, while insufficient retention can trigger re-dosing or rejected loads. The challenge operates within a substantial national economy: World Bank data report UAE GDP of US$552.32 billion in 2024 and GDP per capita of US$50,273.5. Maintaining concrete consistency across this construction-intensive economy requires sophisticated laboratory testing, mix trials and field-level technical support rather than standardized admixture dosing alone.
Ready-Mix Supply Pressure Creating Quality and Delivery Constraints
Rapid construction expansion is placing pressure on the UAE ready-mix ecosystem, creating a challenge for admixture suppliers because shortages or production bottlenecks can disrupt dosage consistency, delivery schedules and project-level concrete performance. Dubai Municipality convened leading ready-mix and contracting companies in 2026 specifically to discuss concrete-market shortages and their effects on construction timelines. The Municipality reported 23,270 buildings under construction during 2025, representing 40,028,453 square metres of built-up area. Earlier, during the first half of 2025, the authority carried out more than 25,000 construction-site inspections covering over 18,800 buildings and more than 36 million square metres. This degree of simultaneous project activity increases pressure on batching capacity, bulk admixture storage, tanker logistics and technical support teams. Admixture suppliers must ensure continuous availability of superplasticizers, retarders and specialty products while maintaining formulation consistency across high-volume deliveries. Substituting an unavailable product can also require new mix trials and compatibility validation. World Bank data place UAE GDP at US$552.32 billion in 2024, highlighting the scale of the economy supporting this construction intensity. Supply reliability and plant-level technical service are therefore central competitive challenges alongside product chemistry itself.
Market Opportunities
Green Concrete Adoption Expanding Demand for SCM-Compatible Admixtures
The UAE’s push toward lower-impact construction creates a future growth opportunity for concrete admixture suppliers capable of enabling greater use of supplementary cementitious materials while preserving strength, flowability and setting performance. Dubai Municipality reported that it oversaw the use of more than 1.5 million cubic metres of green concrete during the first half of 2025, demonstrating that sustainable concrete has moved into substantial commercial deployment rather than remaining limited to pilot projects. During the same period, the Municipality inspected more than 18,800 buildings under construction covering over 36 million square metres, creating a broad project base in which lower-carbon concrete specifications can be expanded. High GGBS, silica-fume and other reduced-clinker mixes can exhibit different adsorption, early-strength and slump-retention behaviour than conventional Portland-cement mixes, creating opportunities for optimized PCE superplasticizers, accelerators and hydration-control technologies. The economic base supporting construction innovation is significant: World Bank data report UAE GDP of US$552.32 billion in 2024 and GDP per capita of US$50,273.5. Suppliers that can formulate admixtures around locally used binders and aggregates can therefore participate in the transition toward lower-cement, higher-durability concrete while maintaining construction productivity and specification compliance.
High-Rise and Specialized Building Pipeline Creating Scope for Advanced PCE Systems
The concentration of technically demanding buildings in Dubai creates a strong future opportunity for advanced concrete admixtures designed for high-strength, pumped and self-compacting concrete. Digital Dubai recorded 1,024 multi-storey buildings under construction in 2024, alongside 969 public buildings and 547 industrial buildings, within a total pipeline of 18,114 structures supervised by Dubai Municipality. Multi-storey developments require concrete that can maintain rheological stability while travelling through long pipelines and substantial vertical pumping heights, which creates demand for high-range PCE water reducers, viscosity modifiers and extended slump-retention systems. Public and industrial buildings additionally create opportunities for waterproofing, shrinkage control, durability enhancement and specialized flooring admixtures. Dubai’s real estate ecosystem reinforces the underlying project flow: Dubai Land Department recorded 226,000 real estate transactions valued at AED761 billion in 2024, indicating substantial development and investment activity supporting new construction. At the national level, the World Bank reported US$552.32 billion of GDP in 2024, with GDP per capita of US$50,273.5. This combination of dense vertical development and strong capital formation provides admixture suppliers with opportunities to move from commodity products toward customized high-performance formulations supported by laboratory and site-level technical services.
Future Outlook
The UAE Concrete Admixtures Market is expected to expand at approximately ~XX% CAGR during 2026-2035, supported by continued urban expansion, transport infrastructure, large residential developments and increasingly demanding concrete specifications. Product demand should migrate further toward PCE-based superplasticizers, extended-slump-retention technologies, durability enhancers and admixtures designed for low-carbon binders. Local production, polymer synthesis and customer-specific formulations are also expected to become stronger competitive differentiators.
Infrastructure will remain a major consumption engine. The UAE Ministry of Energy and Infrastructure stated that the construction sector was valued at approximately AED150 billion in 2024. By 2026, the national transport and road agenda included projects valued above AED170 billion through 2030, indicating a substantial infrastructure base requiring structural concrete, bridges, pavements, foundations and associated admixture technologies.
Major Players
- Sika UAE LLC
- Al Gurg Fosroc LLC
- GCP Applied Technologies / Saint-Gobain Construction Chemicals
- CHRYSO Middle East
- Mapei Construction Chemicals LLC
- MC-Bauchemie Middle East LLC
- CONMIX Ltd.
- Normet
- Cementaid Middle East FZE
- Kryton International Inc.
- Krystaline Technology SA
- Castech Middle East FZE
- AIM Industries
- Stoncor Middle East LLC / Euclid Chemical
- Penetron International
Key Target Audience
- Concrete Admixture and Construction Chemical Manufacturers
- Ready-Mix Concrete Producers
- Precast and Prestressed Concrete Manufacturers
- Main Contractors and Infrastructure Contractors
- Real Estate Developers and Mega-Project Owners
- Cement, SCM and Concrete Raw-Material Suppliers
- Investments and Venture Capitalist Firms
- Government and Regulatory Bodies (Dubai Municipality, Abu Dhabi Department of Municipalities and Transport, Ministry of Energy and Infrastructure, Emirates Authority for Standardization and Metrology Functions under the Ministry of Industry and Advanced Technology)
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves constructing an ecosystem map covering admixture producers, raw-material suppliers, ready-mix companies, precast producers, contractors, developers and regulatory bodies. Key variables include concrete output, admixture dosage, PCE penetration, building and infrastructure activity, local manufacturing, cement chemistry, hot-weather performance requirements and application-specific product intensity.
Step 2: Market Analysis and Construction
Historical information is compiled across ready-mix, precast, infrastructure, marine and specialist concrete applications. The bottom-up approach estimates admixture consumption using concrete volumes, dosage ranges and application mix, while the top-down approach evaluates construction activity and construction-chemical demand. Both calculations are reconciled to establish the market baseline and segmentation structure.
Step 3: Hypothesis Validation and Expert Consultation
Market hypotheses are validated through computer-assisted telephone interviews and technical discussions with admixture manufacturers, concrete technologists, batching-plant operators, contractors and procurement professionals. Interviews assess PCE usage, slump-retention requirements, mix compatibility, technical qualification, waterproofing adoption, bulk supply models, local formulation practices and supplier selection criteria.
Step 4: Research Synthesis and Final Output
Primary findings are triangulated with Dubai Municipality certification information, government construction indicators, company disclosures and project activity. Market sizing is validated through top-down and bottom-up comparisons. Forecast assumptions then incorporate construction activity, ready-mix penetration, PCE migration, local manufacturing, infrastructure spending, low-carbon concrete adoption and increasing specification of high-performance admixtures.

- Executive Summary
- Research Methodology (Market Definitions and Assumptions, UAE Concrete Admixtures Market Classification, Chemical Admixture Scope, Ready-Mix Concrete Assessment, Precast Concrete Assessment, Site-Batched Concrete Assessment, Plasticizer Assessment, Superplasticizer Assessment, PCE-Based Admixture Assessment, SNF-Based Admixture Assessment, Retarding Admixture Assessment, Accelerating Admixture Assessment, Waterproofing Admixture Assessment, Crystalline Admixture Assessment, Corrosion-Inhibiting Admixture Assessment, Shrinkage-Reducing Admixture Assessment, Viscosity-Modifying Admixture Assessment, High-Performance Concrete Assessment, Self-Compacting Concrete Assessment, Hot-Weather Concreting Assessment, Slump-Retention Assessment, Water-Reduction Assessment, Chloride and Sulfate Resistance Assessment, Marine Concrete Assessment, Low-Carbon Concrete Assessment, Ready-Mix Plant Mapping, Precast Plant Mapping, Supply-Side Assessment, Demand-Side Assessment, Top-Down Market Sizing, Bottom-Up Market Sizing, Primary Industry Interviews, Construction Project Pipeline Assessment, Admixture Dosage Modelling, Local Manufacturing Assessment, Import Assessment, Data Triangulation, Forecasting Framework)

- Definition and Scope
- UAE Concrete Admixtures Industry Evolution and Development of Conventional Water Reducers, Lignosulfonate-Based Plasticizers, Sulfonated Naphthalene Formaldehyde Superplasticizers, Polycarboxylate Ether Superplasticizers, Extended Slump-Retention Admixtures, Retarding Admixtures, Accelerating Admixtures, Viscosity-Modifying Admixtures, Integral Waterproofing Admixtures, Crystalline Waterproofing Technologies, Corrosion-Inhibiting Admixtures, Shrinkage-Reducing Admixtures, High-Performance Concrete Technologies, Self-Compacting Concrete Technologies, Hot-Weather Concrete Solutions, Low-Carbon Concrete Admixtures, High-Strength Concrete Applications, Marine Concrete Durability Solutions
- Concrete Admixtures Value Chain Analysis
- Concrete Admixtures Supply Chain Analysis
- PCE Monomer Suppliers, Acrylic Polymer Suppliers, Lignosulfonate Suppliers, Naphthalene-Based Chemical Suppliers, Specialty Chemical Manufacturers, Concrete Admixture Manufacturers, Local Polymer Blending Facilities, Ready-Mix Concrete Producers, Precast Concrete Manufacturers, Construction Chemical Distributors, Main Contractors, Infrastructure Contractors, Real Estate Developers, Concrete Technology Laboratories, Material Testing and Certification Providers, Bulk Chemical Logistics Providers, Municipal Authorities

- Growth Drivers (Dubai Urban Development, Abu Dhabi Infrastructure Expansion, High-Rise Construction, Residential Development, Transport Infrastructure, Data Centre Construction, Hospitality Projects, Ready-Mix Concrete Demand, High-Performance Concrete Adoption, Hot-Weather Concreting Requirements, Marine Infrastructure, Low-Carbon Concrete Adoption)
- Market Challenges (Cement Chemistry Variability, Aggregate Quality Variability, Extreme Ambient Temperature, Rapid Slump Loss, Long Concrete Delivery Distances, Raw Material Import Dependence, Polymer Feedstock Volatility, Ready-Mix Price Competition, Admixture-Cement Compatibility, Technical Qualification Requirements, Quality Consistency, Concrete Supply Bottlenecks)
- Market Opportunities (PCE Superplasticizer Penetration, Low-Carbon Concrete Admixtures, Extended Slump-Retention Technologies, High-Strength Concrete, Self-Compacting Concrete, Precast Automation, Crystalline Waterproofing Admixtures, Corrosion Inhibitors, Marine Concrete Durability, Data Centre Construction, Tunnel and Underground Concrete, Local Polymer Blending, AI-Assisted Concrete Mix Optimization)
- Market Trends (PCE-Based Water Reducers, Long Slump-Retention Admixtures, Cement Optimization, SCM-Compatible Admixtures, Reduced Clinker Concrete, High Pumpability Concrete, Self-Compacting Concrete, Integral Waterproofing, Crystalline Technologies, Digital Concrete Monitoring, Automated Dosing, Customized Mix-Specific Admixtures, Locally Formulated Polymer Systems)
- Government Regulations and Standards (Dubai Municipality Ready-Mix Certification, Dubai Municipality Concrete Admixture Conformity Requirements, BS EN 934-2 Concrete Admixture Requirements, ASTM C494 Requirements, BS EN 206 Concrete Requirements, ACI Hot-Weather Concreting Requirements, Al Sa’fat Green Building System, Abu Dhabi Construction Specifications, Estidama Pearl Rating Requirements, Product Conformity Requirements)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Concrete Admixtures Manufacturing and Construction Project Ecosystem

- By Market Value (2020-2025)
- By Admixture Consumption Volume (2020-2025)
- By Superplasticizer Consumption Volume (2020-2025)
- By PCE-Based Admixture Consumption (2020-2025)
- By Retarding Admixture Consumption (2020-2025)
- By Waterproofing Admixture Consumption (2020-2025)
- By Ready-Mix Concrete Admixture Consumption (2020-2025)
- By Precast Concrete Admixture Consumption (2020-2025)
- By Infrastructure Concrete Admixture Consumption (2020-2025)
- By High-Rise Building Admixture Consumption (2020-2025)
- By Marine and Coastal Concrete Admixture Consumption (2020-2025)
- By Locally Manufactured Admixture Consumption (2020-2025)
- By Imported Admixture Consumption (2020-2025)

- By Admixture Type (In Value %)
Plasticizers and Water Reducers
High-Range Water Reducers and Superplasticizers
Retarding Admixtures
Accelerating Admixtures
Viscosity-Modifying Admixtures
Air-Entraining Admixtures
Integral Waterproofing Admixtures
Crystalline Waterproofing Admixtures
Corrosion-Inhibiting Admixtures
Shrinkage-Reducing Admixtures
Hydration-Control Admixtures
Anti-Washout Admixtures
Pumping Aids
Specialty Performance Admixtures - By Chemical Technology (In Value %)
Polycarboxylate Ether-Based Admixtures
Sulfonated Naphthalene Formaldehyde-Based Admixtures
Sulfonated Melamine Formaldehyde-Based Admixtures
Lignosulfonate-Based Admixtures
Acrylic Polymer-Based Admixtures
Polymer-Modified Hybrid Admixtures
Crystalline Reactive Chemicals
Hydrophobic Pore-Blocking Admixtures
Calcium Nitrate-Based Corrosion Inhibitors
Non-Chloride Accelerator Chemistries
Other Specialty Chemistries - By Application (In Value %)
Ready-Mix Concrete
Precast Concrete
Prestressed Concrete
Site-Batched Concrete
Shotcrete and Sprayed Concrete
Piling Concrete
Raft Foundation Concrete
Mass Foundation Concrete
Pumped High-Rise Concrete
Tunnel and Underground Concrete
Marine and Coastal Concrete
Water-Retaining Structures
Industrial Flooring Concrete
Road and Pavement Concrete - By Performance Requirement (In Value %)
Extended Slump Retention
High Water Reduction
High Early Strength
Delayed Setting
Rapid Setting
Improved Pumpability
Self-Compacting Performance
Segregation Control
Reduced Permeability
Chloride Resistance
Sulfate Resistance
Corrosion Protection
Crack and Shrinkage Control
High-Temperature Concrete Performance - By Source (In Value %)
Locally Manufactured Admixtures
Locally Blended Admixtures
Imported Finished Admixtures
Imported Raw Materials with Local Formulation - By Region (In Value %)
Dubai
Abu Dhabi
Sharjah
Ras Al Khaimah
Ajman
Fujairah
Umm Al Quwain

- Market Share of Major Players (By UAE Revenue, Admixture Consumption Volume, Superplasticizer Volume, PCE-Based Admixture Portfolio, Ready-Mix Concrete Exposure, Precast Concrete Exposure, Infrastructure Project Exposure, High-Rise Project Portfolio, Marine Concrete Portfolio, Local Manufacturing Capacity, Polymer Blending Capability, Technical Laboratory Capability, Bulk Delivery Network, Regional Distribution Coverage, Low-Carbon Concrete Capability)
- Cross Comparison Parameters (PCE Superplasticizer Portfolio Breadth, Hot-Weather Slump-Retention Capability, Ready-Mix and Precast Customer Coverage, UAE Manufacturing and Blending Capability, Low-Carbon and SCM Compatibility, Marine and Durability Admixture Capability, Technical Laboratory and Mix-Design Support, Bulk Delivery and Field-Service Network)
- SWOT Analysis of Major Players
- Competitive Positioning Matrix
- Major Companies
Sika UAE LLC
Al Gurg Fosroc LLC
GCP Applied Technologies / Saint-Gobain Construction Chemicals
CHRYSO Middle East
Mapei Construction Chemicals LLC
MC-Bauchemie Middle East LLC
CONMIX Ltd.
Normet
Cementaid Middle East FZE
Kryton International Inc.
Krystaline Technology SA
Castech Middle East FZE
AIM Industries
Stoncor Middle East LLC / Euclid Chemical
Penetron International

- Ready-Mix Concrete Producer Requirement Assessment
- Precast Concrete Manufacturer Requirement Assessment
- Main Contractor Procurement Assessment
- High-Rise Building Concrete Requirement Assessment
- Infrastructure Contractor Requirement Assessment
- Marine and Coastal Concrete Requirement Assessment
- Real Estate Developer Concrete Specification Assessment
- Concrete Technology Consultant Requirement Assessment
- Low-Carbon Concrete Requirement Assessment
- Hot-Weather Concrete Performance Requirement Assessment
- Superplasticizer Compatibility Assessment
- Technical Laboratory and Field Service Requirement Assessment

- By Market Value (2026-2035)
- By Admixture Consumption Volume (2026-2035)
- By Superplasticizer Consumption Volume (2026-2035)
- By PCE-Based Admixture Consumption (2026-2035)
- By Retarding Admixture Consumption (2026-2035)
- By Waterproofing Admixture Consumption (2026-2035)
- By Ready-Mix Concrete Admixture Consumption (2026-2035)
- By Precast Concrete Admixture Consumption (2026-2035)
- By Infrastructure Concrete Admixture Consumption (2026-2035)
- By High-Rise Building Admixture Consumption (2026-2035)
- By Marine and Coastal Concrete Admixture Consumption (2026-2035)
- By Locally Manufactured Admixture Consumption (2026-2035)
- By Imported Admixture Consumption (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
