
 Download PDF
Market Overview
The UAE Dump Truck Market is valued at approximately ~USD million, based on historical market assessment, and is supported by construction, quarrying, infrastructure development and heavy-material transportation. Construction output expanded from AED 134.9 billion to AED 154.0 billion across the latest two annual periods, while Dubai’s road network reached 18,990 lane-km. Large-scale building, road, industrial and earthmoving activity sustains demand for road-legal tippers, rock-body trucks and off-highway haulers.
Dubai, Abu Dhabi, Ras Al Khaimah, Fujairah and Sharjah are the principal UAE Dump Truck Market demand centers. Dubai benefits from large construction, logistics and road-development activity, while Abu Dhabi combines major infrastructure, industrial and energy projects. Ras Al Khaimah and Fujairah are strategically important because quarrying and aggregate operations generate intensive rock-haulage requirements. The UAE construction sector recorded AED 154.0 billion of output, while Dubai had 2.5 million registered vehicles, reinforcing its large commercial transport ecosystem.
Market Segmentation
By Dump Truck Type
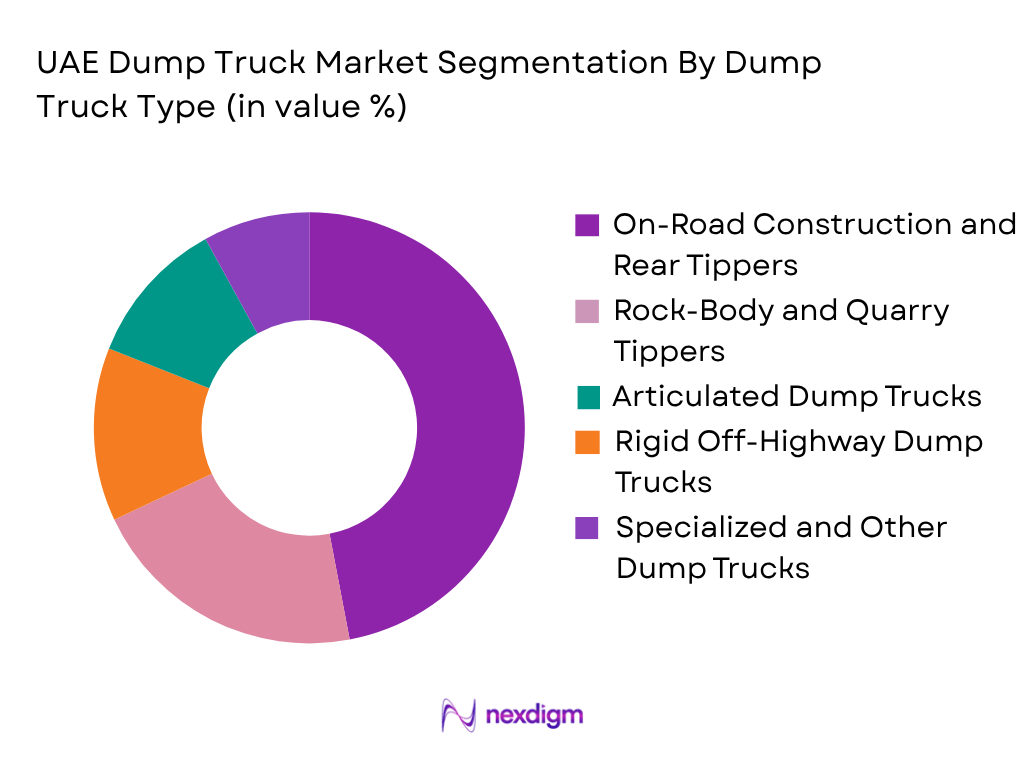
The UAE Dump Truck Market is segmented into on-road rear tippers, construction and rock-body tippers, articulated dump trucks, rigid off-highway dump trucks and specialized heavy haulers. On-road construction and rear tippers represent the dominant subsegment because they can operate across public roads, construction sites, aggregate yards, infrastructure projects and industrial developments. Their broader operating flexibility makes them more applicable to UAE contractors than mine-specific rigid haul trucks. The federal heavy-vehicle framework permits gross weights reaching 65 tonnes for six-axle vehicles, enabling high-capacity road-based configurations where axle-loading requirements are satisfied. Six-by-four and eight-by-four chassis are particularly relevant for earth, aggregate and construction-material transport because they combine payload capability with road mobility. Articulated dump trucks remain important in quarry and difficult-terrain operations, especially where loose surfaces and steep haul roads require higher traction. Rigid off-highway trucks address more specialized high-payload quarry and heavy earthmoving operations.
By Application Type
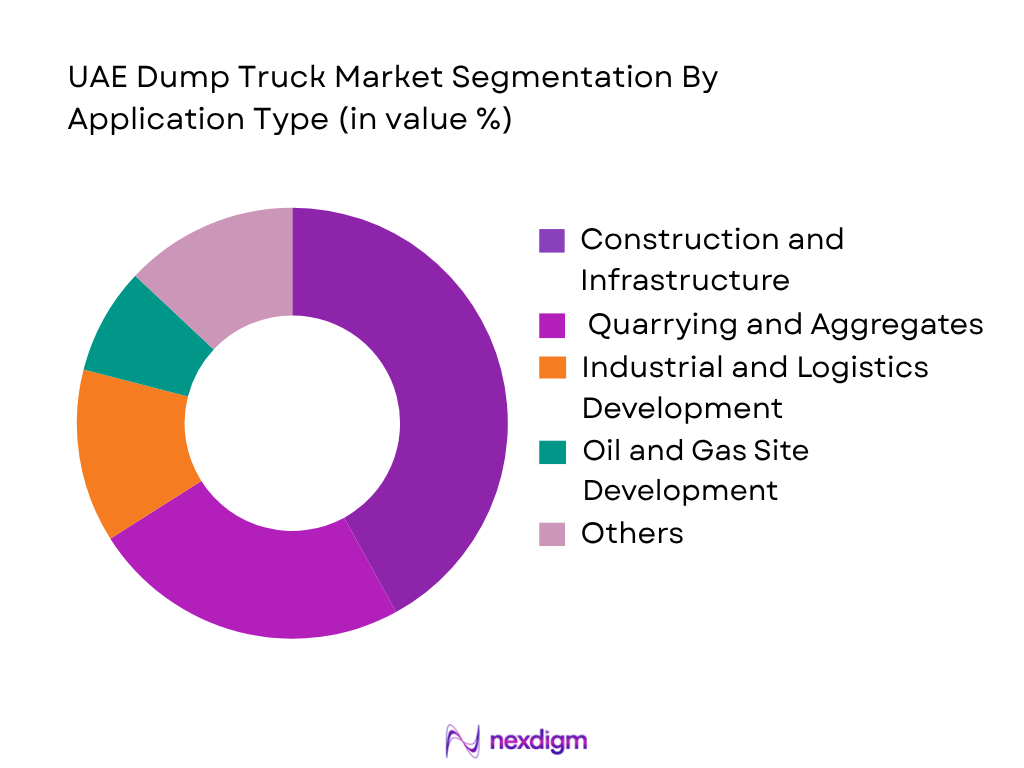
The UAE Dump Truck Market is segmented into construction and infrastructure, quarrying and aggregates, industrial and logistics development, oil and gas site development, municipal works and other specialized applications. Construction and infrastructure represent the dominant subsegment because dump trucks are required throughout excavation, site preparation, road building, aggregate delivery, demolition and earthmoving operations. UAE construction output reached AED 154.0 billion, creating a substantial underlying workload for heavy tipper fleets. Quarrying and aggregates form another structurally important segment because limestone, crushed stone and rock must be moved from quarry faces to crushers, stockpiles and construction customers. Ras Al Khaimah and Fujairah are particularly relevant to this operating model. Industrial developments, ports and logistics zones additionally require earthmoving and site-development fleets. Consequently, fleet operators need vehicles capable of operating under high ambient temperatures, dusty conditions, intensive duty cycles and repeated loaded-unloaded movements while maintaining acceptable uptime.
Competitive Landscape
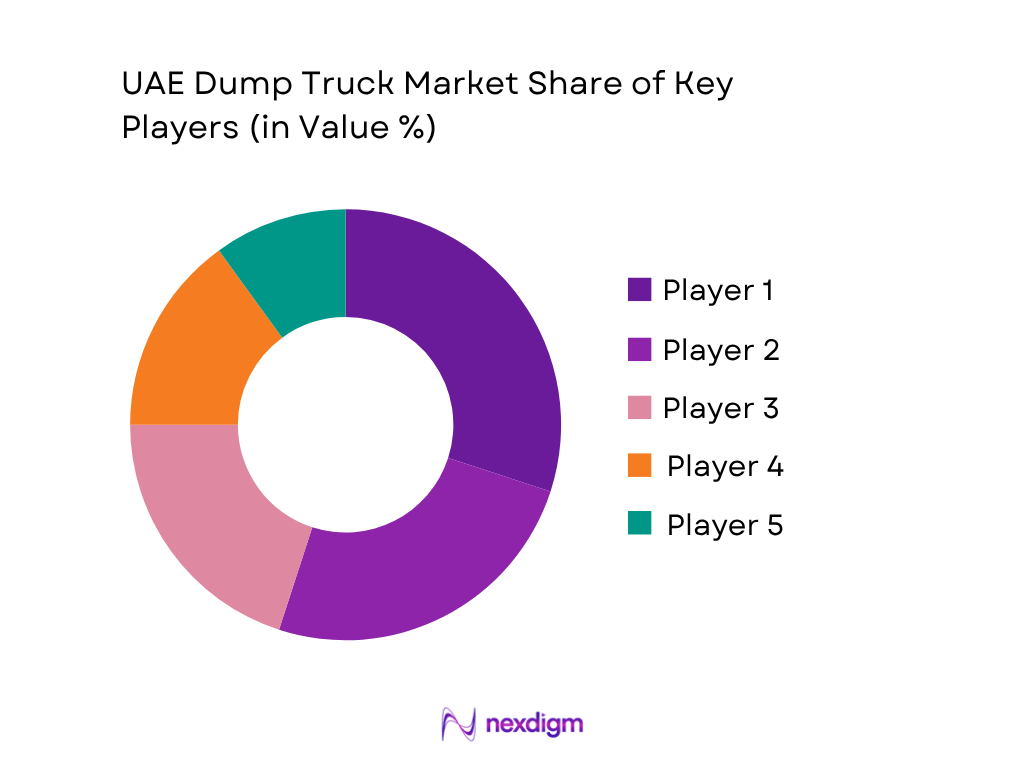
The UAE Dump Truck Market is characterized by competition between European heavy commercial vehicle manufacturers, Japanese truck brands and global off-highway equipment suppliers. Volvo Trucks, Mercedes-Benz Trucks, Scania, MAN and Renault Trucks address severe-duty road and construction applications, while Caterpillar, Komatsu, Volvo Construction Equipment, Bell Equipment and other construction-equipment manufacturers compete in specialized off-highway haulage. Competitive differentiation centers on payload capability, axle configurations, desert-duty cooling, drivetrain durability, dealer support, spare-parts availability and fleet telematics.
| Major Player | Establishment Year | Headquarters | Core UAE Dump Truck Focus | Payload / GVW Breadth | Construction Capability | Quarry Capability | Desert-Duty Suitability | Fleet Technology |
| Volvo Trucks | 1928 | ~ | ~ | ~ | ~ | ~ | ~ | ~ |
| Mercedes-Benz Trucks | 1896 | ~ | ~ | ~ | ~ | ~ | ~ | ~ |
| Scania AB | 1891 | ~ | ~ | ~ | ~ | ~ | ~ | ~ |
| Caterpillar Inc. | 1925 | ~ | ~ | ~ | ~ | ~ | ~ | ~ |
| Komatsu Ltd. | 1921 | ~ | ~ | ~ | ~ | ~ | ~ | ~ |
UAE Dump Truck Market Analysis
Growth Drivers
Large Construction Pipeline Supporting Sustained Heavy Tipper Utilization
Construction and infrastructure activity is a major demand driver for the UAE Dump Truck Market because excavation, grading, road formation, aggregate delivery, demolition and site preparation require continuous movement of dense materials. Dubai Municipality recorded 30,000 building-permit applications in the first half of 2024, compared with 23,000 applications in the corresponding 2023 period, while completed building transactions reached 5,500, compared with 4,000. Dubai’s Roads and Transport Authority reported the road network reaching 18,990 lane-kilometres in 2024, alongside 152 bridges and tunnels for vehicles and 2,613 km of cycling tracks. Abu Dhabi’s construction ecosystem also remained substantial, with the emirate recording 30,415 real-estate transactions in 2024. These workloads create recurring requirements for 6×4 and 8×4 rear tippers, rock-body trucks and construction dump trucks carrying excavated soil, crushed aggregate, fill and demolition material. The UAE’s 2024 GDP reached USD 552.32 billion, while GDP per capita reached USD 50,273.5, providing a strong macroeconomic foundation for capital-intensive infrastructure and real-estate activity. Continued project execution therefore supports demand for high-payload trucks, automated transmissions, heavy-duty axles, hydraulic hoists and fleet-management systems optimized for intensive construction cycles.
Quarry, Aggregate and Industrial Material Movement Supporting Severe-Duty Dump Trucks
The UAE Dump Truck Market benefits from a large quarrying, aggregate and industrial-material ecosystem concentrated particularly in Ras Al Khaimah, Fujairah and the Northern Emirates. Fujairah Natural Resources Corporation oversees quarrying and mineral-resource activities across an emirate covering approximately 1,450 square kilometres, while Ras Al Khaimah’s industrial base includes major limestone, rock, cement and construction-material operations requiring repeated quarry-to-crusher and quarry-to-project movements. Heavy trucks operating on public roads are permitted gross weights reaching 21 tonnes for two axles, 34 tonnes for three axles, 45 tonnes for four axles, 56 tonnes for five axles and 65 tonnes for six axles, establishing a regulatory framework for high-capacity aggregate transportation. Dubai’s logistics system adds another demand layer: Jebel Ali Port handled 15.5 million TEUs in 2024, while DP World’s UAE operations handled 15.5 million TEUs, supporting industrial construction and material-handling activity around ports, logistics parks and free zones. The UAE economy generated USD 552.32 billion of GDP in 2024, with GDP per capita of USD 50,273.5. This combination supports demand for quarry tippers, articulated dump trucks, abrasion-resistant bodies and severe-duty drivetrains designed for rock, limestone and aggregate movement.
Market Challenges
Heavy-Vehicle Weight and Axle Regulations Constraining Payload Optimization
Payload regulation represents a market-specific operational challenge for the UAE Dump Truck Market because contractors and aggregate operators must maximize material moved per trip while complying with federal gross-weight and axle-load limits. The national framework sets maximum gross weights at 21 tonnes for two-axle vehicles, 34 tonnes for three-axle vehicles, 45 tonnes for four-axle vehicles, 56 tonnes for five-axle vehicles and 65 tonnes for six-axle vehicles. Enforcement infrastructure includes 24 smart electronic gates planned for monitoring heavy vehicles across federal roads, making legal payload distribution increasingly important for fleet operations. These limits affect chassis selection, axle configuration, body volume, tare weight and the amount of dense rock or aggregate that can legally be transported. A high-volume body does not necessarily increase productive payload when carrying limestone or crushed rock because weight limits can be reached before volumetric capacity is utilized. Manufacturers and body builders therefore need stronger lightweight bodies, optimized wheelbases and appropriate axle ratings without sacrificing severe-duty durability. The UAE’s 2024 GDP of USD 552.32 billion and USD 50,273.5 GDP per capita support high construction intensity, but the regulatory environment requires fleets to translate that workload into compliant vehicle configurations rather than simply increasing payload per trip.
Extreme Heat, Dust and Intensive Duty Cycles Increasing Technical Requirements
The UAE’s operating environment creates a substantial technical challenge for dump trucks because construction and quarry fleets routinely combine high ambient temperatures, airborne dust, abrasive material, repeated tipping cycles and heavy axle loads. The country covers approximately 83,600 square kilometres, with extensive desert terrain and major construction activity concentrated around urban and industrial corridors. Dubai alone maintained 18,990 lane-kilometres of roads in 2024, while the emirate’s vehicle population reached 2.5 million registered vehicles, increasing interaction between heavy construction fleets and dense road traffic. Dump trucks operating between quarries and construction sites consequently require robust cooling systems, high-capacity air filtration, durable braking systems, reinforced suspension and reliable hydraulic tipping equipment. Quarry vehicles face additional stress from unpaved haul roads, rock loading, steep gradients and repeated stop-start cycles. Heat also places higher thermal loads on engines, transmissions, tires, lubricants and electrical systems, making preventive maintenance and parts availability important fleet-selection factors. The UAE generated USD 552.32 billion in GDP during 2024, with GDP per capita at USD 50,273.5, supporting intensive infrastructure activity, but maintaining equipment uptime under these operating conditions requires desert-duty engineering, mobile service capability and application-specific maintenance programs.
Market Opportunities
High-Payload Multi-Axle Tippers and Connected Fleet Systems Creating Expansion Potential
The UAE Dump Truck Market has a future growth opportunity in high-productivity multi-axle vehicles and connected fleet technologies as contractors seek to move greater material volumes while remaining within federal weight requirements. Current regulations allow gross weights of 45 tonnes for four-axle vehicles, 56 tonnes for five-axle vehicles and 65 tonnes for six-axle vehicles, creating a clear operating case for optimized 8×4 and other multi-axle heavy tipper configurations. The installation framework for 24 smart electronic heavy-vehicle monitoring gates also strengthens the need for onboard weighing, axle-load monitoring and digital compliance tools. Dubai’s construction and transport ecosystem provides an addressable fleet base: its road network reached 18,990 lane-kilometres in 2024, while registered vehicles reached 2.5 million. Contractors operating large fleets can increasingly use telematics, geofencing, payload monitoring, driver-behaviour analytics, tire-pressure monitoring and remote diagnostics to improve truck utilization and reduce unscheduled downtime. The UAE’s 2024 GDP stood at USD 552.32 billion, with GDP per capita at USD 50,273.5, providing a strong economic base for technology-intensive fleet investment. Future competitive advantage can therefore emerge from combining legally optimized payload configurations with connected fleet platforms, predictive maintenance, digital service records and mobile technical support.
Jebel Ali Trading Ecosystem Creating Used Equipment, Refurbishment and Re-Export Opportunities
The UAE’s position as a regional logistics and re-export hub creates a future opportunity for dump-truck distributors, used-equipment dealers, body builders and refurbishment companies serving GCC, African and Asian destinations. Jebel Ali Port handled 15.5 million TEUs in 2024, while DP World’s Dubai automotive terminals handled a record 1.3 million vehicles during the same period. Jebel Ali alone handled nearly 960,000 vehicles and Ro-Ro units, demonstrating the scale of vehicle logistics infrastructure available for commercial-equipment trade. Jebel Ali Free Zone hosts more than 930 automotive and spare-parts companies, providing an established ecosystem for importation, storage, parts supply, modification and onward distribution. This infrastructure can support used construction tippers and off-highway equipment through inspection, engine and transmission rebuilding, hydraulic refurbishment, replacement dump bodies and GCC-specification conversion before re-export. Dubai also had 2.5 million registered vehicles in 2024, reinforcing the depth of the local automotive service ecosystem. At the macroeconomic level, the UAE generated USD 552.32 billion in GDP during 2024, with GDP per capita of USD 50,273.5. These current capabilities create scope for the UAE to expand as a regional lifecycle hub for new, used and remanufactured dump-truck equipment.
Future Outlook
The UAE Dump Truck Market is forecast to expand at approximately ~X.X% CAGR during 2026–2035, supported by construction activity, transport infrastructure, quarry operations, industrial development and fleet replacement. Future demand will increasingly favor vehicles combining higher legal payloads with stronger fuel efficiency, automated transmissions, connected fleet management and severe-climate reliability. Off-highway applications will create additional opportunities for articulated haulers, while electrification and low-emission technologies will gradually influence construction fleet procurement.
The regulatory environment will increasingly influence truck configuration. UAE federal heavy-vehicle rules specify maximum gross weights of 21 tonnes for two-axle vehicles, 34 tonnes for three-axle vehicles, 45 tonnes for four-axle vehicles, 56 tonnes for five-axle vehicles and 65 tonnes for six-axle vehicles. These limits make payload engineering, axle distribution, chassis tare weight and dump-body design increasingly important to fleet productivity. Manufacturers capable of providing application-specific configurations can therefore target contractors seeking maximum legal payload without compromising durability.
Major Players
- Volvo Trucks – FMX Construction Tippers / Heavy-Duty 6×4 and 8×4 Applications
- Renault Trucks – K Range Heavy Construction Tippers / 6×4, 8×4 and All-Wheel-Drive Applications
- Scania AB – Heavy Construction Tippers / Quarry and Severe-Duty Truck Applications
- MAN Truck & Bus SE – TGS Construction Trucks / Heavy-Duty Tipper Applications
- Mercedes-Benz Trucks – Arocs Construction and Heavy-Duty Tipper Platforms
- IVECO S.p.A. – T-Way Heavy Construction and Off-Road Truck Platforms
- Isuzu Motors Limited – Heavy Commercial Chassis / Municipal and Construction Tipper Applications
- Hino Motors, Ltd. – 500 and 700 Series Heavy Commercial and Tipper Applications
- UD Trucks Corporation – Quester Heavy-Duty Construction and Tipper Applications
- Caterpillar Inc. – Off-Highway Trucks / Quarry and Heavy Construction Haulers
- Komatsu Ltd. – Rigid Off-Highway Dump Trucks / Quarry and Mining Haulage
- Volvo Construction Equipment – Articulated Dump Trucks / Quarry and Infrastructure Haulage
- Bell Equipment – Articulated Dump Trucks / Quarry and Earthmoving Applications
- SANY Heavy Industry Co., Ltd. – Off-Highway and Wide-Body Dump Trucks / Quarry Applications
- XCMG Group – Mining Dump Trucks / Wide-Body Haulers / Heavy Construction Applications
Key Target Audience
- Dump Truck and Heavy Commercial Vehicle Manufacturers
- Construction and Off-Highway Equipment Manufacturers
- Infrastructure and Heavy Civil Contractors
- Quarry, Aggregate and Building Material Operators
- Heavy Truck Distributors, Dealers and Body Builders
- Fleet Operators, Equipment Rental and Leasing Companies
- Investments and Venture Capitalist Firms
- Government and Regulatory Bodies (Ministry of Energy and Infrastructure, Ministry of Industry and Advanced Technology, Roads and Transport Authority Dubai, Integrated Transport Centre Abu Dhabi, Federal Authority for Identity Citizenship Customs and Port Security)
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves developing an ecosystem map covering UAE dump-truck OEMs, authorized distributors, body builders, construction contractors, quarry operators, rental companies and fleet owners. Core variables include GVW, payload, axle configuration, dump-body capacity, drivetrain type, application intensity, construction activity, quarry demand, fleet replacement and heavy-vehicle regulations.
Step 2: Market Analysis and Construction
Historical demand is constructed through bottom-up analysis of road-legal tippers, quarry trucks, articulated dump trucks and rigid off-highway haulers. Construction activity, infrastructure development, quarry applications and fleet requirements are mapped against vehicle configurations. The resulting market structure is reconciled with equipment availability, distributor networks, customer procurement patterns and replacement demand.
Step 3: Hypothesis Validation and Expert Consultation
Market hypotheses are validated through structured discussions and CATIs with heavy-truck distributors, construction contractors, quarry operators, fleet managers, body builders and equipment-service companies. These consultations assess payload preferences, axle requirements, operating cycles, replacement behaviour, severe-climate performance, maintenance requirements, rental utilization and purchasing criteria across major UAE applications.
Step 4: Research Synthesis and Final Output
The final phase triangulates primary findings with official construction, transport, economic and heavy-vehicle regulatory indicators. Bottom-up fleet and application estimates are reconciled with supply-side vehicle portfolios and distributor capabilities. The process produces the final UAE Dump Truck Market sizing framework, segmentation, competitive assessment, technology outlook and strategic opportunity analysis.

- Executive Summary
- Research Methodology (Market Definition and Scope, UAE Dump Truck and Tipper Taxonomy, On-Road Tipper and Off-Highway Dump Truck Classification, Rigid and Articulated Dump Truck Classification, GVW and Payload Capacity Mapping, Axle Configuration Assessment, Dump Body Configuration Assessment, Construction and Quarry Application Mapping, Heavy-Vehicle Fleet Assessment, New Dump Truck Sales Assessment, Fleet Replacement Assessment, Equipment Import and Re-Export Mapping, Distributor and Service Network Assessment, Market Sizing Framework)

- Definition and Scope
- UAE Dump Truck Industry Evolution and Heavy Construction Equipment Development
- Dump Truck Chassis Manufacturing, Body-Upfitting and Assembly Process
- Dump Truck Value Chain Analysis
- UAE Dump Truck Supply Chain Analysis
- Engine, Transmission, Axle, Suspension, Hydraulic Hoist and Dump Body Ecosystem Analysis
- UAE Dump Truck Import, Body-Building, Distribution and Re-Export Footprint Assessment
- OEM, Authorized Distributor, Construction Contractor, Quarry Operator and Aftermarket Framework

- Growth Drivers (Major Infrastructure and Urban Development Projects, Quarry and Aggregate Transportation, Road and Transport Infrastructure Expansion, Industrial and Logistics Zone Development, Construction Fleet Replacement, Growth of Heavy Civil Projects, Port and Free-Zone Development, Contractor Demand for Higher-Payload Tippers)
- Market Challenges (Federal Heavy-Vehicle Weight Restrictions, Axle Load Compliance, Extreme Heat and Dust Operating Conditions, Tire and Drivetrain Wear, Dependence on Imported Trucks and Spare Parts, Construction Cycle Volatility, Used-Truck Competition, Fleet Financing and Residual Value Risk)
- Market Opportunities (High-Payload Road-Legal Tippers, Articulated Dump Trucks for Quarry Applications, Electric and Low-Emission Construction Trucks, Connected Fleet Telematics, Onboard Payload Monitoring, High-Strength Lightweight Dump Bodies, Used Equipment Refurbishment, UAE-to-GCC and Africa Heavy Equipment Re-Exports)
- Market Trends (6×4 and 8×4 Tipper Adoption, Automated Manual Transmission Growth, High-Torque Construction Drivetrains, Payload Optimization, Connected Truck Monitoring, Driver-Assistance Systems, Fleet Electrification, Predictive Maintenance, Specialized Body-Upfitting)
- Regulatory and Standards Landscape (Ministry of Energy and Infrastructure Heavy-Vehicle Weight Regulations, Federal Heavy-Vehicle Axle Load Limits, 65-Ton Maximum Road Weight Framework, Smart Electronic Weight Monitoring Gates, Roadworthiness and Vehicle Inspection Requirements, Dubai RTA Commercial Vehicle Requirements, Abu Dhabi Heavy Vehicle Requirements, Special Load Permit Framework)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Competition Ecosystem

- By Market Value (2020-2025)
- By New Dump Truck and Tipper Unit Sales (2020-2025)
- By On-Road Tipper Unit Sales (2020-2025)
- By Off-Highway Dump Truck Unit Sales (2020-2025)
- By Articulated Dump Truck Unit Sales (2020-2025)
- By Rigid Dump Truck Unit Sales (2020-2025)

- By Dump Truck Type (In Value %)
On-Road Rear Tippers
Construction Tippers
Rock Body Tippers
Box Body Tippers
Quarry Tippers
Articulated Dump Trucks
Rigid Off-Highway Dump Trucks
Heavy Mining Haul Trucks
Wide-Body Dump Trucks
Specialized Dump Trucks - By GVW and Payload Capacity (In Value %)
Below 21 Ton GVW
21–34 Ton GVW
34–45 Ton GVW
45–56 Ton GVW
56–65 Ton GVW
Below 25 Ton Payload
25–40 Ton Payload
40–60 Ton Payload
60–100 Ton Payload
Above 100 Ton Payload - By Application Type (In Value %)
Road and Highway Construction
Urban Infrastructure Development
Residential and Commercial Construction
Industrial and Logistics Park Construction
Quarrying and Aggregate Haulage
Limestone and Rock Transportation
Earthmoving and Site Preparation
Port and Free-Zone Development
Oil and Gas Site Development
Utilities and Pipeline Construction
Demolition and Construction Waste
Municipal and Public Works
Land Reclamation and Coastal Projects
Heavy Civil Construction - By Powertrain Type (In Value %)
Diesel Internal Combustion Dump Trucks
Diesel Automated Manual Dump Trucks
Diesel Automatic Dump Trucks
Diesel-Electric Off-Highway Haulers
Battery Electric Dump Trucks
Battery Electric Off-Highway Haulers
Hybrid and Electrified Haulage Systems
Alternative-Fuel Heavy Tippers - By Sales Channel (In Value %)
OEM and Principal Direct Sales
Authorized Heavy Truck Distributors
Construction Equipment Dealers
Fleet Direct Procurement
Quarry Operator Procurement
Infrastructure Contractor Procurement
Rental and Leasing Companies
Used Heavy Truck Dealers
Heavy Equipment Auction Channels
Free-Zone Importers and Re-Exporters - By Emirate (In Value %)
Dubai
Abu Dhabi
Sharjah
Ajman
Ras Al Khaimah
Fujairah
Umm Al Quwain

- Market Share of Major Players (By Revenue, Unit Sales, Dump Truck Type, Payload Class, Construction Application, Quarry Application, Sales Channel, Emirate)
- Cross Comparison Parameters (On-Road Tipper and Off-Highway Dump Truck Portfolio Breadth, 21-65 Ton Road GVW and Off-Highway Payload Coverage, 6×4-6×6-8×4-8×8 Axle and Traction Capability, Construction Quarry Aggregate and Heavy-Civil Application Coverage, High-Ambient-Temperature Cooling and Desert-Duty Reliability, UAE Authorized Distributor Parts Workshop and Mobile-Service Network Strength, Telematics Payload Monitoring Driver-Safety and Fleet-Uptime Capability, Dubai-Jebel Ali Used Equipment and GCC-Africa Re-Export Readiness)
- SWOT Analysis of Major Players
- Competitive Positioning Matrix
- Pricing and Distribution Network Benchmarking
- Detailed Profiles of Major Companies
Volvo Trucks – FMX Construction Tippers / Heavy-Duty 6×4 and 8×4 Applications
Renault Trucks – K Range Heavy Construction Tippers / 6×4, 8×4 and All-Wheel-Drive Applications
Scania AB – Heavy Construction Tippers / Quarry and Severe-Duty Truck Applications
MAN Truck & Bus SE – TGS Construction Trucks / Heavy-Duty Tipper Applications
Mercedes-Benz Trucks – Arocs Construction and Heavy-Duty Tipper Platforms
IVECO S.p.A. – T-Way Heavy Construction and Off-Road Truck Platforms
Isuzu Motors Limited – Heavy Commercial Chassis / Municipal and Construction Tipper Applications
Hino Motors, Ltd. – 500 and 700 Series Heavy Commercial and Tipper Applications
UD Trucks Corporation – Quester Heavy-Duty Construction and Tipper Applications
Caterpillar Inc. – Off-Highway Trucks / Quarry and Heavy Construction Haulers
Komatsu Ltd. – Rigid Off-Highway Dump Trucks / Quarry and Mining Haulage
Volvo Construction Equipment – Articulated Dump Trucks / Quarry and Infrastructure Haulage
Bell Equipment – Articulated Dump Trucks / Quarry and Earthmoving Applications
SANY Heavy Industry Co., Ltd. – Off-Highway and Wide-Body Dump Trucks / Quarry and Heavy Construction Applications
XCMG Group – Mining Dump Trucks / Wide-Body Haulers / Heavy Construction Applications

- Dump Truck Fleet Buyer Segmentation
- Construction Contractor and Quarry Operator Procurement Behaviour
- Dump Truck OEM and Distributor Selection Criteria
- Fleet Buyer and Operator Pain Points
- GVW, Payload and Powertrain Adoption Assessment
- Replacement, Rental and Repurchase Behaviour

- By Market Value (2026-2035)
- By New Dump Truck and Tipper Unit Sales (2026-2035)
- By On-Road Tipper Unit Sales (2026-2035)
- By Off-Highway Dump Truck Unit Sales (2026-2035)
- By Articulated Dump Truck Unit Sales (2026-2035)
- By Rigid Dump Truck Unit Sales (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
