
 Download PDF
Market Overview
The UAE Exterior Wall Systems Market is supported by sustained construction activity, high-rise development, commercial real estate investment, hospitality projects and demand for technically advanced building envelopes. The latest two reported periods show UAE GDP increasing from USD 522.62 billion to USD 552.32 billion, while construction activity expanded strongly. Dubai provides particularly visible evidence of the project pipeline: buildings under construction increased from 15,722 to 18,114, with multi-story buildings accounting for 1,024 projects in the latest period. These developments require curtain walls, glazing, cladding and other facade systems. DataBank
Dubai and Abu Dhabi represent the principal demand centres for UAE exterior wall systems because of their concentration of high-rise residential buildings, commercial towers, hospitality assets, mixed-use developments, government projects and major infrastructure. Dubai’s building pipeline is particularly extensive, with 18,114 buildings under construction in the latest reported period, including 1,024 multi-story buildings and 969 public buildings. Dubai’s real-estate transaction value also reached AED 761.11 billion, providing evidence of the scale of underlying property activity. Abu Dhabi complements this demand through government-led infrastructure, commercial development, cultural projects and large-scale urban expansion.
Market Segmentation
By System Type
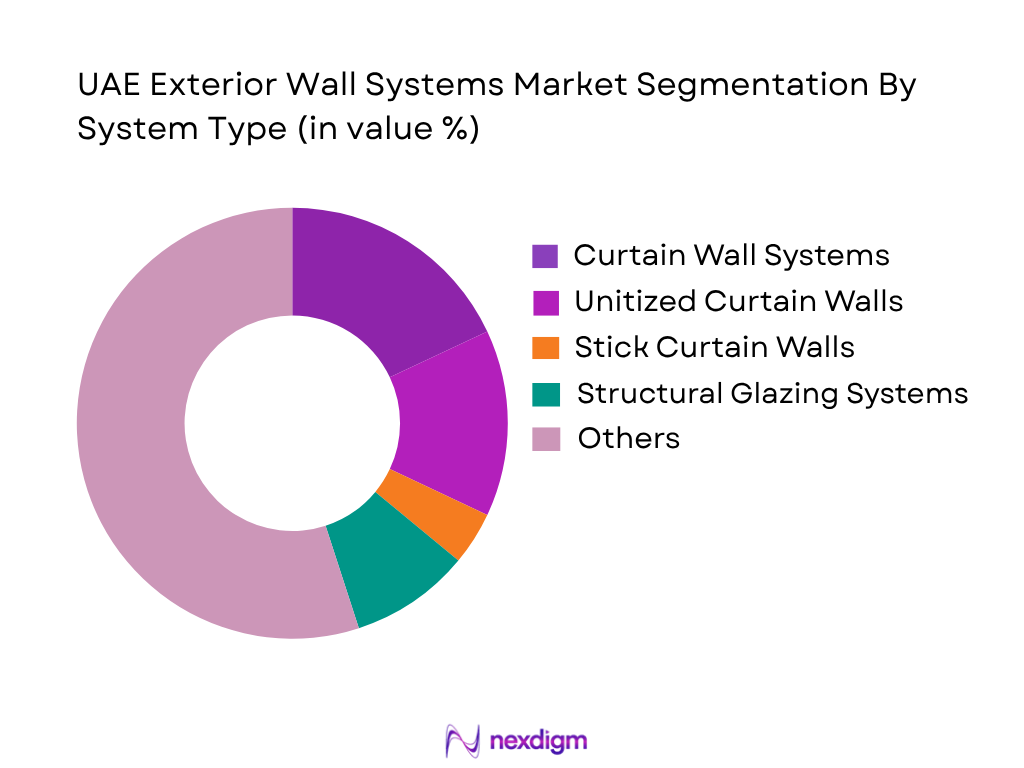
The UAE Exterior Wall Systems Market is segmented by system type into curtain wall systems, unitized curtain walls, stick curtain walls, structural glazing systems, semi-unitized facade systems, aluminium cladding systems, aluminium composite panel cladding, metal cladding systems, stone cladding systems, rainscreen and ventilated facade systems, insulated exterior wall systems, and precast and GRC exterior wall systems. Curtain wall systems represent the dominant segment within the report framework because they are extensively specified for high-rise residential, commercial, hospitality and mixed-use buildings. Their suitability for large glazed elevations, architectural flexibility, lightweight construction and integration with aluminium framing makes them particularly relevant to UAE developments. Unitized systems are especially suitable for high-rise projects because factory fabrication can support installation efficiency and consistency. Structural glazing and high-performance glass systems complement curtain walls where developers prioritize architectural appearance, daylighting and solar control. Aluminium cladding and composite panels remain important for opaque sections, podiums and architectural detailing, while rainscreen and insulated systems are gaining relevance as developers place greater emphasis on heat management and building-envelope performance. The UAE’s large pipeline of high-rise and multi-story construction therefore supports sustained demand across both glazed and opaque facade assemblies.
By Application
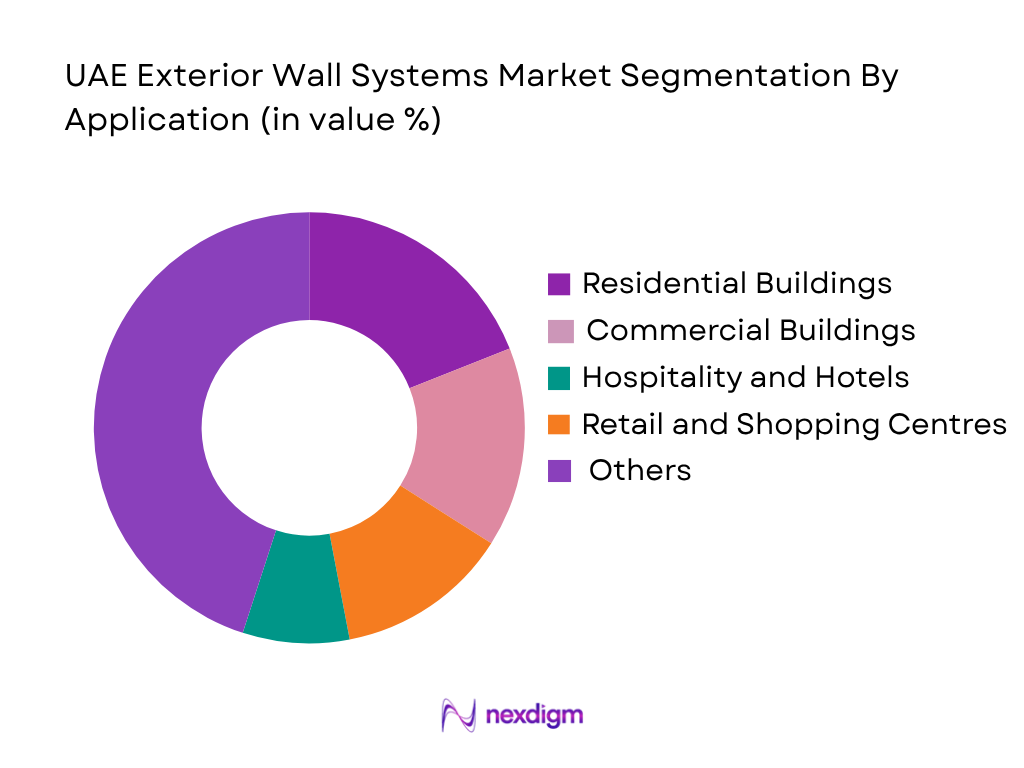
The UAE Exterior Wall Systems Market is segmented by application into residential buildings, commercial buildings, hospitality and hotels, retail and shopping centres, office buildings, healthcare facilities, educational buildings, industrial and logistics buildings, airports and transportation infrastructure, government and institutional buildings, mixed-use developments and data centres. Commercial buildings represent the leading application within the report framework because UAE business districts and mixed-use developments require extensive glazed facades, aluminium systems, curtain walls and architectural cladding. Dubai’s building pipeline included 1,024 multi-story buildings under construction, supporting recurring facade requirements across towers and commercial assets. Hospitality is another important application because the UAE recorded more than 30 million hotel guests in 2024 and more than 105 million occupied hotel nights, creating an expanding base of hotels and tourism-oriented developments. Residential high-rise construction also generates substantial demand for curtain walls, balconies, glazing and cladding, particularly in Dubai. Airports, healthcare facilities, public buildings and data centres create additional requirements for high-performance and specialized envelope systems. The breadth of applications reduces dependence on a single construction segment and supports demand for both standardized and customized facade solutions.
Competitive Landscape
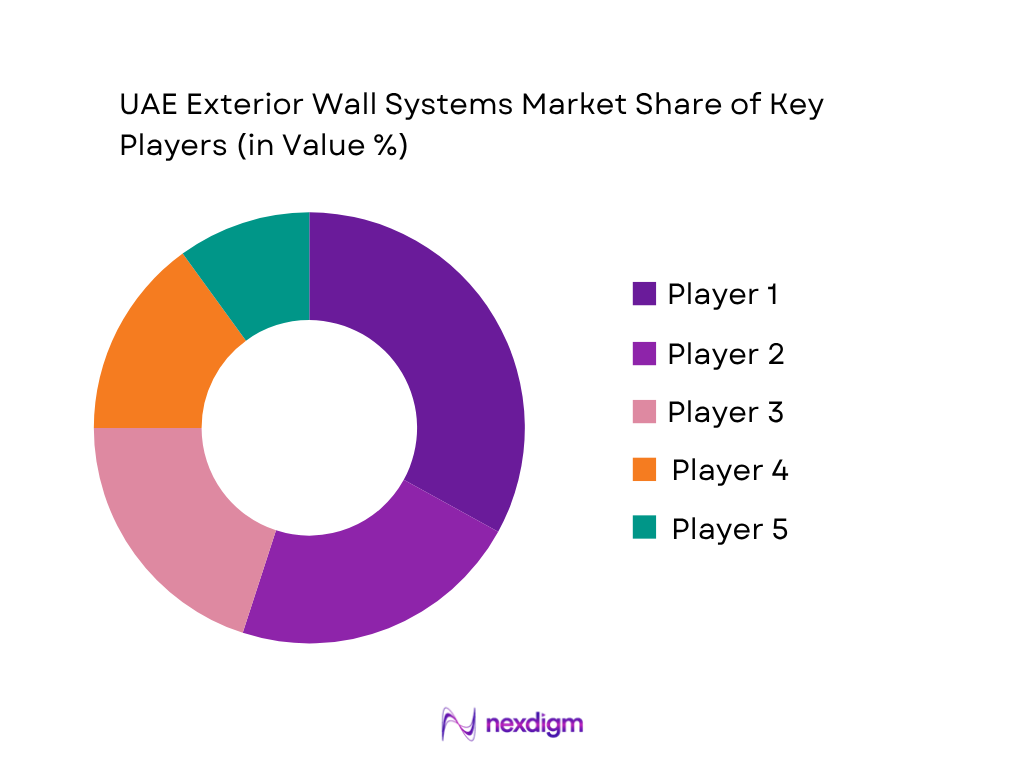
The UAE Exterior Wall Systems Market includes international facade-system providers, regional facade contractors, aluminium and glass processors, and specialized building-envelope manufacturers. Competition is influenced by high-rise project experience, engineering capabilities, manufacturing capacity, architectural-glass processing, aluminium fabrication, installation resources and the ability to meet UAE building and fire-safety requirements. Dubai and Abu Dhabi’s large development pipelines favour companies capable of handling complex facade packages and coordinating with developers, architects, consultants and main contractors.
| Company | Establishment Year | Headquarters | Core Facade Capability | High-Rise Experience | Manufacturing/Fabrication | Glass Capability | Aluminium Capability | Project Execution |
| Al Abbar Group | 1969 | Dubai, UAE | ~ | ~ | ~ | ~ | ~ | ~ |
| Emirates Glass | 1997 | Dubai, UAE | ~ | ~ | ~ | ~ | ~ | ~ |
| Alico Aluminium & Light Industries | 1976 | Dubai, UAE | ~ | ~ | ~ | ~ | ~ | ~ |
| Emirates Building Systems | 1997 | Dubai, UAE | ~ | ~ | ~ | ~ | ~ | ~ |
| Permasteelisa Gartner Middle East | 1980 | Dubai, UAE | ~ | ~ | ~ | ~ | ~ | ~ |
UAE Exterior Wall Systems Market Analysis
Growth Drivers
Construction and Urban Infrastructure Expansion
The UAE Exterior Wall Systems Market is supported by sustained expansion in construction and urban infrastructure, particularly across Dubai and Abu Dhabi. The UAE’s real GDP reached AED 1.776 trillion in 2024, while construction and building activities recorded 8.4 growth, making construction one of the country’s fastest-expanding economic activities. The sector also contributed AED 158.3 billion to the national economy when applying the reported 8.9 construction contribution to total GDP. FedComp & Stats Centre Dubai provides a particularly strong demand base for facade systems. Dubai Municipality recorded 18,114 buildings under construction at the end of 2024, compared with 15,722 in the preceding period. The pipeline included 9,297 private villas, 6,277 investment villas, 1,024 multi-story buildings, 969 public buildings and 547 industrial buildings, creating requirements for curtain walls, aluminium cladding, glazing, insulation and architectural facade assemblies. DSC The UAE’s construction expansion is therefore directly relevant to exterior wall-system demand because each new residential, commercial, hospitality, institutional and industrial development requires an engineered building envelope. Continued urban development, redevelopment and infrastructure investment provide recurring opportunities for facade contractors, system suppliers, glass processors and aluminium fabricators.
Growth of Real Estate, Hospitality and High-Rise Development
Expansion of real estate, hospitality and high-rise development is strengthening demand for technically advanced exterior wall systems across the UAE. National real GDP increased to AED 1.776 trillion in 2024, while real estate activities expanded by 4.8 and accommodation and food-service activities grew by 5.7. The same period recorded 147.8 million airport passengers, demonstrating the scale of international mobility supporting hospitality, tourism and commercial development. Ministry of Education Dubai remains particularly significant because its development model is concentrated around high-density residential towers, hotels, retail destinations, offices and mixed-use communities. Dubai Municipality reported 1,024 multi-story buildings under construction in 2024, alongside 15,574 villa projects, covering both private and investment villas. DSC These building categories require different facade specifications, ranging from unitized curtain walls and solar-control glazing for towers to insulated cladding, architectural aluminium and weather-resistant envelope systems for villas. Hospitality activity also creates recurring requirements for visually differentiated facades, high-performance glazing and durable exterior finishes. Hotel guests across the UAE reached approximately 15.3 million during the first half of 2024, while hotel revenues exceeded AED 24.6 billion, supporting continued investment in accommodation infrastructure. Ministry of Education
Market Challenges
High Climatic Performance and Building-Envelope Requirements
The UAE Exterior Wall Systems Market faces demanding climatic requirements because facade assemblies must operate under intense heat, solar exposure, dust and substantial temperature variation while maintaining occupant comfort and building performance. The challenge is particularly relevant to curtain walls, glazing, aluminium cladding, insulation and sealant systems, where thermal performance, air infiltration, water penetration and ultraviolet resistance directly affect building-envelope performance. The UAE economy recorded AED 1.776 trillion in real GDP in 2024, with construction growing by 8.4, indicating a large and active building environment in which performance requirements apply across numerous new developments. FedComp & Stats Centre Dubai Municipality reported 18,114 buildings under construction in 2024, including 1,024 multi-story buildings, meaning facade contractors must repeatedly deliver systems suitable for high-rise and technically complex structures. DSC Exterior wall systems therefore require careful specification of glass coatings, thermal breaks, insulation, framing systems and weather seals rather than focusing only on architectural appearance. Higher-performance assemblies can also require more sophisticated engineering, testing and installation procedures. The combination of climatic exposure and increasingly complex building designs creates technical requirements across design, procurement, fabrication and installation, raising the importance of engineering quality, material compatibility and long-term facade durability.
Dependence on Construction Cycles, Imported Components and Project Execution
The UAE Exterior Wall Systems Market is exposed to construction-cycle fluctuations, project scheduling risks and dependence on globally sourced materials and components. Although the national construction sector expanded by 8.4 in 2024, the wider UAE economy remains influenced by changes in investment activity, global trade, interest rates and real-estate development conditions. The Central Bank of the UAE reported real GDP growth of 3.9 for 2024 and projected continued expansion supported by non-hydrocarbon activities, while identifying construction and real estate as important contributors to domestic growth. Central Bank of the UAE Exterior wall-system projects also involve multiple interconnected stages, including architectural design, structural engineering, procurement, glass processing, aluminium fabrication, panel manufacturing, logistics, installation and testing. Delays in any stage can affect facade completion and building handover. Dubai’s 18,114 buildings under construction demonstrate the scale of projects requiring coordinated execution across contractors and suppliers. DSC Imported glass, aluminium systems, hardware, sealants and specialized facade components can further expose contractors to international supply-chain disruptions and longer procurement cycles. These factors make production planning, local fabrication capability, inventory management and supplier diversification important operational considerations for UAE facade-system participants.
Market Opportunities
Expansion of High-Performance and Energy-Efficient Facade Systems
The UAE Exterior Wall Systems Market has an opportunity to expand through high-performance facade systems designed to improve thermal efficiency, solar control and building-envelope performance. The opportunity is supported by the scale of construction activity and the increasing technical requirements of modern buildings. UAE real GDP reached AED 1.776 trillion in 2024, while construction expanded by 8.4, confirming continued development activity across residential, commercial, hospitality and infrastructure projects. Ministry of Education Dubai alone had 18,114 buildings under construction, including 1,024 multi-story buildings, providing a substantial project base for advanced curtain walls, insulated aluminium systems, solar-control glazing, high-performance glass and thermally improved facade assemblies. DSC High-performance systems can address the specific requirements of the UAE’s hot climate by reducing unwanted solar heat gain while maintaining daylight and architectural transparency. This creates opportunities for suppliers offering low-emissivity glazing, spectrally selective glass, thermal-break aluminium frames, insulated cladding and integrated facade solutions. Commercial towers, hotels, healthcare buildings and premium residential developments can particularly support sophisticated envelope specifications. The combination of continued construction activity and technically demanding building designs provides an opportunity for manufacturers and facade contractors to differentiate through energy performance, durability, engineering capability and compliance with project-specific envelope requirements.
Facade Modernization, Hospitality Development and Advanced Architectural Systems
Facade modernization and continued hospitality development create opportunities for suppliers of architectural glazing, aluminium cladding, curtain walls, rainscreen systems and customized exterior-envelope solutions. UAE accommodation and food-service activities grew by 5.7 in 2024, while the country recorded approximately 15.3 million hotel guests during the first half of the year. Hotel revenues exceeded AED 24.6 billion during the same period, demonstrating significant activity within the hospitality ecosystem. Ministry of Education Real estate activities also expanded by 4.8, supporting continued development and refurbishment requirements across commercial and residential assets. Ministry of Education Dubai’s construction pipeline adds further opportunity, with 18,114 buildings under construction and 547 industrial buildings recorded by Dubai Municipality. DSC Beyond new construction, existing hotels, offices, retail properties and residential buildings can require facade refurbishment to improve thermal performance, weather resistance, architectural appearance and asset value. This supports demand for replacement glazing, facade recladding, aluminium renovation systems and upgraded building-envelope components. Developers and asset owners can also use distinctive facade designs to differentiate properties in competitive real-estate and hospitality environments. Consequently, opportunities extend beyond new-build construction into renovation, modernization and performance upgrades across the UAE’s growing building stock.
Future Outlook
The UAE Exterior Wall Systems Market is expected to continue developing alongside high-rise residential construction, commercial real estate, hospitality expansion and infrastructure investment. The project pipeline provides a foundation for continued requirements for curtain walls, glazing, aluminium cladding and specialized building-envelope systems. Dubai’s 18,114 buildings under construction demonstrate the scale of ongoing development, while UAE construction activity expanded by 8.4 in the latest reported period. Future demand is also likely to emphasize thermal performance, solar control, durability, fire performance and sustainable facade materials as developers increasingly integrate building-envelope performance into project specifications. DSC
Major Players
- Al Abbar Group
- Emirates Glass LLC
- ALICO Aluminium & Light Industries Co.
- Emirates Building Systems
- Permasteelisa Gartner Middle East
- Alumco LLC
- Al Abrar Company
- Leskor Metal Industries LLC
- Alumital Glass & Aluminium Works LLC
- Madinat Al Saada Aluminium & Glass Works LLC
- Inventure Metal Products Industries LLC
- ESC Aluminium Systems
- Facade One International
- JML Architectural Facades
- Zafcon Facade Glass & Aluminium Installation LLC
Key Target Audience
- Real Estate Developers and Property Development Companies
- Facade Contractors and Building-Envelope Specialists
- Architectural and Engineering Procurement Teams
- Aluminium, Glass and Cladding Manufacturers
- Main Contractors and Specialist Subcontractors
- Investments and Venture Capitalist Firms
- Government and Regulatory Bodies (Dubai Municipality, Abu Dhabi Department of Municipalities and Transport, Ministry of Energy and Infrastructure)
- Building Material Distributors and Construction-System Suppliers
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves constructing a UAE Exterior Wall Systems ecosystem covering developers, architects, facade consultants, contractors, manufacturers, glass processors, aluminium fabricators and material suppliers. Key variables include facade installation area, building type, system type, material selection, project pipeline, high-rise construction and building-envelope specifications.
Step 2: Market Analysis and Construction
Historical construction and real-estate indicators are compiled to establish demand relationships between building activity and exterior wall-system requirements. The analysis evaluates residential, commercial, hospitality, infrastructure and mixed-use projects alongside curtain-wall, glazing, cladding and insulated-wall applications.
Step 3: Hypothesis Validation and Expert Consultation
Market hypotheses are validated through discussions with facade contractors, system manufacturers, developers, architects and building-material suppliers. Industry inputs are used to assess procurement practices, project specifications, system preferences, fabrication capacity, installation constraints and competitive positioning.
Step 4: Research Synthesis and Final Output
The final stage triangulates project-level, construction-sector and company-level information to establish the market framework. Bottom-up assessments of facade applications are reconciled with top-down construction indicators to produce a consistent market estimate, segmentation structure and forward-looking assessment.

- Executive Summary
- Research Methodology (Market Definitions and Assumptions, UAE Exterior Wall Systems Market Classification, Building-Envelope Scope, Facade System Mapping, Curtain Wall Assessment, Structural Glazing Assessment, Cladding System Assessment, Insulated Wall System Assessment, Exterior Insulation Assessment, Rainscreen Facade Assessment, Ventilated Facade Assessment, Aluminium Profile Assessment, Architectural Glass Assessment, ACP and Metal Composite Panel Assessment, Stone and Ceramic Cladding Assessment, Thermal Performance Assessment, Solar Control Assessment, Fire Performance Assessment, Wind-Load Assessment, Water-Tightness Assessment, Acoustic Performance Assessment, Supply-Side Assessment, Demand-Side Assessment, Top-Down Market Sizing, Bottom-Up Market Sizing, Primary Industry Interviews, Project Pipeline Assessment, Data Triangulation, Forecasting Framework)

- Definition and Scope
- UAE Building-Envelope Industry Evolution and Development of Curtain Wall Systems, Structural Glazing, Unitized Facades, Stick Curtain Walls, Aluminium Cladding, ACP Cladding, Stone Cladding, Glass Facades, Rainscreen Systems, Insulated Wall Systems, Ventilated Facades, High-Performance Glazing, Solar-Shading Facades, Prefabricated Facade Systems, Sustainable Exterior Wall Technologies
- Exterior Wall Systems Value Chain Analysis
- Exterior Wall Systems Supply Chain Analysis
- Aluminium Extrusion Suppliers, Architectural Glass Manufacturers, ACP Manufacturers, Insulation Material Suppliers, Sealant and Adhesive Suppliers, Steel and Structural Component Suppliers, Facade System Providers, Facade Engineering Companies, Facade Contractors, Fabrication Facilities, Installation Contractors, Main Contractors, Real Estate Developers, Architects, Consultants, Building Material Distributors, Building Testing and Certification Providers

- Growth Drivers (High-Rise Residential Development, Commercial Real Estate Construction, Hospitality and Tourism Development, Infrastructure Expansion, Mixed-Use Development, Premium Architectural Facade Demand, Climate-Responsive Building Design, Energy-Efficient Building Requirements, Urban Redevelopment, Luxury Real Estate Development)
- Market Challenges (High Installation Complexity, Skilled Facade Installer Requirements, Extreme Heat Exposure, Sand and Dust Accumulation, Solar Radiation Exposure, Imported Material Dependency, Project Execution Delays, Fire-Safety Compliance Requirements, Facade Maintenance Requirements, Material and Component Supply Constraints)
- Market Opportunities (High-Performance Curtain Walls, Energy-Efficient Glazing, Unitized Facade Adoption, Sustainable Cladding Systems, Building Retrofit and Facade Renovation, High-Rise Residential Development, Luxury Hospitality Projects, Data Centre Construction, Green Building Materials, Solar-Control Facades, Ventilated Facade Systems, Smart Facade Technologies)
- Market Trends (Unitized Curtain Wall Adoption, High-Performance Low-E Glass, Thermally Broken Aluminium Systems, Sustainable Cladding Materials, Rainscreen Facades, Integrated Solar Shading, Prefabricated Facade Components, Digital Facade Engineering, BIM-Based Facade Coordination, Smart Building Envelopes, Lightweight Cladding, High-Durability Coatings)
- Government Regulations and Standards (Dubai Building Code, Al Sa’fat Dubai Green Building System, Abu Dhabi Estidama Pearl Rating System, UAE National Green Building Regulation, UAE Energy-Efficiency Regulations, Dubai Facade Treatment Requirements, External Cladding Requirements, Fire and Life Safety Code, Thermal Insulation Requirements, Glazing and Solar-Control Requirements, Wind-Load Requirements, Building Permit and Facade Approval Requirements) Dubai Municipality
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Construction and Facade Project Ecosystem

- By Market Value (2020-2025)
- By Exterior Wall Systems Installation Area (2020-2025)
- By Curtain Wall Installation Area (2020-2025)
- By Cladding Installation Area (2020-2025)
- By Architectural Glass Installation Area (2020-2025)
- By Aluminium Facade Installation Volume (2020-2025)
- By Insulated Wall System Installation Area (2020-2025)
- By Residential Exterior Wall System Installation Area (2020-2025)
- By Commercial Exterior Wall System Installation Area (2020-2025)
- By Infrastructure Exterior Wall System Installation Area (2020-2025)
- By Average System Value per Square Meter (2020-2025)

- By System Type (In Value %)
Curtain Wall Systems
Unitized Curtain Walls
Stick Curtain Walls
Structural Glazing Systems
Semi-Unitized Facade Systems
Aluminium Cladding Systems
Aluminium Composite Panel Cladding
Metal Cladding Systems
Stone Cladding Systems
Rainscreen and Ventilated Facade Systems
Insulated Exterior Wall Systems
Precast and GRC Exterior Wall Systems - By Material Type (In Value %)
Aluminium
Architectural Glass
Aluminium Composite Panels
Steel
Stone
Ceramic and Terracotta
GRC and GFRC
Insulation Materials
Concrete and Precast Materials
Other Facade Materials - By Application (In Value %)
Residential Buildings
Commercial Buildings
Hospitality and Hotels
Retail and Shopping Centres
Office Buildings
Healthcare Facilities
Educational Buildings
Industrial and Logistics Buildings
Airports and Transportation Infrastructure
Government and Institutional Buildings
Mixed-Use Developments
Data Centres - By Building Height (In Value %)
Low-Rise Buildings
Mid-Rise Buildings
High-Rise Buildings
Super High-Rise Buildings
Skyscrapers - By Emirate (In Value %)
Dubai
Abu Dhabi
Sharjah
Ajman
Ras Al Khaimah
Fujairah
Umm Al Quwain

- Market Share of Major Players (By UAE Revenue, Facade Project Value, Curtain Wall Installation Capacity, Aluminium Fabrication Capacity, Architectural Glass Processing Capacity, Cladding Portfolio, Unitized Facade Capability, High-Rise Project Portfolio, Emirate-Wise Project Coverage, Green Building Capability, Facade Engineering Capability, Installation Capacity, Aftermarket and Maintenance Support)
- Cross Comparison Parameters (Curtain Wall System Portfolio Breadth, Unitized Facade Manufacturing Capability, Architectural Glass Processing Capability, Aluminium Fabrication Capacity, High-Performance Glazing Capability, Facade Engineering and Design Capability, High-Rise Project Execution Capability, Green Building and Energy-Efficiency Compliance)
- SWOT Analysis of Major Players
- Competitive Positioning Matrix
- Exterior Wall Systems Technology and Performance Benchmarking
- Major Companies
Al Abbar Group
Emirates Glass LLC
ALICO Aluminium & Light Industries Co.
Emirates Building Systems
Permasteelisa Gartner Middle East
Alumco LLC
Al Abrar Company
Leskor Metal Industries LLC
Alumital Glass & Aluminium Works LLC
Madinat Al Saada Aluminium & Glass Works LLC
Inventure Metal Products Industries LLC
ESC Aluminium Systems
Facade One International
JML Architectural Facades
Zafcon Facade Glass & Aluminium Installation LLC

- Real Estate Developer Facade Requirement Assessment
- Main Contractor Procurement Assessment
- Facade Contractor Project Requirement Analysis
- Architect and Design Specification Assessment
- Commercial Building Envelope Requirement Assessment
Residential High-Rise Facade Requirement Assessment - Hospitality Facade Requirement Assessment
- Infrastructure and Transportation Facade Assessment
- Industrial and Logistics Building Envelope Assessment
- Data Centre Facade Requirement Assessment
- Facade Performance Requirement Assessment (Thermal Insulation, U-Value, Solar Heat Gain, Air Permeability, Water Tightness, Wind Resistance, Fire Performance, Acoustic Performance, Structural Load Resistance, Durability)

- By Market Value (2026-2035)
- By Exterior Wall Systems Installation Area (2026-2035)
- By Curtain Wall Installation Area (2026-2035)
- By Cladding Installation Area (2026-2035)
- By Architectural Glass Installation Area (2026-2035)
- By Aluminium Facade Installation Volume (2026-2035)
- By Insulated Wall System Installation Area (2026-2035)
- By Residential Exterior Wall System Installation Area (2026-2035)
- By Commercial Exterior Wall System Installation Area (2026-2035)
- By Infrastructure Exterior Wall System Installation Area (2026-2035)
- By High-Rise Building Facade Installation Area (2026-2035)
- By Green Building Facade Installation Area (2026-2035)
- By Data Centre Exterior Wall System Installation Area (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
