
 Download PDF
Market Overview
The UAE Gelcoat Market is valued at approximately ~USD XX million, supported by marine manufacturing, GRP tanks and pipes, construction composites, swimming pools and industrial FRP. The broader economic base strengthened as UAE GDP increased from USD 522.62 billion to USD 552.32 billion, while GDP per capita reached USD 50,273.5. Demand is reinforced by local polyester, vinyl ester and gelcoat manufacturing in Jebel Ali and by recurring composite consumption in marine and infrastructure applications.
Dubai, Ajman, Sharjah and Abu Dhabi form the principal UAE gelcoat demand and supply clusters. Dubai leads through Jebel Ali, where Scott Bader manufactures polyester resins, vinyl esters and gelcoats for regional markets; Ajman hosts Polychem, SAAD Fiber Glass and Al Jazira composite-material operations. UAE GDP expanded from USD 522.62 billion to USD 552.32 billion, supporting construction and industrial activity, while coastal manufacturing and yacht production reinforce marine-grade gelcoat consumption across these emirates.
Market Segmentation
By Resin Chemistry
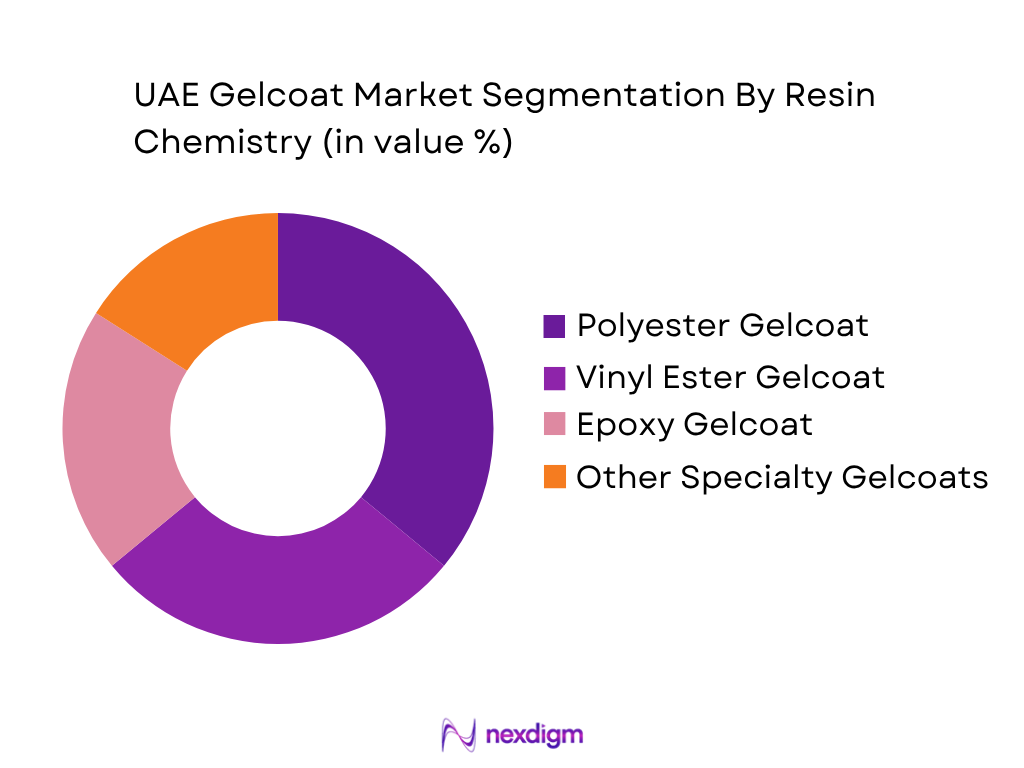
The UAE Gelcoat Market is segmented by resin chemistry into polyester, vinyl ester, epoxy and other specialty formulations. Polyester gelcoat holds the dominant position because UAE composite fabrication remains extensively linked with unsaturated polyester systems used in fiberglass boats, GRP tanks, architectural panels, pools and general-purpose moulded products. Within polyester chemistry, orthophthalic grades address general applications, while isophthalic and ISO-NPG formulations serve marine and exterior uses requiring stronger hydrolysis resistance, UV stability and gloss retention. Scott Bader’s Jebel Ali facility manufactures polyester resins, vinyl esters and gelcoats locally, strengthening availability of compatible systems. Modest Marketing also distributes orthophthalic, isophthalic and marine-grade systems, demonstrating the breadth of polyester chemistry in local supply channels. Vinyl ester gelcoats remain strategically important for chemical containment, industrial tanks, pipes and applications requiring greater corrosion and osmosis resistance.
By Application Technology
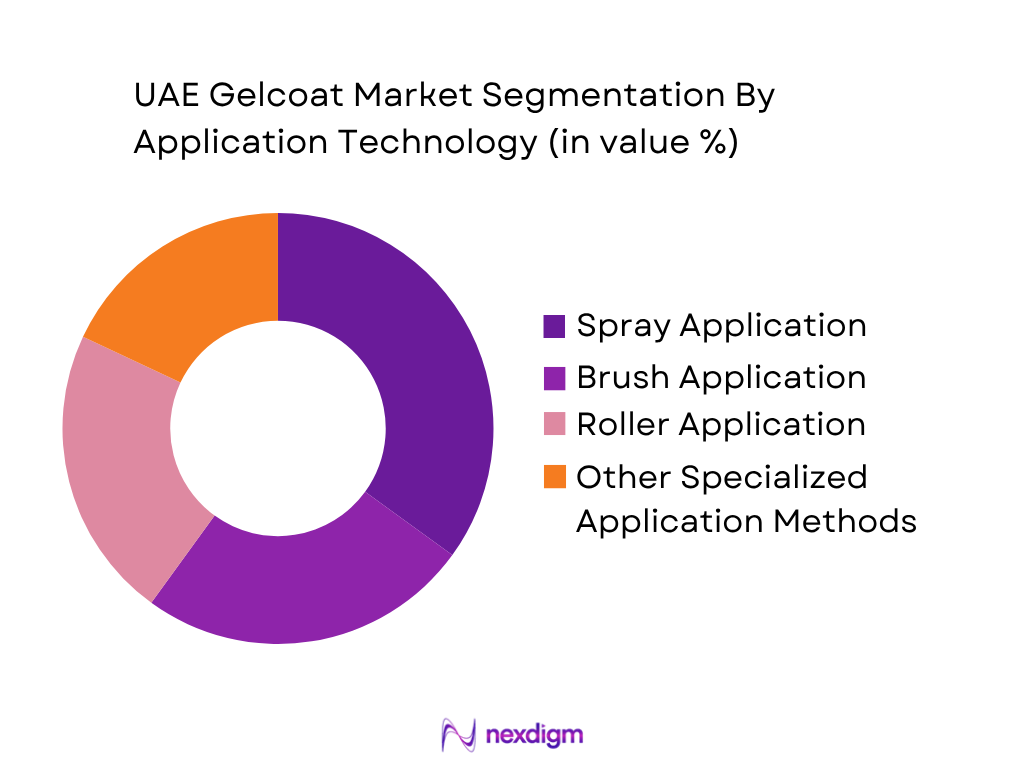
The UAE Gelcoat Market is segmented into spray application, brush and roller application, and other specialized processing methods. Spray-applied gelcoat represents the dominant application route because UAE boatbuilders, GRP tank manufacturers and larger composite fabricators require uniform film coverage, consistent surface quality and faster mould preparation across relatively large component areas. Spray systems are particularly relevant in yacht hulls, boat decks, architectural GRP components and industrial mouldings where appearance and controlled coating thickness are important. Brush and roller methods remain significant among smaller FRP fabricators, repair businesses, customized component producers and low-volume manufacturing operations because they provide flexibility without sophisticated dispensing equipment. Scott Bader identifies both manually applied and mechanically sprayed gelcoat technologies, while UAE composite suppliers provide resins, gelcoats, applicators and associated processing materials. Increasing requirements for repeatable gloss, reduced sagging, controlled catalyst addition and improved productivity are expected to support greater technical sophistication in spray processing.
Competitive Landscape
The UAE Gelcoat Market combines local manufacturing, specialized composite-material distribution and multinational formulation technology. Scott Bader Middle East has a particularly strong structural position because its Jebel Ali facility manufactures polyester resins, vinyl esters and gelcoats while serving marine, pipe, infrastructure, construction, automotive and chemical-containment customers. Ajman has developed into another important supply cluster through Polychem, SAAD Fiber Glass and Al Jazira, while Dubai-based Modest Marketing combines distribution, warehousing and technical product support.
| Company | Establishment Year | Headquarters / UAE Base | Business Model | Gelcoat & Resin Portfolio | Key UAE Applications | Local Supply Capability | Regional Reach | Technical Capability |
| Scott Bader Middle East | 1998 | Jebel Ali Free Zone, Dubai | ~ | ~ | ~ | ~ | ~ | ~ |
| Polychem Middle East | 1998 | Ajman | ~ | ~ | ~ | ~ | ~ | ~ |
| Modest Marketing LLC | 1992 | Dubai; Ajman branch | ~ | ~ | ~ | ~ | ~ | ~ |
| SAAD Fiber Glass Trading | 2006 | Ajman | ~ | ~ | ~ | ~ | ~ | ~ |
| Al Jazira Fibreglass Products Trading | 1998 | Ajman | ~ | ~ | ~ | ~ | ~ | ~ |
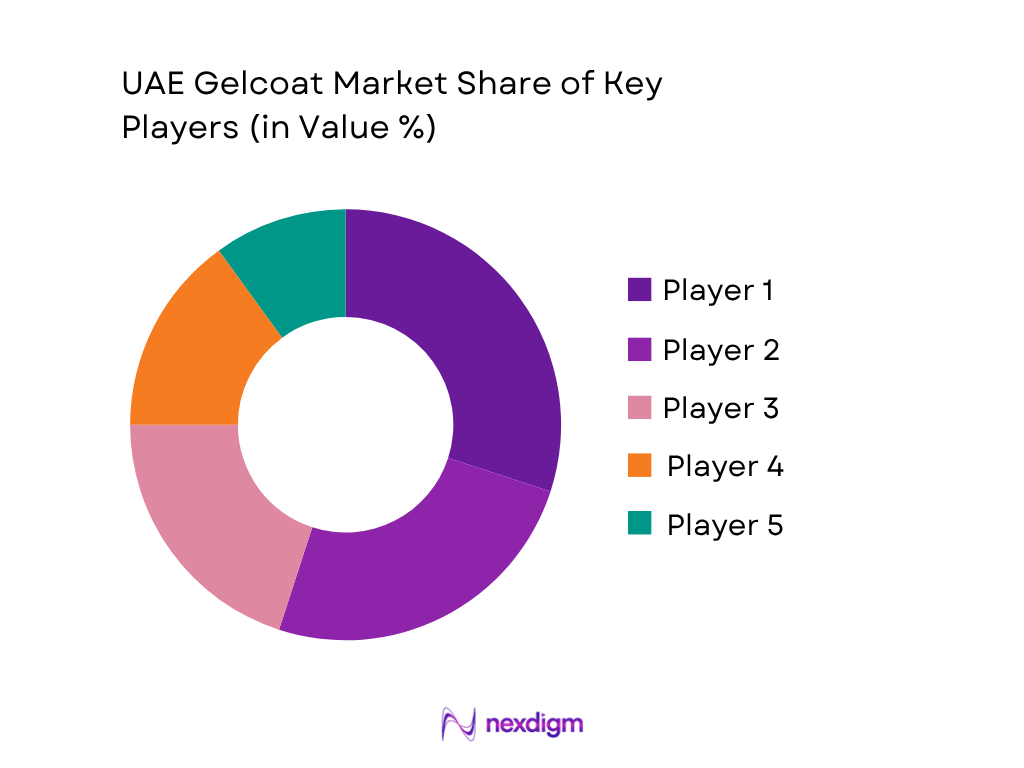
UAE Gelcoat Market Analysis
Growth Drivers
Expansion of Marine and Yacht Manufacturing Ecosystem
The UAE Gelcoat Market is supported by a substantial marine and yacht ecosystem that directly consumes marine-grade polyester, ISO-NPG and vinyl-ester gelcoats for hulls, decks, superstructures, moulded interiors and repair applications. The Dubai International Boat Show recorded more than 1,000 brands from 55 countries, over 200 displayed craft and 46 product launches in 2024, while Dubai Harbour operates 705 berths and accommodates yachts up to 160 metres, illustrating the scale of the surrounding marine service and fabrication ecosystem. This environment supports recurring requirements for high-gloss surfaces, UV stability, hydrolysis resistance, colour retention and osmosis protection. The broader macroeconomic setting reinforces premium marine demand: World Bank data places UAE GDP at USD 552.32 billion in 2024, GDP per capita at USD 50,273.5, and population at 10,986,400. These indicators are relevant because yacht ownership, leisure marine infrastructure, vessel maintenance and high-value composite fabrication are concentrated in high-income coastal economies. The combination of domestic boatbuilding capability, marina infrastructure and international marine-sector participation provides a durable demand base for technically differentiated marine gelcoat formulations.
Growth of GRP Water Infrastructure and Corrosion-Resistant Composite Applications
Water infrastructure is another important driver for UAE gelcoat demand because GRP tanks, GRE pipes, water-treatment components, liners and associated composite products require durable surfaces capable of resisting moisture, chemicals and long-term hydrolysis. DEWA recorded 150,478 million imperial gallons of desalinated water production in 2024, compared with 143,309 million imperial gallons in 2023, while installed desalination capacity stood at 495 million imperial gallons per day. DEWA’s water infrastructure also included 1,463 km of 1,200-mm transmission pipelines, 350 km of 900-mm pipelines and reservoir storage capacity of 1,002 million imperial gallons in 2024. DEWA explicitly identifies glass-reinforced epoxy pipes within its water-distribution infrastructure, confirming the direct relevance of composite materials to the utility sector. This demand is supported by a large national economy: World Bank data records UAE GDP at USD 552.32 billion in 2024, GDP per capita of USD 50,273.5, and population of 10,986,400. Rising utility loads and extensive water-handling infrastructure therefore support consumption of water-resistant, chemical-resistant and application-specific gelcoat systems used across tanks, covers, housings and molded GRP components.
Market Challenges
Dependence on Imported Polyester Resin and Styrene Feedstocks
The UAE Gelcoat Market faces material supply-chain exposure because key polyester-resin and styrene inputs are sourced in substantial volumes from international suppliers. World Bank WITS trade data shows that Saudi Arabia exported 5,779,030 kg of unsaturated polyester resin to the UAE in 2024, while India supplied 2,000,560 kg, the Netherlands 1,712,890 kg, China 1,003,000 kg and the United Kingdom 485,808 kg. Styrene supply is even more concentrated: Saudi Arabia shipped 42,400,000 kg of styrene to the UAE in 2024, followed by Kuwait with 1,618,990 kg and India with 1,082,460 kg. This structure exposes gelcoat formulators to maritime logistics, supplier concentration, shipping schedules and feedstock availability, particularly for specialized isophthalic, ISO-NPG and vinyl-ester systems. Jebel Ali Port handled 15.5 million TEUs and 5.4 million metric tonnes of breakbulk cargo in 2024, demonstrating the scale of the logistics channel supporting imported industrial materials. The World Bank recorded UAE GDP at USD 552.32 billion and GDP per capita at USD 50,273.5 in 2024, indicating a large industrial economy whose composite sector must maintain reliable raw-material continuity despite external sourcing dependencies.
High Technical Requirements Across Water, Marine and Industrial Composite Applications
UAE gelcoat suppliers face a technical challenge because major downstream applications operate in demanding environments where coating defects can impair appearance, durability or corrosion protection. DEWA produced 150,478 million imperial gallons of desalinated water in 2024, with peak daily water demand reaching 455.067 million imperial gallons, while the utility maintained 1,002 million imperial gallons of reservoir storage capacity. These water-system dimensions increase the importance of hydrolysis resistance and stable composite surfaces in GRP-related installations. Marine applications impose separate requirements: Dubai Harbour provides 705 berths for vessels reaching 160 metres, creating an operating environment where saltwater exposure, UV radiation, gloss retention and osmosis resistance are essential. Industrial specifications are equally demanding. ADNOC reported around 4.85 million barrels per day of oil-production capacity, approximately 11.5 billion standard cubic feet per day of gas capacity and operations across 35 producing fields in its 2024 sustainability reporting. Gelcoat systems used around industrial FRP components therefore require controlled formulation and compatibility with corrosion-resistant laminates. World Bank data places UAE GDP at USD 552.32 billion in 2024, reinforcing the scale of end-use industries that require consistent curing, pigmentation, surface thickness and application quality rather than general-purpose coating performance alone.
Market Opportunities
Specialty Gelcoats for Oil, Gas and Chemical-Resistant FRP Applications
The UAE Gelcoat Market has a significant opportunity to deepen penetration of vinyl-ester, novolac, chemical-resistant and high-temperature surface systems within oil, gas and process-industry composite applications. ADNOC’s 2024 sustainability reporting identifies approximately 4.85 million barrels per day of oil-production capacity, around 11.5 billion standard cubic feet per day of gas capacity and 35 producing fields, creating an extensive installed base of energy infrastructure exposed to corrosive fluids, humidity, chemicals and aggressive service conditions. ADNOC Gas additionally recorded 3,616 trillion British thermal units of sales volumes in 2024 and awarded contracts associated with expansion of UAE gas infrastructure. These current operating figures provide a strong foundation for future demand from FRP piping, chemical tanks, covers, ducts, scrubbers, liners and other corrosion-resistant composite structures where specialty gelcoats can protect the exposed surface and complement vinyl-ester laminates. The broader economic platform remains favorable: World Bank data records UAE GDP at USD 552.32 billion in 2024, GDP per capita at USD 50,273.5, and population at 10,986,400. Suppliers capable of meeting industrial qualification requirements can therefore expand beyond conventional marine and decorative gelcoats into technically demanding energy and process-sector applications.
Expansion of Water, Construction and Exterior GRP Surface Systems
Future UAE Gelcoat Market development can increasingly target UV-stabilized, hydrolysis-resistant and architectural gelcoats for water infrastructure, building components and exterior GRP systems. DEWA recorded 150,478 million imperial gallons of desalinated water production in 2024 and maintained 495 million imperial gallons per day of installed desalination capacity, while average daily water demand reached 413.865 million imperial gallons. In Abu Dhabi, Statistics Centre–Abu Dhabi recorded 299,360 buildings in 2024, compared with 281,780 buildings in 2023, and the number of real-estate units reached 783,970. These current infrastructure statistics indicate a large installed and expanding base for tanks, service enclosures, architectural composite elements, water-management products and other GRP components requiring durable finishes. The opportunity is also supported by the national industrial environment: the Federal Competitiveness and Statistics Centre reported UAE non-oil GDP of AED 1.342 trillion in 2024, while World Bank data places overall GDP at USD 552.32 billion and population at 10,986,400. Gelcoat manufacturers that develop exterior formulations combining UV durability, water resistance, colour stability, fire performance and compatibility with GRP fabrication can use these existing infrastructure fundamentals to expand into higher-specification construction and utility applications.
Future Outlook
The UAE Gelcoat Market is forecast to expand at approximately ~XX% CAGR during 2026-2035, with development increasingly concentrated in high-performance rather than purely general-purpose surface systems. Marine manufacturing, yacht refurbishment, GRP water infrastructure, chemical containment, construction composites and specialty industrial applications are expected to sustain demand.
Premium ISO-NPG and vinyl ester systems should gain strategic importance where UAE operating conditions require resistance to intense UV exposure, water, salinity, chemicals and prolonged outdoor weathering. Polynt identifies ISO-NPG gelcoats as particularly suited to premium marine and architectural applications, while vinyl ester formulations provide enhanced chemical and osmosis resistance. The UAE also possesses an established local technology platform. Scott Bader manufactures gelcoats and composite resins in Jebel Ali and serves pipes, infrastructure, construction, automotive, marine and chemical containment. This local production capability differentiates the UAE from markets dependent exclusively on finished imports and creates opportunities for faster product customization, technical support and regional exports.
Major Players
- Scott Bader Middle East
- Polychem Middle East
- Modest Marketing LLC
- SAAD Fiber Glass Trading LLC
- Al Jazira Fibreglass Products Trading LLC
- Fortune Emirates General Trading LLC
- Fusion Matrix Chemicals
- Polynt Composites
- BÜFA Composite Systems
- AOC
- allnex
- INEOS Composites
- GRP Industries
- Al Madina Fiberglass
- EFG Industries
Key Target Audience
- Gelcoat, Unsaturated Polyester and Vinyl Ester Resin Manufacturers
- Marine, Yacht and Fiberglass Boat Manufacturers
- GRP Tank, Pipe and Chemical Equipment Manufacturers
- Oil and Gas Composite Equipment Manufacturers and Contractors
- Construction, Infrastructure and Architectural Composite Manufacturers
- Composite Raw Material Distributors and Specialty Chemical Suppliers
- Investments and Venture Capitalist Firms
- Government and Regulatory Bodies (Ministry of Industry and Advanced Technology, Ministry of Energy and Infrastructure, Ministry of Climate Change and Environment, Dubai Municipality, Abu Dhabi Quality and Conformity Council)
Research Methodology
Step 1: Identification of Key Variables
The initial phase constructs an ecosystem map covering gelcoat manufacturers, polyester and vinyl ester resin suppliers, pigment producers, distributors, FRP fabricators, boatbuilders, GRP tank manufacturers and industrial customers. Critical variables include resin chemistry, application technology, domestic manufacturing, imported supply, marine exposure, infrastructure applications, customer qualification requirements and emirate-level demand concentration. Secondary and proprietary databases are used to establish consistent market definitions.
Step 2: Market Analysis and Construction
Historical UAE Gelcoat Market performance is analyzed using both top-down and bottom-up approaches. The top-down assessment examines marine manufacturing, construction composites, GRP tanks and pipes, chemical containment, swimming pools and industrial FRP demand. Bottom-up analysis evaluates supplier portfolios, local formulation capability, distributor activity, gelcoat consumption per composite application and customer procurement patterns to construct the overall market framework while minimizing double counting.
Step 3: Hypothesis Validation and Expert Consultation
Market hypotheses are validated through CATIs and structured interviews with gelcoat producers, resin suppliers, composite distributors, FRP fabricators, marine manufacturers, equipment suppliers and application specialists. Discussions assess chemistry preferences, ISO-NPG usage, vinyl ester adoption, gelcoat thickness, pigmentation requirements, catalyst systems, spray processing, environmental performance and technical support. These findings are reconciled with public company disclosures and industry-level evidence to validate the market structure.
Step 4: Research Synthesis and Final Output
The final phase triangulates manufacturer-level supply estimates with downstream application demand and distribution-channel information. Particular emphasis is placed on marine composites, GRP infrastructure, chemical-resistant equipment, building products and harsh-climate performance requirements. Historical trends and primary findings are integrated into segmentation, competitive positioning and forecast assumptions, producing a consistent UAE Gelcoat Market model covering product chemistry, applications, customer groups, emirates and the long-term competitive outlook.

- Executive Summary
- Research Methodology (Market Definition and Scope, UAE Gelcoat Market Classification, Gelcoat Demand Assessment, Unsaturated Polyester and Vinyl Ester Resin Supply Mapping, Marine Composite Industry Assessment, GRP Tank and Pipe Application Analysis, Oil and Gas Composite Application Assessment, Construction and Infrastructure FRP Demand Evaluation, Swimming Pool and Water Feature Application Assessment, Import-Export and Re-Export Analysis, End-Use Industry Demand Mapping, Gelcoat Application Technology Assessment)

- Definition and Scope
- UAE Gelcoat Industry Evolution and Development of Marine, GRP Infrastructure and Composite Fabrication Ecosystem
- Gelcoat Formulation, Resin Distribution and Fiberglass Processing Industry Structure
- UAE Gelcoat Value Chain Analysis
- UAE Gelcoat Supply Chain Analysis
- Polyester Resin Supplier, Vinyl Ester Supplier, Gelcoat Manufacturer, Pigment and Additive Supplier, Composite Material Distributor, FRP Fabricator, Marine OEM and Infrastructure Contractor Ecosystem Analysis
- Gelcoat Formulation and Application Integration Assessment Across Marine, GRP Infrastructure, Oil and Gas, Construction, Swimming Pools and Industrial Applications

- Growth Drivers (Expansion of Fiberglass Boat and Yacht Manufacturing, High Penetration of GRP Tanks and Piping, Infrastructure Demand for Corrosion-Resistant Composites, Growth of Swimming Pool and Water Feature Fabrication, Oil and Gas Demand for Chemical-Resistant FRP, Increasing Requirement for UV-Stable Exterior Composite Surfaces, Jebel Ali Composite Material Distribution Hub, Growth of Domestic FRP Fabrication)
- Market Challenges (Dependence on Imported Polyester and Vinyl Ester Feedstocks, Styrene Handling and Emission Management, Extreme Heat and UV Exposure, Surface Degradation Under Sand and Saline Environments, Gelcoat Color Fading and Gloss Retention Requirements, Variable Application Quality Among Small Fabricators, Skilled Spray Applicator Availability, Resin and Catalyst Storage Under High Ambient Temperatures)
- Market Opportunities (Premium Marine ISO-NPG Gelcoats, Vinyl Ester Gelcoats for Oil and Gas Equipment, Chemical-Resistant Gelcoats for GRP Tanks and Piping, UV-Stabilized Gelcoats for Exterior Infrastructure, Swimming Pool and Water Feature Gelcoats, Low-Styrene Formulations, Flame-Retardant Gelcoats for Public Infrastructure, Automated Gelcoat Spray Systems, Tooling Gelcoats for Local Composite Mould Production)
- Market Trends (ISO-NPG Adoption in Marine Applications, Higher-UV-Stability Formulations, Vinyl Ester Surface Systems, Pre-Pigmented Gelcoats, Custom RAL Color Matching, High-Gloss Marine Finishes, Low-Styrene Systems, Fire-Retardant Composite Surfaces, Automated Spray Processing, Local Warehousing of Specialty Gelcoats)
- Regulatory and Standards Landscape (UAE Environmental Regulations, Hazardous Chemical Storage Requirements, Occupational Health and Safety Requirements, Civil Defence Fire-Safety Requirements, Ministry of Industry and Advanced Technology Conformity Requirements, Marine Classification Requirements, Potable Water Contact Requirements for GRP Tanks, Oil and Gas Vendor Qualification Requirements)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Competition Ecosystem

- By Market Value (2020-2025)
- By Gelcoat Consumption Volume (2020-2025)
- By Domestic Gelcoat Production and Formulation Volume (2020-2025)
- By Polyester Gelcoat Consumption Volume (2020-2025)
- By Vinyl Ester Gelcoat Consumption Volume (2020-2025)
- By Gelcoat Import Volume (2020-2025)
- By Gelcoat Export and Re-Export Volume (2020-2025)

- By Resin Chemistry (In Value %)
Orthophthalic Polyester Gelcoat
Isophthalic Polyester Gelcoat
Isophthalic-NPG Gelcoat
Neopentyl Glycol Polyester Gelcoat
Vinyl Ester Gelcoat
Novolac Vinyl Ester Gelcoat
Hybrid and Modified Polyester Gelcoat
Low-Styrene Specialty Gelcoat - By Product Type (In Value %)
General-Purpose Gelcoat
Marine-Grade Gelcoat
Tooling Gelcoat
Clear Gelcoat
Pigmented and Custom-Colored Gelcoat
UV-Stabilized Gelcoat
Fire-Retardant Gelcoat
Chemical-Resistant Gelcoat
Abrasion-Resistant Gelcoat
Pool and Water-Contact Gelcoat - By Application Type (In Value %)
Marine Hull and Deck Applications
GRP Tank and Water Storage Applications
GRP and GRE Pipe Applications
Oil and Gas Equipment Applications
Chemical Processing Equipment Applications
Building and Construction Composite Applications
Swimming Pool and Water Feature Applications
Automotive and Specialty Vehicle Applications
Composite Tooling and Mould Applications - By Application Technology (In Value %)
Hand Lay-Up Gelcoat Application
Manual Spray Gelcoat Application
Airless and Air-Assisted Spray Application
Automated Spray Gelcoat Application
Brush Application
Roller Application
Open-Mould Gelcoat Application
Vacuum Infusion-Compatible Surface Systems
RTM-Compatible Surface Systems
MEKP-Cured Gelcoat Systems - By End-Use Industry (In Value %)
Marine and Boatbuilding
GRP Tanks and Water Storage
GRP and GRE Pipes
Oil and Gas
Chemical Processing Equipment
Building and Construction
Swimming Pools and Water Features
Automotive and Specialty Vehicles
Public Infrastructure and Utilities
Industrial and Composite Tooling - By Emirate (In Value %)
Dubai
Abu Dhabi
Sharjah
Ajman
Ras Al Khaimah
Umm Al Quwain
Fujairah

- Market Share of Major Players (By Revenue, Gelcoat Volume, Resin Chemistry and Product Portfolio, End-Use Industry, Application Technology, UAE Manufacturing and Formulation Footprint, Distribution Network, Customer Segment Distribution)
- Cross Comparison Parameters (UAE Gelcoat Revenue, Polyester-Vinyl Ester-ISO-NPG Portfolio Breadth, UAE Gelcoat Manufacturing and Formulation Capability, Marine and GRP Infrastructure Application Coverage, Low-Styrene and Fire-Retardant Formulation Capability, Custom Pigmentation and Color-Matching Capability, UAE Warehousing and GCC Distribution Footprint, Gelcoat Spray and FRP Technical-Service Capability)
- SWOT Analysis of Major Players
- Competitive Positioning Matrix
- Gelcoat Resin and Product Portfolio Benchmarking
- Pricing and Gelcoat Category Benchmarking
- Manufacturing and Formulation Technology Assessment
- Customer Industry and Regional Distribution Assessment
- Detailed Profiles of Major Companies
Scott Bader Middle East
Polychem Middle East
Modest Marketing LLC
SAAD Fiber Glass Trading LLC
Al Jazira Fibreglass Products Trading LLC
Fortune Emirates General Trading LLC
Fusion Matrix Chemicals
Polynt Composites
BÜFA Composite Systems
AOC
allnex
INEOS Composites
GRP Industries
Al Madina Fiberglass
EFG Industries

- Marine and Boatbuilder Gelcoat Procurement Assessment
- Yacht and Leisure Craft Gelcoat Requirement Analysis
- GRP Tank Manufacturer Gelcoat Procurement Assessment
- GRP and GRE Pipe Fabricator Requirement Analysis
- Oil and Gas Composite Fabricator Gelcoat Assessment
- Chemical Processing Equipment Manufacturer Surface Protection Analysis
- Swimming Pool and Water Feature Manufacturer Gelcoat Assessment
- Construction Composite Manufacturer Gelcoat Requirement Analysis
- Industrial FRP and Composite Tooling Customer Analysis

- By Market Value (2026-2035)
- By Gelcoat Consumption Volume (2026-2035)
- By Domestic Gelcoat Production and Formulation Volume (2026-2035)
- By Polyester Gelcoat Consumption Volume (2026-2035)
- By Vinyl Ester Gelcoat Consumption Volume (2026-2035)
- By Gelcoat Import Volume (2026-2035)
- By Gelcoat Export and Re-Export Volume (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
