
 Download PDF
Market Overview
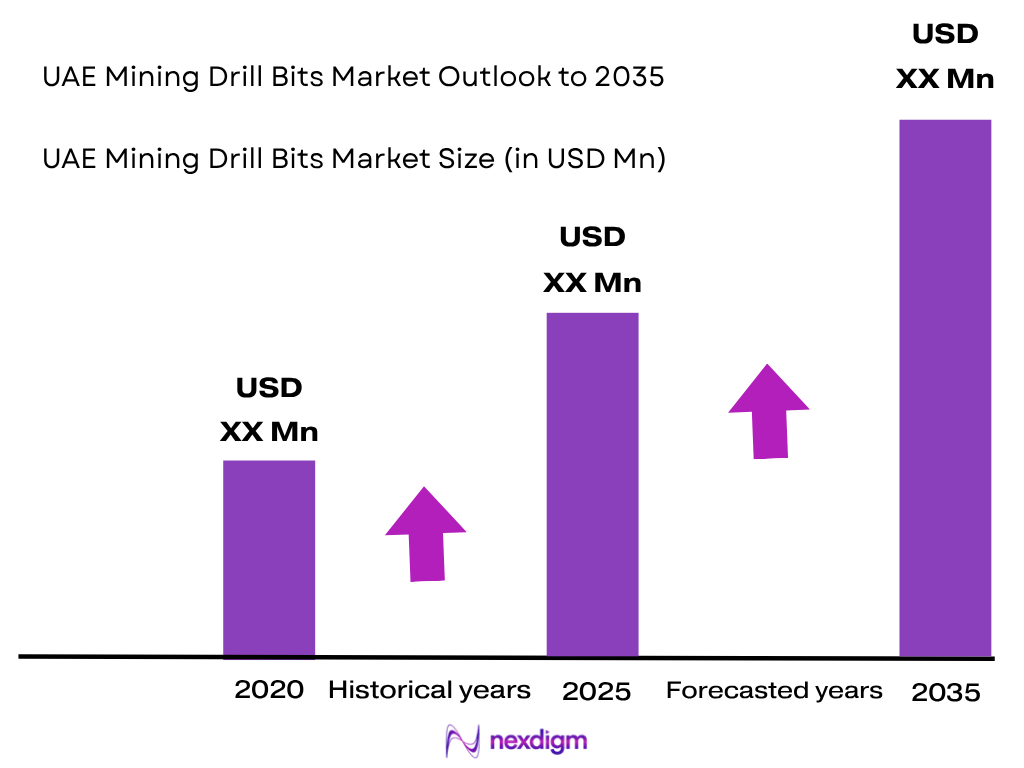
The UAE Mining Drill Bits Market is estimated at ~USD XX million in 2024, with a projected CAGR of XX% during 2026-2035. Demand is closely linked to quarrying, aggregate production, construction activity and rock excavation. Fujairah is particularly important because its mining ecosystem includes gabbro and other hard-rock resources used for construction materials. The Fujairah Mining Observatory records 460 mining-facility site permits and 26,727 mining-facility transactions, demonstrating the scale of regulated mining activity in the emirate. The UAE’s real GDP reached AED 1.776 trillion in 2024, while construction expanded 8.4%, supporting downstream requirements for aggregates and drilling consumables.
Fujairah represents the principal mining and quarrying center for UAE Mining Drill Bits Market demand because of its extensive mountainous terrain, hard-rock resources, quarrying infrastructure and export connectivity. The Fujairah Mining Observatory identifies 3 mining zones, 8 major processing plants, 3 export outlets and 14 investment opportunities, while the emirate’s GDP reached AED 29.130 billion in 2024. The wider northern Emirates also contribute through limestone and hard-rock quarrying. Official UAE geological information identifies substantial limestone and hard-rock resources in the northern Emirates used for aggregates and cement raw materials.
Market Segmentation
By Drill Bit Type
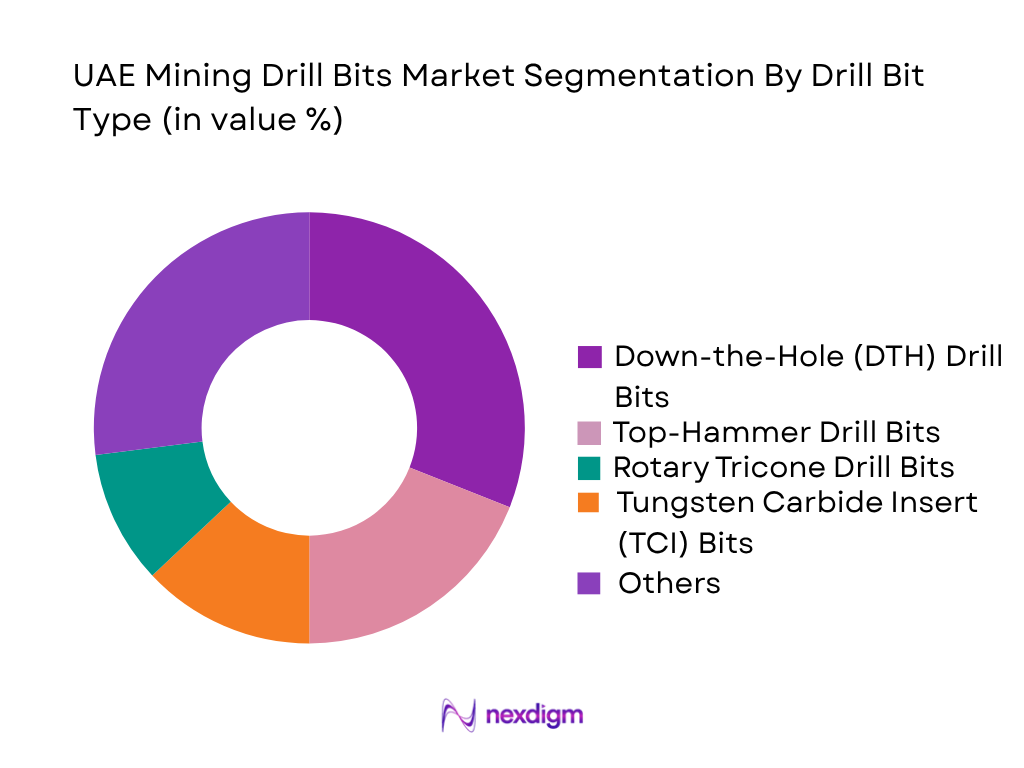
The UAE Mining Drill Bits Market is segmented by drill bit type into Down-the-Hole (DTH) drill bits, top-hammer drill bits, rotary tricone drill bits, tungsten carbide insert (TCI) bits, milled-tooth drill bits, polycrystalline diamond compact (PDC) bits, diamond core bits, drag bits, button bits and specialty mining drill bits. DTH drill bits represent the leading sub-segment because they are closely aligned with hard-rock quarrying, blast-hole drilling and large-scale aggregate extraction. Fujairah’s geological environment contains extensive ophiolite-derived rocks, including gabbro, while approximately 1,200 square kilometres of the emirate consists of mountains and rocky highlands. The designated mining areas cover approximately 100 square kilometres, creating concentrated drilling requirements. DTH systems are suited to hard formations because the hammer operates directly at the bottom of the hole, supporting penetration and drilling efficiency. Their application across quarry benches, construction aggregates and rock excavation further broadens their addressable demand.
By Mining Application
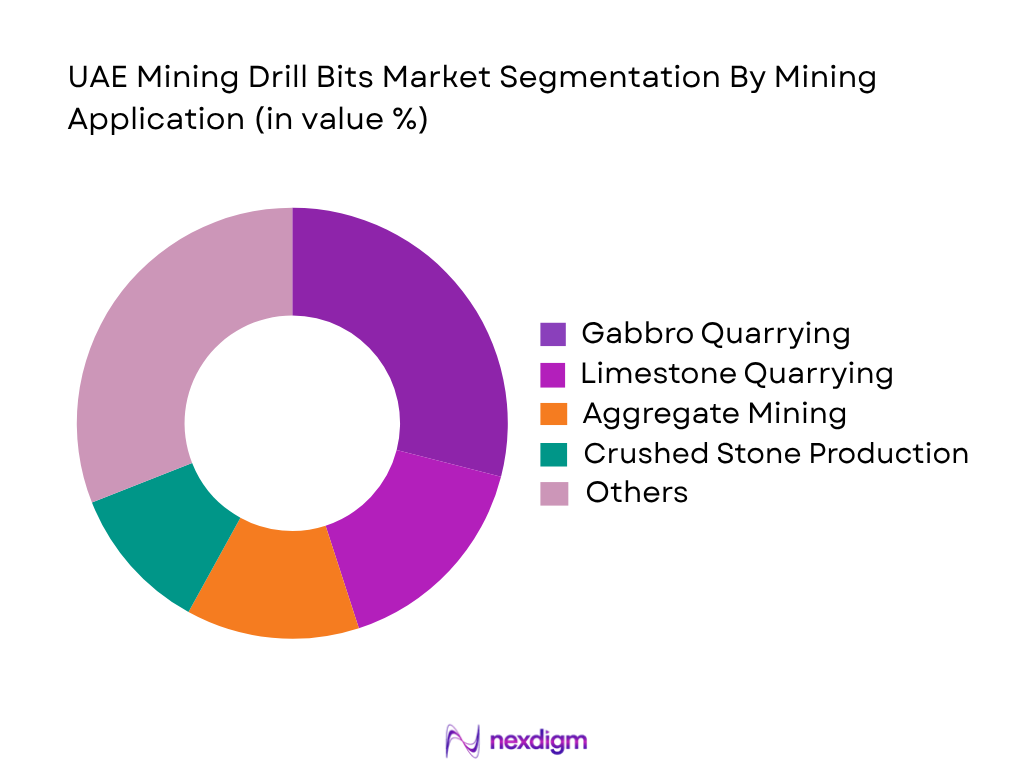
The UAE Mining Drill Bits Market is segmented by mining application into gabbro quarrying, limestone quarrying, aggregate mining, crushed stone production, construction material quarrying, cement raw material extraction, industrial mineral extraction, exploration drilling, infrastructure rock excavation and other mining and quarrying applications. Gabbro quarrying represents a major application because the northern Emirates contain substantial hard-rock resources and Fujairah has developed a specialized quarrying ecosystem around these materials. The Fujairah Mining Observatory identifies the Al Tawyeen-Habhab area as containing extensive deposits of gabbro and diorite and reports approximately 40-45 active crushers and 10-15 factories in the area. The UAE’s geological authorities also identify northern hard-rock resources as important inputs for construction aggregates and cement manufacturing. These operations require drilling for bench development, blasting and rock fragmentation, creating recurring consumption of DTH, top-hammer and carbide-equipped drill bits.
Competitive Landscape
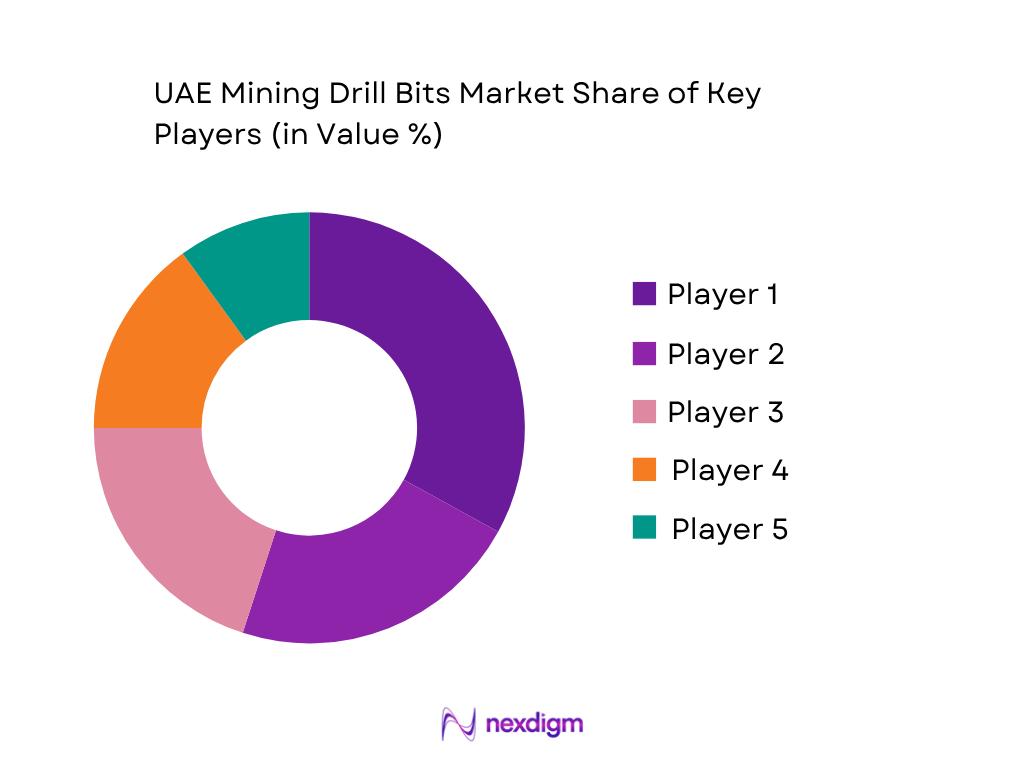
The UAE Mining Drill Bits Market includes international manufacturers of drilling equipment, rock tools and mining consumables alongside regional distributors and service providers. Competition is influenced by DTH technology, carbide insert quality, bit durability, compatibility with drilling rigs, penetration performance and aftermarket support. Companies with established mining-equipment portfolios can serve quarry operators through integrated drill-rig, hammer and consumable offerings. Fujairah’s established quarrying infrastructure, including 460 permitted mining-facility sites, provides an important customer base for suppliers of replacement drill bits and associated rock-drilling products.
| Company | Establishment Year | Headquarters | DTH Technology | Top-Hammer Technology | Rotary Drilling | Carbide Technology | Quarrying Applications | Aftermarket Support | Regional Presence |
| Epiroc | 2018 | Stockholm, Sweden | ~ | ~ | ~ | ~ | ~ | ~ | ~ |
| Sandvik | 1862 | Stockholm, Sweden | ~ | ~ | ~ | ~ | ~ | ~ | ~ |
| Boart Longyear | 1890 | Salt Lake City, USA | ~ | ~ | ~ | ~ | ~ | ~ | ~ |
| Mincon Group | 1977 | Shannon, Ireland | ~ | ~ | ~ | ~ | ~ | ~ | ~ |
| Robit | 1975 | Lempäälä, Finland | ~ | ~ | ~ | ~ | ~ | ~ | ~ |
UAE Mining Drill Bits Market Analysis
Growth Drivers
Expansion of Construction and Infrastructure Activity
The UAE Mining Drill Bits Market is supported by the country’s large construction and infrastructure base, which generates sustained requirements for quarrying, aggregate production, rock excavation and drilling-and-blasting activities. The UAE Ministry of Energy and Infrastructure reported that the construction sector was valued at approximately AED 150 billion in 2024, providing a substantial downstream base for quarry-derived aggregates and dimensioned rock materials used across infrastructure projects. The World Bank records UAE GDP at USD 552.32 billion in 2024, while GDP per capita reached USD 50,273.5, reflecting the scale of economic activity supporting capital-intensive construction and industrial operations. The UAE Ministry of Energy and Infrastructure also reported in 2026 that the national transport and road-project portfolio exceeded AED 170 billion through 2030, including an AED 750 million investment in federal-road upgrading. Such infrastructure activity requires continuous supplies of aggregates and construction materials, sustaining drilling requirements at quarry sites. The combination of large infrastructure expenditure, urban development and rock-based construction-material production creates recurring consumption of DTH, rotary, top-hammer and carbide-based drill bits. The market therefore benefits from continued quarry development and increasing requirements for productive drilling systems capable of maintaining penetration performance in hard-rock formations.
Diversification and Industrial Investment Supporting Mining Equipment Demand
The UAE Mining Drill Bits Market is also supported by economic diversification, industrial investment and expanding non-hydrocarbon activity. The World Bank records UAE GDP growth of 4.0 in 2024, with GDP reaching USD 552.32 billion, while the IMF reported real non-hydrocarbon GDP growth of 5.0 in 2024. This expansion is relevant to mining-drill-bit demand because quarrying supplies construction aggregates and industrial minerals used by manufacturing, infrastructure and real-estate activities. The UAE attracted USD 45.64 billion of foreign direct investment inflows in 2024, according to World Bank data based on international balance-of-payments sources, indicating substantial international capital deployment across the economy. The IMF further reported that construction, manufacturing, tourism and financial services were important contributors to non-hydrocarbon activity. For the Mining Drill Bits Market, this diversification creates multiple downstream demand channels rather than reliance on a single mining application. Expansion of industrial zones, logistics infrastructure, manufacturing facilities and construction projects increases requirements for quarried rock and aggregates, while drilling contractors require dependable consumables to maintain equipment utilization. Continued investment in non-hydrocarbon sectors therefore supports quarrying activity and creates opportunities for suppliers offering durable drilling tools, optimized bit configurations and technical support for UAE operating conditions.
Market Challenges
Dependence on Hard-Rock Quarrying Conditions and Drill-Bit Wear
The UAE Mining Drill Bits Market faces operational challenges associated with the hard and abrasive geological conditions encountered in major quarrying areas, particularly in Fujairah and the eastern UAE. Hard-rock drilling places high mechanical loads on buttons, carbide inserts, cutting structures and threaded connections, increasing the importance of penetration rate, bit life and resistance to premature wear. The challenge is commercially significant because drilling consumables are repeatedly exposed to impact, abrasion, vibration and elevated operating stresses. The Fujairah mining ecosystem is particularly relevant because quarrying and aggregate-processing operations form an established industrial cluster serving construction markets. The UAE Ministry of Energy and Infrastructure reported a national construction sector valued at approximately AED 150 billion in 2024, demonstrating the scale of downstream demand that requires reliable aggregate supplies. At the same time, the World Bank recorded USD 552.32 billion in UAE GDP in 2024, indicating substantial economic activity dependent on infrastructure and construction inputs. Operators therefore require consistent drilling productivity while managing consumable replacement and equipment downtime. Manufacturers must continuously optimize carbide grades, button geometry, flushing arrangements and bit designs for specific formations. Differences in rock hardness, fracture characteristics and drilling parameters can also make standardized product configurations less effective across individual quarry sites.
Imported Technology, Supply-Chain Exposure and Specialized Equipment Requirements
The UAE Mining Drill Bits Market faces supply-chain and technology challenges because sophisticated drilling consumables, carbide components and specialized rock-drilling systems are frequently sourced through international manufacturers and regional distribution networks. This creates exposure to international logistics conditions, lead times, inventory requirements and fluctuations in availability of specialized components. The UAE’s strong international trade position partly offsets these constraints, but the market remains dependent on efficient import and distribution channels for technically specialized drilling products. World Bank data show that the UAE attracted USD 45.64 billion in FDI inflows in 2024, demonstrating its deep integration with international capital and commercial networks. The World Bank also records UAE GDP at USD 552.32 billion in 2024, reflecting the scale of the economy in which imported industrial equipment is deployed. From an operational perspective, mining contractors cannot easily substitute high-performance drill bits when a particular rig, thread configuration or drilling application requires a specialized design. Maintaining adequate local inventories is therefore important, particularly for quarry operators with continuous production schedules. Suppliers must also provide technical assistance covering bit selection, drilling parameters, flushing practices and wear analysis. These requirements increase the importance of regional warehousing, aftermarket support and engineering capabilities within the UAE Mining Drill Bits Market.
Market Opportunities
Development of Advanced Drilling Solutions for Large Infrastructure Demand
The UAE Mining Drill Bits Market has an opportunity to expand through advanced drilling products designed to improve penetration efficiency, service life and drilling consistency in hard-rock quarrying. The opportunity is supported by the scale of infrastructure activity: the UAE Ministry of Energy and Infrastructure reported a national transport and road-project portfolio exceeding AED 170 billion through 2030, including an AED 750 million federal-road upgrading investment. The same ministry reported that the UAE construction sector was valued at approximately AED 150 billion in 2024. These figures indicate continuing downstream requirements for aggregates, crushed rock and construction materials, creating a basis for recurring quarry drilling activity. Suppliers can address this demand through optimized DTH bits, high-performance top-hammer configurations, advanced carbide button designs and application-specific cutting structures. Digital monitoring and drilling-performance analysis can further improve bit-selection decisions by linking penetration rates, operating pressure, rotation speed and wear characteristics with individual geological formations. The opportunity extends beyond simply increasing unit sales because quarry operators can benefit from products that reduce unplanned bit changes and improve drilling consistency. Manufacturers that combine drilling consumables with technical services, application engineering and wear-analysis programs can therefore develop deeper relationships with UAE quarry operators and drilling contractors while supporting productivity across infrastructure-material supply chains.
Expansion of Local Industrial Ecosystems and Specialized Mining Services
The UAE Mining Drill Bits Market can also benefit from continued development of industrial ecosystems, foreign investment and specialized technical services around quarrying and construction-material production. World Bank data show that UAE FDI inflows reached USD 45.64 billion in 2024, while UAE GDP reached USD 552.32 billion, providing evidence of substantial economic activity and international investment capacity. The IMF reported real non-hydrocarbon GDP growth of 5.0 in 2024, with construction, manufacturing, tourism and financial services contributing to diversification. These conditions create opportunities for suppliers to establish stronger local distribution, inventory and technical-support capabilities for drilling consumables. Rather than relying exclusively on product imports, market participants can develop regional service models covering bit selection, drilling optimization, refurbishment assessment, wear monitoring and operator training. The opportunity is particularly relevant for drilling contractors and quarry operators seeking to improve equipment utilization and reduce interruptions caused by unsuitable consumables. Localized technical support can also shorten response times for replacement requirements and enable suppliers to adapt drilling-bit configurations to individual rock formations and rig specifications. As infrastructure, manufacturing and logistics investment continues to develop, suppliers with integrated equipment-support capabilities can participate more deeply in the UAE’s industrial supply chain while addressing the specialized requirements of hard-rock drilling operations.
Future Outlook
Over the coming decade, the UAE Mining Drill Bits Market is expected to develop alongside quarrying modernization, construction-material demand and increased emphasis on drilling productivity. The market outlook will be shaped by higher-performance DTH systems, longer-life carbide inserts, automated drilling equipment and digital monitoring technologies. Fujairah’s established mining infrastructure provides a strong base for continued rock-tool consumption, while the UAE’s broader economic diversification supports construction, manufacturing and infrastructure activity. The country’s construction activity expanded 8.4% in 2024, while transportation and storage increased 9.6%, reinforcing the broader infrastructure ecosystem that supports demand for aggregates and quarry products.
Demand is also likely to become increasingly performance-oriented, with quarry operators evaluating drill bits through penetration rate, service life, meters drilled per bit, fuel efficiency and downtime. The shift toward digital drilling and automated equipment can create opportunities for suppliers that combine consumables with drilling-performance monitoring and technical services. Environmental management will remain relevant because Fujairah’s mining authority emphasizes environmental assessment, pollution reduction, monitoring and waste-management practices in mining operations.
Major Players
- Epiroc Middle East FZE
- Sandvik Mining and Construction Middle East FZE
- Boart Longyear
- Mincon Group plc
- Robit Plc
- Furukawa Rock Drill Co., Ltd.
- Komatsu Ltd.
- Caterpillar Inc.
- Mitsubishi Materials Corporation
- Brunner & Lay, Inc.
- Rockmore International
- Center Rock Inc.
- Drill King International L.P.
- DATC Group
- Geodrill Limited
Key Target Audience
- Mining and Quarrying Companies
- Gabbro and Limestone Quarry Operators
- Construction Aggregate Producers
- Drilling and Blasting Contractors
- Mining Equipment Distributors and Dealers
- Investments and Venture Capitalist Firms
- Government and Regulatory Bodies (Fujairah Natural Resources Corporation, UAE Ministry of Energy and Infrastructure)
- Cement and Construction Material Manufacturers
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves mapping the UAE Mining Drill Bits Market ecosystem across quarry operators, drilling contractors, equipment manufacturers, distributors and end-use industries. The assessment identifies variables including drill-bit type, diameter, drilling method, rock formation, application, replacement frequency and equipment compatibility. Secondary information from UAE government and mining authorities is incorporated to establish the market’s operating environment.
Step 2: Market Analysis and Construction
Historical market information is structured through a combination of top-down and bottom-up approaches covering drill-bit consumption, quarrying activity, equipment deployment and replacement requirements. Production and operational indicators from UAE mining authorities are evaluated alongside information concerning gabbro, limestone, aggregates and other quarry materials. Demand is then mapped across drilling methods and end-use applications.
Step 3: Hypothesis Validation and Expert Consultation
Market hypotheses are validated through discussions with drilling contractors, quarry operators, rock-tool distributors and mining-equipment specialists. Interviews focus on bit selection criteria, penetration performance, service life, drilling conditions, replacement cycles and procurement practices. Technical feedback is used to validate assumptions concerning DTH, top-hammer, rotary and core-drilling applications.
Step 4: Research Synthesis and Final Output
The final stage integrates supply-side and demand-side findings into a structured UAE Mining Drill Bits Market assessment. Company capabilities, product portfolios, technology coverage, application exposure and aftermarket networks are benchmarked. The resulting analysis is cross-checked against government mining information and industry-specific operating indicators to produce a consistent market framework.

- Executive Summary
- Research Methodology (Market Definition and Scope, UAE Mining Drill Bits Market Classification, Drill Bit Technology Mapping, Down-the-Hole (DTH) Bit Assessment, Top-Hammer Bit Evaluation, Rotary Tricone Bit Analysis, Tungsten Carbide Insert (TCI) Bit Assessment, Milled-Tooth Bit Evaluation, Polycrystalline Diamond Compact (PDC) Bit Analysis, Diamond Core Bit Assessment, Button Bit Evaluation, Drag Bit Assessment, Specialty Mining Bit Mapping, Rock Formation and Drillability Assessment, Bit Material and Carbide Grade Evaluation, Bit Diameter and Shank Configuration Analysis, Drilling Equipment Compatibility Assessment, Bit Consumption and Replacement-Cycle Analysis, Quarry and Open-Pit Drilling Assessment, Exploration Drilling Assessment, Blast-Hole Drilling Evaluation, Market Sizing Framework, Top-Down Analysis, Bottom-Up Analysis, Demand-Side Assessment, Supply-Side Assessment, Primary Industry Interviews, Data Triangulation, Forecasting Framework)

- Definition and Scope
- UAE Mining Drill Bits Industry Evolution and Development of Quarrying and Aggregate Extraction, Gabbro and Limestone Mining Expansion, Blast-Hole Drilling Adoption, Drilling and Blasting Contractor Development, Open-Pit Quarrying Technology Advancement, Construction Aggregate Demand, Infrastructure-Led Quarrying Activity, Exploration Drilling Development, Mining Equipment Localization, Digital Drilling Technology Adoption and Rock Excavation Productivity Enhancement
- Mining Drill Bits Value Chain Analysis
- Mining Drill Bits Supply Chain Analysis
- Carbide and Steel Material Suppliers, Drill Bit Manufacturers, DTH Hammer Manufacturers, Drill Rig Manufacturers, Rock Tool Suppliers, Mining Equipment Distributors, Drilling and Blasting Contractors, Quarry Operators, Aggregate Producers, Limestone Producers, Gabbro Producers, Construction Material Suppliers, Mining Equipment Service Providers, Replacement Parts Distributors, Industrial Procurement Companies and End-Use Mining and Quarrying Operations

- Growth Drivers (Expansion of Gabbro and Limestone Quarrying, Construction Aggregate Demand, Infrastructure Development, Growth of Drilling and Blasting Activities, Open-Pit Quarrying Expansion, Replacement Demand for Rock Tools, Increasing Quarry Productivity Requirements)
- Market Challenges (Dependence on Imported Drill Bits and Rock Tools, High Wear Rates in Abrasive Rock Formations, Drill Bit Replacement Requirements, Equipment Compatibility Constraints, Harsh Operating Conditions, Skilled Drilling Operator Requirements, Maintenance and Downtime Risks)
- Market Opportunities (Advanced DTH Bit Technologies, High-Wear-Resistance Carbide Bit Development, Automated Drilling Systems, Digital Drill Monitoring, High-Productivity Quarry Drilling, Extended-Life Drill Bits, Predictive Maintenance Solutions, Expansion of Gabbro Quarrying)
- Market Trends (Increasing DTH Technology Adoption, Larger-Diameter Blast-Hole Drilling, High-Performance Carbide Inserts, Automated Drill Rig Integration, Digital Drilling Monitoring, Longer Bit Service Life, Optimization of Penetration Rates, Growth of Quarry Automation, Integrated Drill-and-Blast Solutions, Increasing Demand for Aftermarket Rock Tools)
- Government Regulations and Standards (UAE Federal Mining and Quarrying Framework, Fujairah Natural Resources Corporation Requirements, Local Quarry Licensing Requirements, Environmental Impact Assessment Requirements, Blasting Permit Requirements, Occupational Health and Safety Requirements, Explosives Handling Regulations)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Competition Ecosystem

- By Market Value (2020-2025)
- By Volume Consumption (2020-2025)
- By Average Selling Price (2020-2025)
- By Drill Bit Consumption Volume (2020-2025)
- By DTH Drill Bit Consumption Volume (2020-2025)
- By Top-Hammer Drill Bit Consumption Volume (2020-2025)
- By Rotary Tricone Drill Bit Consumption Volume (2020-2025)
- By Diamond Core Bit Consumption Volume (2020-2025)
- By Tungsten Carbide Insert (TCI) Bit Consumption Volume (2020-2025)
- By Blast-Hole Drilling Consumption Volume (2020-2025)
- By Quarry Drilling Consumption Volume (2020-2025)
- By Exploration Drilling Consumption Volume (2020-2025)

- By Drill Bit Type (In Value %)
Down-the-Hole (DTH) Drill Bits
Top-Hammer Drill Bits
Rotary Tricone Drill Bits
Tungsten Carbide Insert (TCI) Bits
Milled-Tooth Drill Bits
Polycrystalline Diamond Compact (PDC) Bits
Diamond Core Bits
Drag Bits
Button Bits
Specialty Mining Drill Bits - By Drilling Method (In Value %)
DTH Drilling
Top-Hammer Drilling
Rotary Drilling
Rotary Percussion Drilling
Diamond Core Drilling
Reverse Circulation Drilling
Air-Core Drilling
Blast-Hole Drilling - By Mining Application (In Value %)
Gabbro Quarrying
Limestone Quarrying
Aggregate Mining
Crushed Stone Production
Construction Material Quarrying
Cement Raw Material Extraction
Industrial Mineral Extraction
Exploration Drilling
Infrastructure Rock Excavation
Other Mining and Quarrying Applications - By Bit Diameter (In Value %)
Small-Diameter Drill Bits
Medium-Diameter Drill Bits
Large-Diameter Drill Bits
Extra-Large-Diameter Drill Bits - By End-Use Industry (In Value %)
Quarrying Industry
Construction Aggregate Industry
Cement Industry
Limestone Mining Industry
Gabbro Mining Industry
Infrastructure Development
Mining Contractors
Drilling and Blasting Contractors
Industrial Mineral Producers
Exploration and Geotechnical Drilling - By Region (In Value %)
Fujairah
Ras Al Khaimah
Abu Dhabi
Dubai
Sharjah
Ajman
Other UAE Regions

- Market Share of Major Players (By UAE Revenue, Drill Bit Product Portfolio, DTH Bit Coverage, Top-Hammer Bit Capability, Rotary Bit Portfolio, Carbide Technology, Bit Diameter Range, Rock Formation Coverage, Quarrying Application Coverage, Drill Rig Compatibility, Production Capacity, Distribution Network, Aftermarket Service Capability, Regional Presence, Customer Base)
- Cross Comparison Parameters (DTH Drill Bit Portfolio Breadth, Top-Hammer Bit Technology Capability, Rotary Tricone Bit Coverage, Carbide Grade and Insert Technology, Drill Bit Diameter Range, Rock Formation Application Coverage, Drill Rig Compatibility, Aftermarket and Rock Tool Service Network)
- SWOT Analysis of Major Players
- Competitive Positioning Matrix
- Drill Bit Technology and Application Benchmarking
- DTH Bit Performance and Penetration Assessment
- Drilling and Blasting Contractor Solution Assessment
- Detailed Profiles of Major Companies
Epiroc Middle East FZE
Sandvik Mining and Construction Middle East FZE
Boart Longyear
Furukawa Rock Drill Co., Ltd.
Komatsu Ltd.
Caterpillar Inc.
Robit Plc
Mincon Group plc
Mitsubishi Materials Corporation
Mitsubishi Materials Trading Corporation
Brunner & Lay, Inc.
Rockmore International
Drill King International L.P.
Center Rock Inc.
DATC Group

- Quarry Operator Drill Bit Requirement Assessment
- Gabbro Quarry Drilling Demand Analysis
- Limestone Quarry Drilling Requirement Assessment
- Aggregate Producer Drill Bit Consumption Analysis
- Cement Raw Material Quarrying Requirement Assessment
- Drilling and Blasting Contractor Procurement Assessment
- Blast-Hole Drilling Requirement Analysis
- Mining Equipment Distributor Demand Assessment
- Exploration Drilling Requirement Analysis
- Drill Rig Compatibility Assessment
- Drill Bit Replacement-Cycle Analysis
- Rock Formation and Abrasiveness Assessment
- Drill Bit Performance Preference Assessment
- Aftermarket Rock Tool Procurement Analysis

- By Market Value (2026-2035)
- By Volume Consumption (2026-2035)
- By Average Selling Price (2026-2035)
- By Drill Bit Consumption Volume (2026-2035)
- By DTH Drill Bit Consumption Volume (2026-2035)
- By Top-Hammer Drill Bit Consumption Volume (2026-2035)
- By Rotary Tricone Drill Bit Consumption Volume (2026-2035)
- By Diamond Core Bit Consumption Volume (2026-2035)
- By Tungsten Carbide Insert (TCI) Bit Consumption Volume (2026-2035)
- By Blast-Hole Drilling Consumption Volume (2026-2035)
- By Quarry Drilling Consumption Volume (2026-2035)
- By Exploration Drilling Consumption Volume (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
