
 Download PDF
Market Overview
The UAE Plastic Pipes and Fittings Market is valued at approximately USD ~XX billion, supported by demand from water transmission, residential construction, commercial infrastructure, irrigation, wastewater management, and industrial applications. The UAE plastic hot and cold pipe segment was valued at USD 95.3 million in 2024, reflecting demand from plumbing and building applications. The market is driven by the country’s continued infrastructure expansion, with the UAE’s construction sector supported by large-scale urban development, water infrastructure investments, and industrial projects. The UAE’s polyolefin supply ecosystem is strengthened by domestic producers such as Borouge, which manufactures polyethylene and polypropylene materials used in pipe applications.
The UAE Plastic Pipes and Fittings Market is concentrated around Dubai, Abu Dhabi, Sharjah, and other developed emirates due to their extensive construction activity, water infrastructure requirements, and industrial development. Dubai remains a major demand center because of high-density residential projects, commercial buildings, hospitality developments, and district cooling networks. Abu Dhabi drives demand through government infrastructure projects, utility networks, oil and gas facilities, and large-scale urban developments. The UAE’s expanding urban infrastructure requires reliable piping systems for potable water, wastewater, irrigation, and cooling applications. Government utility entities including Dubai Electricity and Water Authority and Abu Dhabi Distribution Company continue supporting demand for advanced piping solutions.
Market Segmentation
By Material Type
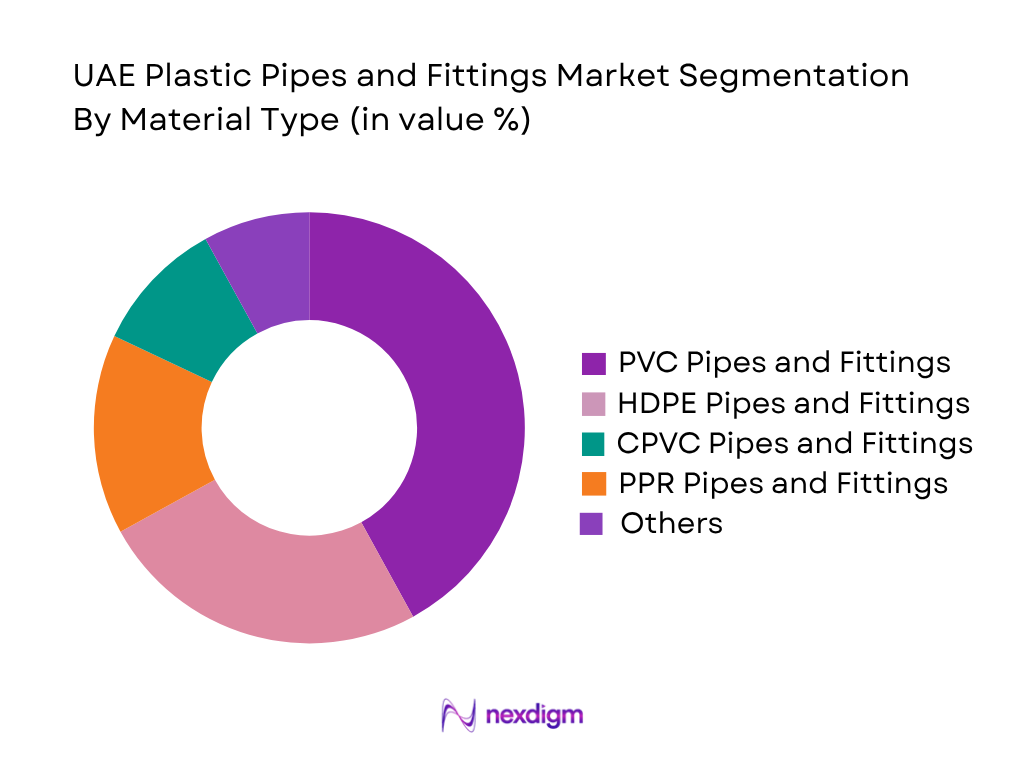
The UAE Plastic Pipes and Fittings Market is segmented by material type into PVC pipes and fittings, HDPE pipes and fittings, CPVC pipes and fittings, PPR pipes and fittings, MDPE pipes and fittings, polyethylene pipes, and composite plastic pipes. PVC pipes and fittings represent the dominant material category due to their widespread adoption in drainage systems, water distribution networks, irrigation applications, and residential plumbing. PVC systems are preferred because of their durability, corrosion resistance, lightweight characteristics, and suitability for UAE climatic conditions. HDPE is increasingly adopted for municipal water transmission, underground utilities, and industrial applications due to flexibility and resistance to environmental stress. CPVC and PPR systems are gaining acceptance in residential and commercial plumbing projects where temperature resistance and long service life are required.
By Application Type
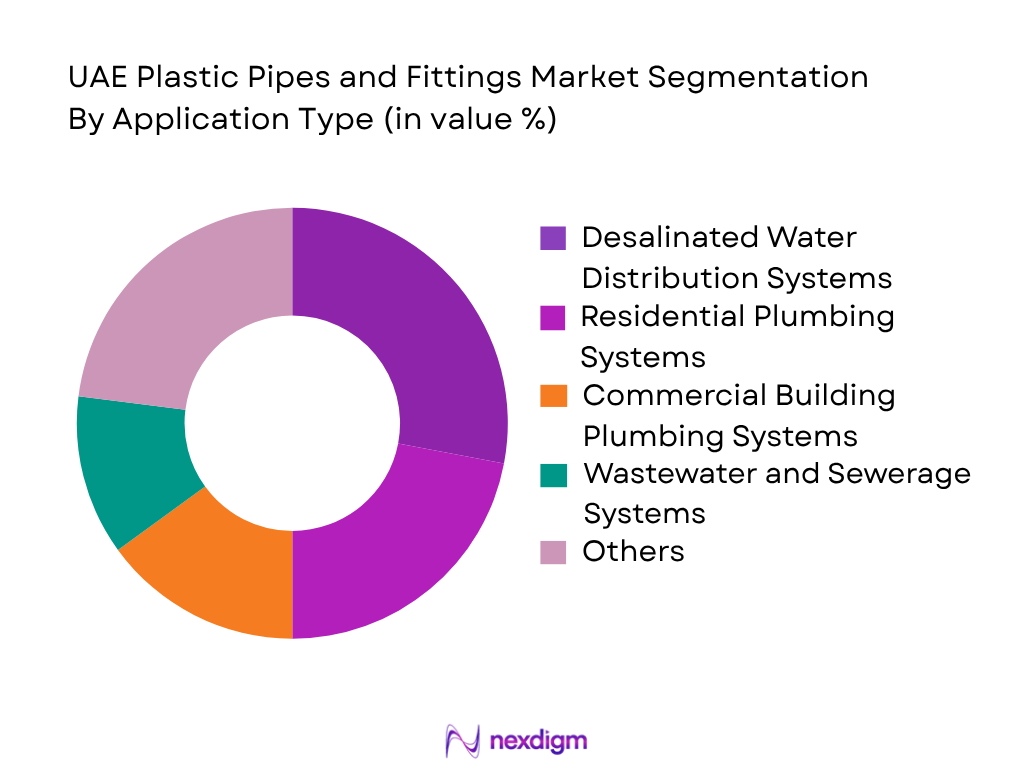
The UAE Plastic Pipes and Fittings Market is segmented by application into desalinated water distribution systems, residential plumbing systems, commercial buildings, wastewater networks, district cooling infrastructure, irrigation systems, oil and gas applications, and industrial process piping. Desalinated water distribution and municipal water infrastructure represent a leading application segment due to the UAE’s dependence on water treatment and transmission networks. The country operates large desalination facilities requiring extensive piping systems for water transportation and utility distribution. Residential and commercial construction also contribute significantly due to continuous development of housing communities, hotels, offices, and mixed-use projects. HDPE and PVC pipes are widely used in utility applications, while CPVC and PPR systems are preferred in building plumbing installations.
Competitive Landscape
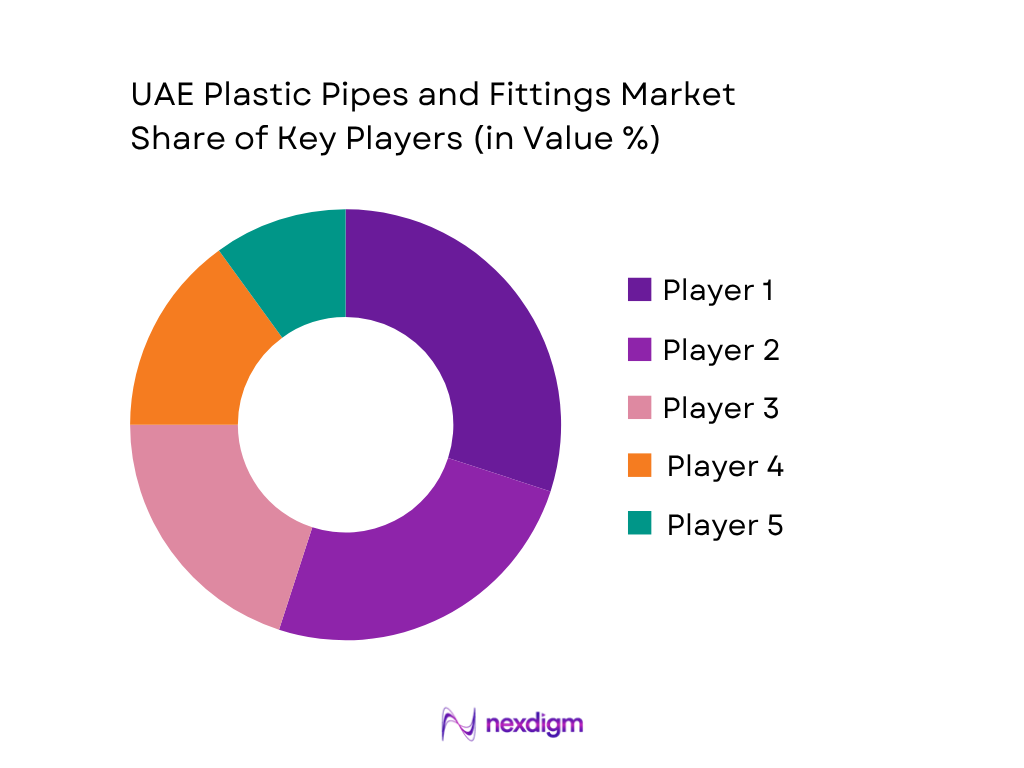
The UAE Plastic Pipes and Fittings Market includes domestic manufacturers, regional suppliers, and international companies supplying advanced piping systems for construction, utilities, industrial, and infrastructure applications. The competitive landscape is influenced by manufacturing capacity, product certification, application expertise, and relationships with contractors, developers, and government utility organizations. Companies such as Future Pipe Industries, Cosmoplast, Interplast, and Hepworth PME maintain strong market presence through diversified product portfolios covering water, wastewater, plumbing, and industrial applications.
| Company | Establishment Year | Headquarters | Product Portfolio | Manufacturing Capability | Key Application Focus | Distribution Network | Certification Coverage |
| Future Pipe Industries | 1984 | Dubai, UAE | ~ | ~ | ~ | ~ | ~ |
| Cosmoplast | 1970 | Dubai, UAE | ~ | ~ | ~ | ~ | ~ |
| Interplast | 1981 | Sharjah, UAE | ~ | ~ | ~ | ~ | ~ |
| Hepworth PME | 1970 | Dubai, UAE | ~ | ~ | ~ | ~ | ~ |
| Harwal Group | 1990 | Dubai, UAE | ~ | ~ | ~ | ~ | ~ |
UAE Plastic Pipes and Fittings Market Analysis
Growth Drivers
Expansion of Water Infrastructure and Desalination Networks Supporting Plastic Pipe Demand
The UAE Plastic Pipes and Fittings Market is significantly supported by continuous development of water infrastructure, desalination facilities, and utility distribution networks due to the country’s limited natural freshwater availability and dependence on treated water systems. The UAE produced approximately 14.2 million cubic meters of desalinated water per day through its desalination infrastructure, according to the UAE Ministry of Energy and Infrastructure, creating extensive requirements for durable HDPE, PVC, and composite piping systems used in water transmission and distribution applications. The country’s population reached approximately 11.0 million people, according to the World Bank, increasing pressure on municipal water networks, residential developments, and utility infrastructure. Dubai Electricity and Water Authority (DEWA) operates thousands of kilometers of water transmission and distribution pipelines, requiring corrosion-resistant piping solutions suitable for desert environments. Abu Dhabi’s water infrastructure expansion through utility networks managed by Abu Dhabi Distribution Company further supports demand for plastic piping systems. The increasing adoption of plastic pipes in desalination plants, potable water networks, wastewater systems, and utility infrastructure is driven by their lightweight properties, resistance to corrosion, and suitability for long-term underground applications.
Growth in Construction Activities and Urban Development Increasing Plumbing System Demand
The UAE Plastic Pipes and Fittings Market benefits from continuous urban development, residential construction, commercial infrastructure expansion, and hospitality sector investments across Dubai, Abu Dhabi, and other emirates. According to the World Bank, the UAE economy maintained strong expansion supported by construction, infrastructure, and non-oil sectors, with GDP reaching approximately USD 537 billion. The UAE’s population exceeded 11 million people, increasing demand for residential communities, commercial buildings, hotels, healthcare facilities, and mixed-use developments requiring advanced plumbing systems. Dubai’s construction pipeline includes large-scale residential and commercial developments requiring PVC, CPVC, and PPR piping solutions for water supply, drainage, and HVAC-related applications. The UAE Ministry of Economy reported continued growth in non-oil economic activities, supporting infrastructure development and building projects. Plastic pipes are increasingly selected in modern construction because they provide corrosion resistance, easier installation, and longer operational life compared with traditional metal alternatives. Expansion of urban infrastructure, real estate development, and sustainable building initiatives is creating additional demand for plastic piping products across residential, commercial, and institutional applications.
Market Challenges
Dependence on Imported Polymer Raw Materials and Global Supply Chain Fluctuations
The UAE Plastic Pipes and Fittings Market faces challenges due to dependence on global polymer supply chains and fluctuations in availability of key raw materials including PVC resin, polyethylene, and polypropylene. Although the UAE has a strong petrochemical industry, plastic pipe manufacturers continue to operate within global polymer pricing and supply dynamics. According to the International Energy Agency, global oil demand remained above 100 million barrels per day, highlighting the continued dependence of petrochemical industries on hydrocarbon feedstocks. The UAE exported approximately 3.7 million barrels per day of crude oil and condensates, according to OPEC statistics, demonstrating the country’s significant role in global energy markets while also reflecting exposure to international commodity cycles. Polymer-based pipe manufacturing requires consistent availability of high-quality resin grades for pressure pipes, potable water applications, and industrial piping systems. Changes in global petrochemical production, logistics conditions, and international supply availability can affect manufacturers’ procurement strategies. These factors create challenges for maintaining stable production schedules and ensuring consistent supply of plastic piping products for infrastructure, construction, and utility projects.
High Competition and Technical Compliance Requirements in Infrastructure Projects
The UAE Plastic Pipes and Fittings Market operates in a competitive environment with manufacturers required to meet strict technical standards for water, construction, industrial, and utility applications. Infrastructure projects in the UAE require compliance with specifications established by organizations such as Dubai Electricity and Water Authority, Abu Dhabi Distribution Company, Dubai Municipality, and Emirates Authority for Standardization and Metrology. The UAE construction sector includes thousands of active contractors and suppliers, increasing competition among piping manufacturers and distributors. According to the UAE Ministry of Economy, the country has more than 1 million registered companies operating across different sectors, contributing to a competitive business environment. Plastic pipe suppliers must differentiate through product certification, manufacturing quality, technical support, and application expertise. Utility projects require pipes capable of handling high-pressure water transmission, underground installations, and demanding environmental conditions. Competition from alternative materials such as ductile iron, steel, and fiberglass piping systems also creates pressure on plastic pipe manufacturers. Maintaining compliance with engineering specifications, improving product reliability, and providing specialized solutions remain important challenges within the market.
Market Opportunities
Development of Smart Water Infrastructure and Sustainable Utility Networks
The UAE Plastic Pipes and Fittings Market has significant opportunities from the modernization of water management systems, smart utility infrastructure, and sustainable urban development initiatives. The UAE continues investing in advanced water management due to its high dependence on desalination and efficient distribution networks. According to the UAE Ministry of Energy and Infrastructure, the country has developed strategic water security programs aimed at improving water storage, distribution efficiency, and infrastructure resilience. Dubai Electricity and Water Authority manages more than 14,000 kilometers of water distribution networks, creating ongoing demand for advanced piping solutions used in utility applications. HDPE and PVC pipes are increasingly suitable for smart water infrastructure due to durability, low maintenance requirements, and compatibility with modern monitoring systems. Expansion of smart cities, automated utility networks, and sustainable infrastructure projects creates opportunities for manufacturers supplying advanced plastic piping systems. Increasing focus on water conservation, wastewater recycling, and efficient distribution networks is expected to support adoption of high-performance plastic pipes across municipal and industrial applications.
Expansion of Wastewater Treatment, District Cooling, and Industrial Infrastructure Applications
The UAE Plastic Pipes and Fittings Market presents growth opportunities through increasing investments in wastewater treatment facilities, district cooling networks, and industrial infrastructure projects. The UAE continues expanding wastewater management capabilities to support urban growth and environmental sustainability. According to the UAE Ministry of Climate Change and Environment, water reuse and sustainable resource management remain important priorities due to increasing urban demand. Dubai operates one of the world’s largest district cooling markets, requiring extensive piping networks for cooling water circulation in residential, commercial, and mixed-use developments. Industrial sectors including manufacturing, energy, and processing facilities require specialized plastic piping systems for chemical resistance, fluid transportation, and operational reliability. According to the World Bank, the UAE’s urban population exceeds 80% of total population, increasing demand for efficient urban infrastructure including wastewater and cooling systems. The adoption of HDPE, PPR, and specialty thermoplastic pipes in industrial and utility applications creates opportunities for manufacturers offering customized solutions. Growth in sustainable infrastructure, industrial diversification, and urban utility modernization will continue supporting demand for plastic pipes and fittings in the UAE.
Future Outlook
Over the next decade, the UAE Plastic Pipes and Fittings Market is expected to witness sustained expansion driven by water infrastructure modernization, urban development, wastewater treatment investments, and increasing adoption of advanced thermoplastic piping systems. Growth will be supported by desalination infrastructure, district cooling networks, industrial expansion, and sustainable construction practices. The market is projected to register a CAGR of approximately XX% during 2026-2035.
Major Players
- Future Pipe Industries
- Cosmoplast
- Interplast
- Hepworth PME
- Harwal Group
- Aalmir Plastic Industries
- National Plastic Factory
- Union Pipes Industry
- Modern Plastic Industry
- Polyfab Plastic Industry
- Ducab Plastic Solutions
- Amiantit Fiberglass Industries
- Al Waha Plastic Factory
- Hotpack Global Plastic Industries
- Tawrid Pipes and Fittings
Key Target Audience
- Plastic Pipe and Fittings Manufacturers
- Water Utility Companies and Infrastructure Operators
- Real Estate Developers and Construction Companies
- Oil and Gas Companies and Industrial Facility Operators
- Building Material Distribution Companies
- Investments and Venture Capitalist Firms (Mubadala Investment Company, Abu Dhabi Investment Authority, Emirates Investment Authority)
- Government and Regulatory Bodies (Dubai Municipality, Dubai Electricity and Water Authority, Abu Dhabi Department of Energy, Abu Dhabi Distribution Company, Emirates Authority for Standardization and Metrology)
- District Cooling and Utility Infrastructure Companies
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves developing an ecosystem map covering polymer suppliers, pipe manufacturers, distributors, contractors, utilities, developers, and end-use industries operating within the UAE Plastic Pipes and Fittings Market. This stage includes extensive desk research using government databases, industry publications, company information, and infrastructure development data to identify major demand factors, supply dynamics, and application-specific variables.
Step 2: Market Analysis and Construction
This phase involves analyzing historical market information related to plastic pipe consumption, material adoption, application demand, and industry structure. Supply-side assessment includes evaluation of manufacturing capabilities, product portfolios, distribution networks, and production technologies. Demand-side analysis covers construction, utilities, irrigation, wastewater, and industrial applications influencing market development.
Step 3: Hypothesis Validation and Expert Consultation
Market assumptions are validated through discussions with manufacturers, distributors, contractors, utility stakeholders, and industry professionals. These consultations provide insights into product preferences, procurement practices, competitive positioning, and application requirements. Expert validation helps refine market estimates and identify key trends affecting the UAE Plastic Pipes and Fittings Market.
Step 4: Research Synthesis and Final Output
The final stage consolidates insights from primary and secondary research to develop a comprehensive market assessment. Data related to segmentation, competitive landscape, regulatory environment, and future opportunities is analyzed and cross-validated to ensure accuracy. The final report provides strategic insights for businesses operating across the UAE plastic piping ecosystem.

- Executive Summary
- Research Methodology (Market Definition and Scope, UAE Plastic Pipes and Fittings Market Classification, Thermoplastic Pipe Demand Assessment, Plastic Pipe Production Volume Analysis, Plastic Fittings Consumption Mapping, PVC Pipe Demand Assessment, HDPE Pipe Consumption Analysis, PPR Plumbing System Adoption Assessment, CPVC Pipe Demand Evaluation, Municipal Water Infrastructure Pipe Requirement Analysis, Desalination Plant Pipeline Demand Assessment, Residential Plumbing Pipe Consumption Mapping, Commercial Construction Plumbing Demand Assessment, Oil and Gas Plastic Pipeline Requirement Analysis, District Cooling Network Pipe Demand Assessment, Irrigation and Landscaping Pipe Requirement Assessment, Wastewater and Sewerage Infrastructure Pipe Requirement Analysis)

- Definition and Scope
- UAE Plastic Pipes and Fittings Industry Evolution and Development of Thermoplastic Piping Infrastructure
- PVC Pressure Pipes, PVC Drainage Pipes, CPVC Pipes, HDPE Pipes, MDPE Pipes, PPR Pipes, PE Pipes, Composite Pipes, Underground Utility Pipes, Irrigation Pipes
- UAE Plastic Pipes and Fittings Value Chain Analysis
- UAE Plastic Pipes and Fittings Supply Chain Analysis
- Plastic Resin Supplier, Polymer Compound Manufacturer, Pipe Extruder, Fittings Manufacturer, Fabricator, Distributor, Contractor, Real Estate Developer, Water Utility End User
- Plastic Pipe Integration Across Desalinated Water Distribution Networks, Residential Plumbing Systems, Commercial Buildings, Industrial Facilities, District Cooling Infrastructure, Oil and Gas Networks, Irrigation Systems, Wastewater Infrastructure, Electrical and Telecom Networks

- Growth Drivers (Expansion of Desalination Water Infrastructure, Residential and Commercial Construction Growth, Government Water Network Development, Increasing HDPE Pipe Adoption for Utility Networks, District Cooling Infrastructure Expansion, Oil and Gas Industry Development, Landscape Irrigation Expansion, Wastewater Infrastructure Modernization, Replacement of Metal Piping Systems, Industrial Facility Development)
- Market Challenges (Dependence on Imported Polymer Raw Materials, Volatility in PVC and Polyethylene Resin Supply, High Competition Among Local and International Manufacturers, Infrastructure Project Specification Requirements, Limited Domestic Polymer Feedstock Availability, Skilled Installation Workforce Requirements, Quality Compliance Requirements, Competition from Steel and Ductile Iron Pipes, Plastic Waste Management Concerns)
- Market Opportunities (Smart Water Infrastructure Development, Expansion of Sustainable Building Projects, Wastewater Treatment Infrastructure Growth, Large Diameter HDPE Pipeline Applications, District Cooling Network Expansion, Industrial Water Management Systems, Advanced Plastic Recycling Solutions, Infrastructure Modernization Projects, Green Building Material Adoption, Advanced Fusion Technology Deployment)
- Market Trends (HDPE Fusion Technology Adoption, Growth of PPR Plumbing Systems, Large Diameter Plastic Pipeline Installation, Smart Utility Network Development, Sustainable Plastic Pipe Manufacturing, Prefabricated Plumbing Systems, BIM-Based Pipe Design Integration, Green Building Certification Requirements, Digital Distribution Expansion)
- Government Regulations and Standards (UAE Standards and Metrology Authority Requirements, Dubai Municipality Plumbing Regulations, Abu Dhabi Water Network Standards, DEWA Water Infrastructure Specifications, ADDC Water Distribution Requirements, UAE Fire and Life Safety Code, Green Building Regulations, Plastic Pipe Certification Standards, Construction Material Compliance Requirements)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Competition Ecosystem

- By Market Value (2020-2025)
- By Plastic Pipe Consumption Volume (2020-2025)
- By Plastic Fittings Consumption Volume (2020-2025)
- By PVC Pipe Consumption Volume (2020-2025)
- By HDPE Pipe Consumption Volume (2020-2025)
- By CPVC Pipe Consumption Volume (2020-2025)
- By PPR Pipe Consumption Volume (2020-2025)

- By Material Type (In Value %)
PVC Pipes and Fittings
CPVC Pipes and Fittings
HDPE Pipes and Fittings
MDPE Pipes and Fittings
PPR Pipes and Fittings
Polyethylene Pipes and Fittings
Composite Plastic Pipes and Fittings
Specialty Thermoplastic Pipes - By Product Type (In Value %)
Pressure Pipes
Non-Pressure Pipes
Potable Water Pipes
Drainage Pipes
Sewerage Pipes
Irrigation Pipes
Corrugated Pipes
Solid Wall Pipes
Flexible Pipes and Tubing
Injection Molded Fittings
Fabricated Fittings
Electrofusion Fittings
Compression Fittings
Mechanical Connection Fittings - By Application Type (In Value %)
Desalinated Water Distribution Systems
Municipal Water Supply Networks
Residential Plumbing Systems
Commercial Building Plumbing Systems
Wastewater and Sewerage Systems
District Cooling Networks
Agricultural Irrigation Systems
Landscape Irrigation Systems
Oil and Gas Utility Applications
Industrial Process Piping Systems
Fire Protection Systems
Electrical Conduit Systems
Telecommunication Duct Systems - By End-Use Industry (In Value %)
Residential Construction Sector
Commercial Real Estate Sector
Water and Utility Authorities
Wastewater Treatment Facilities
Oil and Gas Industry
Industrial Manufacturing Facilities
Hospitality Industry
Agriculture and Landscaping Sector
Healthcare Facilities
Educational Institutions
Government Infrastructure Projects
Telecommunication Infrastructure Sector - By Pipe Diameter (In Value %)
Below 50 mm
50 mm–110 mm
Above 110 mm–315 mm
Above 315 mm–630 mm
Above 630 mm–1000 mm
Above 1000 mm - By Region (In Value %)
Dubai
Abu Dhabi
Sharjah
Ajman
Ras Al Khaimah
Fujairah
Umm Al Quwain

- Market Share of Major Players (By UAE Revenue, Plastic Pipe Sales Volume, Plastic Fittings Sales Volume, PVC Pipe Sales Volume, HDPE Pipe Sales Volume, PPR Pipe Sales Volume, Municipal Infrastructure Exposure, Residential Plumbing Exposure, Manufacturing Footprint, Distribution Network Coverage, Product Portfolio Breadth, Certification Coverage)
- Cross Comparison Parameters (UAE Plastic Pipe and Fittings Revenue, Material Portfolio Breadth Across PVC-HDPE-CPVC-PPR, Pipe Extrusion and Fittings Manufacturing Capacity, Large Diameter Pipe Production Capability, Water Utility Infrastructure Project Exposure, Oil and Gas Application Capability, Distribution Network Reach Across Emirates, UAE Standards and Certification Coverage)
- SWOT Analysis of Major Players
- Competitive Positioning Matrix
- Detailed Profiles of Major Companies
Future Pipe Industries
Cosmoplast
Interplast
Harwal Group
Aalmir Plastic Industries
National Plastic Factory
Union Pipes Industry
Modern Plastic Industry
Hepworth PME
Polyfab Plastic Industry
Ducab Plastic Solutions
Hotpack Global Plastic Industries
Amiantit Fiberglass Industries
Al Waha Plastic Factory
Tawrid Pipes and Fittings

- Water Utility Plastic Pipe Procurement Assessment
- Desalination Plant Pipeline Requirement Analysis
- Residential Developer Plumbing System Material Selection Assessment
- Commercial Building Plumbing Specification Analysis
- District Cooling Network Pipe Requirement Assessment
- Oil and Gas Facility Plastic Piping Requirement Analysis
- Industrial Process Piping Requirement Assessment
- Landscape Irrigation Contractor Procurement Assessment
- Government Infrastructure Project Procurement Analysis
- Plumbing Contractor Material Preference Assessment
- Distributor Inventory and Procurement Assessment
- Architect and Engineering Consultant Plastic Pipe Specification Analysis

- By Market Value (2026-2035)
- By Plastic Pipe Consumption Volume (2026-2035)
- By Plastic Fittings Consumption Volume (2026-2035)
- By PVC Pipe Consumption Volume (2026-2035)
- By HDPE Pipe Consumption Volume (2026-2035)
- By CPVC Pipe Consumption Volume (2026-2035)
- By PPR Pipe Consumption Volume (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
