
 Download PDF
Market Overview
The UK Dump Truck Market is valued at approximately ~USD XX million, supported by construction, quarrying, aggregates, demolition, earthmoving and infrastructure haulage. The latest two annual truck datasets show new HGV registrations moving from 46,227 units to 44,988 units, while rigid-truck registrations increased from 24,439 units to 25,909 units. Construction new-work activity increased from £139,029 million to £140,684 million, sustaining demand for rigid tippers, muckaway vehicles and off-highway articulated haulers.
England dominates the UK Dump Truck Market because it contains the country’s largest concentration of construction projects, roadworks, demolition activity, material movements and HGV fleets. New HGV registrations in England moved from 40,464 units to 39,041 units across the latest two annual datasets, compared with Scotland moving from 3,234 to 3,470 units. Scotland remains strategically important for articulated dump trucks because quarrying, aggregates, earthworks and rugged off-highway applications favour high-traction articulated haulers and heavy construction equipment.
Market Segmentation
By Truck Type
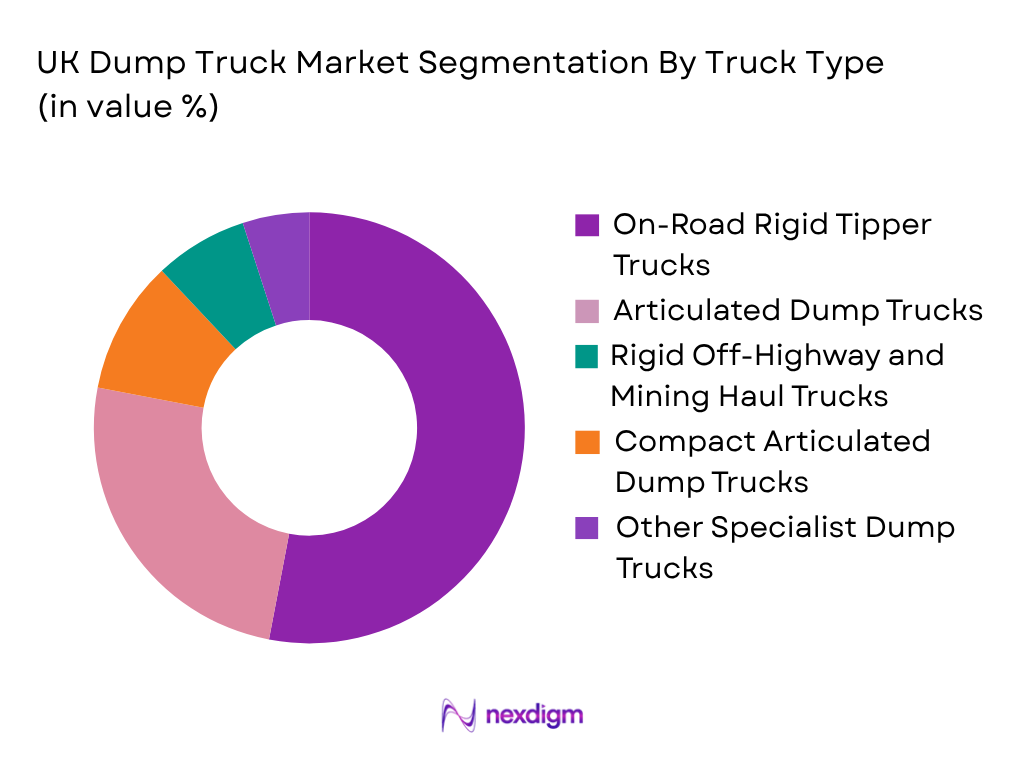
The UK Dump Truck Market is segmented by truck type into on-road rigid tipper trucks, articulated dump trucks, rigid off-highway dump trucks, compact articulated dump trucks and other specialist dump trucks. On-road rigid tipper trucks hold the dominant position because they serve the widest range of UK construction-material movements, including aggregates, asphalt, excavation spoil, demolition waste, sand, gravel and muckaway operations. Their ability to travel legally between depots, quarries and construction sites makes them more versatile than purely off-highway machines. The UK also has a substantial rigid-HGV ecosystem: new rigid HGV registrations reached 25,909 units in 2024, exceeding articulated HGV registrations of 19,079 units. Tippers are particularly concentrated in 6×4 and 8×4 configurations, with 8×4 chassis offering a useful combination of payload, manoeuvrability and road legality. Articulated dump trucks remain critical for quarries, major earthmoving projects and difficult terrain where traction, ground clearance and productivity outweigh public-road flexibility.
By Application Type
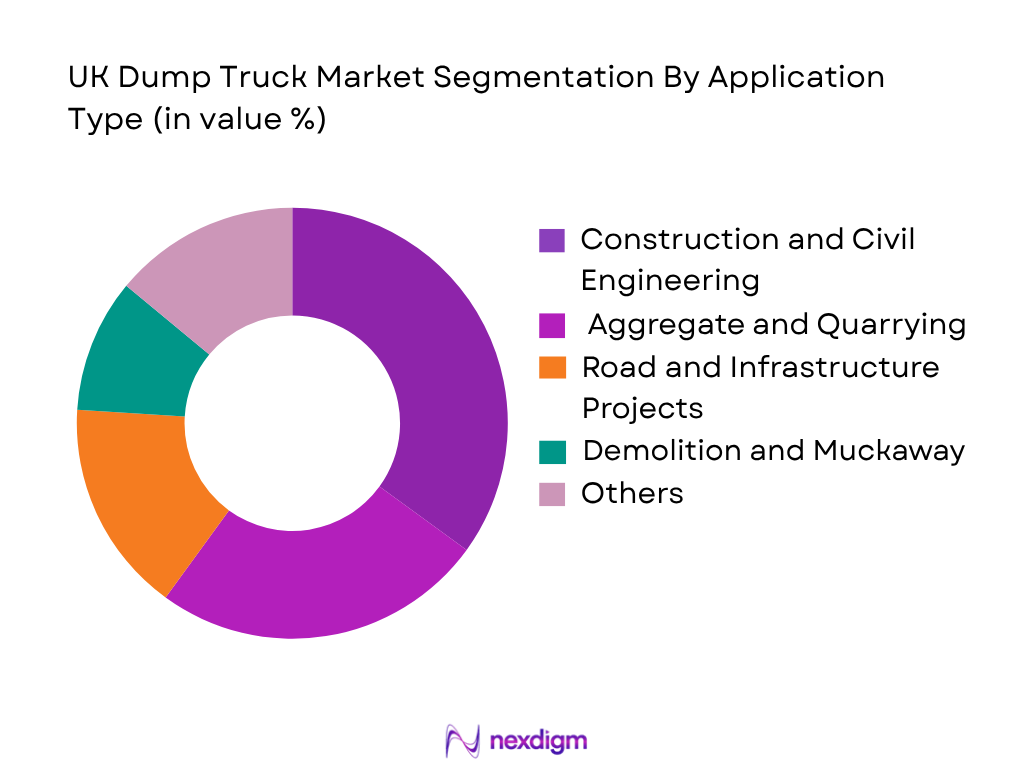
The UK Dump Truck Market is segmented by application into construction and civil engineering, quarrying and aggregates, road and infrastructure projects, demolition and muckaway, waste and recycling, mining and extraction and other specialist applications. Construction and civil engineering represent the dominant application segment because dump trucks are required throughout excavation, ground preparation, earthmoving, aggregate delivery and spoil-removal activities. Great Britain recorded £140,684 million of construction new work in 2024, while annual construction new orders reached £71,707 million. Infrastructure alone generated £33.9 billion of new-work construction activity, creating substantial requirements for bulk-material movement. Quarrying and aggregates form the second major application base because dump trucks continuously transfer blasted rock, sand, gravel, overburden and processed aggregates between working faces, crushers, stockpiles and loading locations. Demand therefore extends from road-going 8×4 tippers working between quarries and projects to articulated haulers operating entirely inside extraction and earthmoving sites.
Competitive Landscape
The UK Dump Truck Market has two intersecting competitive groups. Road-going tipper demand is served by heavy-truck manufacturers such as DAF, Volvo Trucks and Scania, whose chassis are integrated with specialist tipper bodies and hydraulic equipment. Off-highway demand is served by construction-equipment manufacturers such as Caterpillar, Volvo Construction Equipment, Bell Equipment, Rokbak and others. Competition centres on payload productivity, 6×4 and 8×4 availability, off-road traction, bodybuilder compatibility, fleet uptime, safety technology, fuel efficiency, Stage V or Euro VI compliance and dealer support.
| Major Player | Establishment Year | Headquarters | Core Dump-Truck Offering | Key Configuration / Payload Focus | Powertrain Capability | Main UK Applications | Safety & Telematics Capability | UK Service / Support Position |
| DAF Trucks | 1928 | Eindhoven, Netherlands | ~ | ~ | ~ | ~ | ~ | ~ |
| Volvo Trucks | 1928 | Gothenburg, Sweden | ~ | ~ | ~ | ~ | ~ | ~ |
| Scania | 1891 | Södertälje, Sweden | ~ | ~ | ~ | ~ | ~ | ~ |
| Caterpillar | 1925 | Irving, Texas, USA | ~ | ~ | ~ | ~ | ~ | ~ |
| Bell Equipment | 1954 | Richards Bay, South Africa | ~ | ~ | ~ | ~ | ~ | ~ |
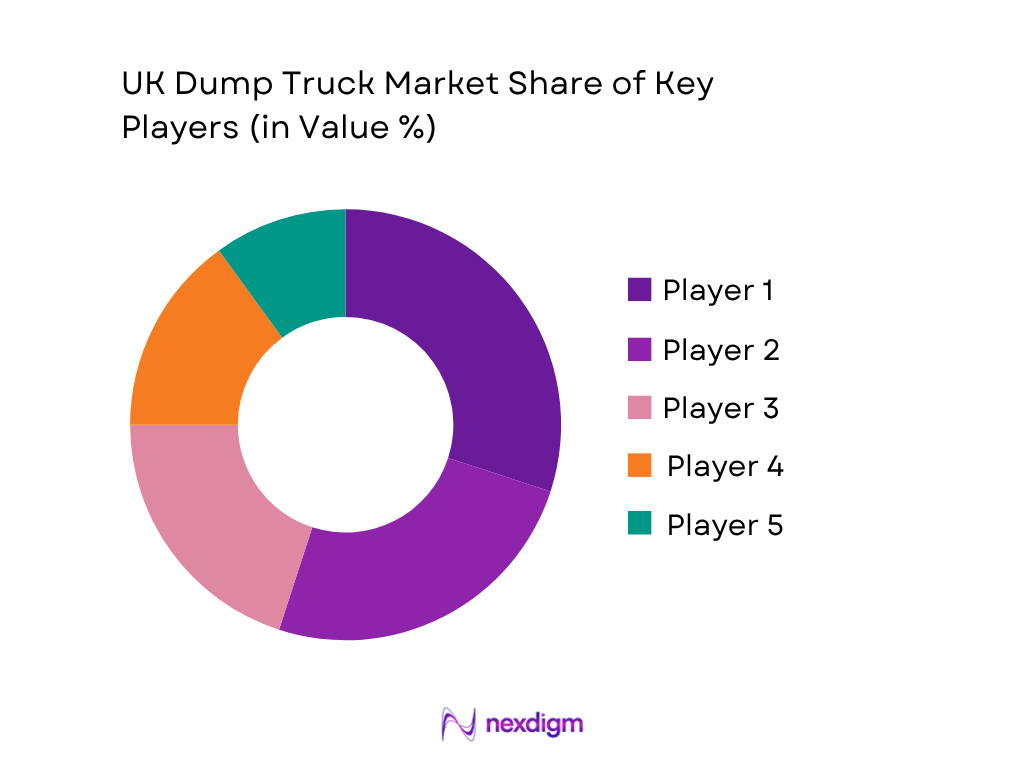
UK Dump Truck Market Analysis
Growth Drivers
Large Construction and Civil Engineering Workload Sustains Demand for Heavy Tippers
The UK’s substantial construction workload is a core growth driver for the UK Dump Truck Market because earthmoving, excavation, muckaway, aggregate delivery and site preparation require continuous deployment of rigid tippers and off-highway haulers. The Office for National Statistics recorded £140,684 million of construction new work in Great Britain in 2024, an increase of £1,904 million from the preceding year. Public-sector new work added £2,592 million, while public new housing alone contributed an additional £3,826 million. Infrastructure construction represented another major demand pool, with the Office for National Statistics recording £33.9 billion of infrastructure new work in 2024. These projects require high-capacity 6×4 and 8×4 tippers for excavated material, aggregates and asphalt, together with articulated dump trucks for inaccessible or unfinished terrain. The broader economic environment supports the scale of this activity: World Bank data place UK GDP at exactly USD 3,686.03 billion in 2024, with GDP per capita at USD 53,246.4. Combined construction volumes and a large national economy provide a substantial operating base for dump-truck manufacturers, bodybuilders, plant-hire companies, quarry fleets and specialist construction-haulage operators.
High Aggregate Production Creates Continuous Quarry and Material-Haulage Requirements
The scale of UK aggregate production directly supports the UK Dump Truck Market because quarried rock, sand and gravel require repeated movement between extraction faces, crushers, screening facilities, stockpiles and final loading points. The Mineral Products Association, drawing on British Geological Survey and Crown Estate data, recorded 186.3 million tonnes of primary aggregates production in 2024, comprising 132.2 million tonnes of crushed rock and 54.1 million tonnes of sand and gravel. Regional crushed-rock production included 27.0 million tonnes in the East Midlands, 26.3 million tonnes across southern regions, 22.9 million tonnes in Northern Ireland, 18.9 million tonnes in Scotland and 12.8 million tonnes in Wales. Great Britain additionally supplied 74.7 million tonnes of recycled and secondary aggregates, creating further haulage requirements around demolition, recycling and construction sites. These tonnages are particularly suited to high-payload articulated dump trucks and 8×4 road tippers because productivity depends on tonnes moved per operating cycle. The World Bank recorded UK GDP at USD 3,686.03 billion in 2024 and GDP per capita at USD 53,246.4, reinforcing the substantial industrial and construction economy supporting quarry-equipment utilisation and replacement activity.
Market Challenges
Construction and Infrastructure Volatility Creates Uneven Dump Truck Utilisation
Construction-cycle volatility remains a major challenge for the UK Dump Truck Market because dump trucks generate economic value only when high utilisation can be maintained across earthmoving, infrastructure, quarry and materials-handling projects. Although the Office for National Statistics recorded £140,684 million of total construction new work in 2024, infrastructure new work stood at £33.9 billion, with lower activity in several material-intensive categories including roads, railways, sewerage infrastructure and harbours. The same ONS dataset shows that public infrastructure construction declined by £2,178 million, while private new housing declined by £1,421 million. These reductions directly affect demand for muckaway tippers, aggregate carriers and articulated haulers because fewer excavation and civil-engineering work packages mean fewer operating hours and weaker fleet utilisation. The wider truck market also illustrates fleet-cycle sensitivity: Department for Transport administrative statistics recorded approximately 51,000 newly registered HGVs in 2024, while registrations declined to approximately 47,000 in 2025. Against this operating backdrop, World Bank data recorded UK GDP of USD 3,686.03 billion in 2024 and GDP per capita of USD 53,246.4. Dump-truck suppliers therefore face project timing risk despite operating within a large and diversified economy.
Transition from Diesel to Zero-Emission Heavy Trucks Creates Fleet and Infrastructure Complexity
Decarbonisation presents a significant challenge for the UK Dump Truck Market because heavy construction tippers combine high payloads, hydraulic power requirements, extended operating hours and irregular access to charging infrastructure. Department for Transport data recorded approximately 534,000 licensed HGVs in 2024, while only 990 licensed HGVs were zero-emission vehicles, illustrating the considerable technological transition still required across the heavy-vehicle parc. Administrative vehicle-registration statistics show 520,000 licensed road-using HGVs in 2025, while only around 1,000 road-using HGVs were zero emission. New zero-emission HGV registrations reached 632 units in 2025, compared with a total of approximately 47,000 newly registered HGVs. Dump trucks face additional complexity because construction sites, quarries and demolition projects often operate away from established depot charging infrastructure, while payload capacity can be affected by the mass of energy-storage systems. Heavy-duty electric equipment must also support tipping hydraulics, traction on loose surfaces and repetitive loaded cycles. The broader economic backdrop remains substantial, with the World Bank recording UK GDP at USD 3,686.03 billion in 2024 and GDP per capita of USD 53,246.4, highlighting that infrastructure readiness rather than economic scale remains a key constraint.
Market Opportunities
Large Existing HGV Fleet Creates Future Replacement and Specialist Tipper Conversion Opportunities
The scale of the existing heavy-truck parc provides a significant future opportunity for the UK Dump Truck Market because fleet replacement continually creates demand for new chassis, tipper bodies, hydraulic systems, weighing equipment and construction-specific safety technology. Department for Transport administrative records show approximately 534,000 licensed HGVs in 2024 and 520,000 licensed road-using HGVs in 2025. Around 51,000 HGVs were newly registered in 2024, followed by approximately 47,000 in 2025, demonstrating substantial annual fleet renewal even as overall truck demand fluctuated. Within the heavy-truck market, SMMT recorded 25,909 new rigid-truck registrations in 2024, including 16,805 rigid vehicles above 16 tonnes, an important chassis pool for construction applications such as 6×4 and 8×4 tippers. In 2025, another 22,250 rigid trucks entered the market, including 14,717 units above 16 tonnes. Replacement cycles allow operators to adopt lighter tipper bodies, onboard weighing, improved visibility systems and connected fleet technology. World Bank data place UK GDP at USD 3,686.03 billion in 2024, with GDP per capita at USD 53,246.4, supporting continued investment in productive commercial equipment and specialised vehicle conversion capabilities.
Electrified Quarry and Controlled-Site Haulage Creates a New Equipment Growth Path
Electrification of controlled construction and quarry sites represents an important future opportunity for the UK Dump Truck Market because repetitive haul routes are better suited to planned charging than long-distance road freight. Current fleet statistics demonstrate both the size of the addressable transition and the early stage of adoption. The Department for Transport recorded approximately 520,000 licensed road-using HGVs in 2025, while new road-using zero-emission HGV registrations reached 632 units during the year. The equipment opportunity is reinforced by the physical scale of UK material handling: industry data based on British Geological Survey, Crown Estate and sector records show 186.3 million tonnes of primary aggregates were produced in 2024, including 132.2 million tonnes of crushed rock and 54.1 million tonnes of sand and gravel. These materials are frequently transported over repetitive quarry routes, where charging infrastructure can be located close to loading and dumping areas. Electrified articulated haulers can therefore target operations characterised by predictable distances, controlled access and frequent cycles. The macroeconomic environment remains supportive of technology investment, with the World Bank recording UK GDP at USD 3,686.03 billion in 2024 and GDP per capita at USD 53,246.4. This creates scope for electric haulers, charging systems, battery servicing and energy-management solutions.
Future Outlook
The UK Dump Truck Market is forecast to expand at approximately ~X.X% CAGR during 2026–2035, with development increasingly driven by infrastructure renewal, quarry productivity, fleet replacement and the gradual introduction of low-emission heavy equipment. The market will remain divided between road-going rigid tippers and off-highway articulated haulers, requiring different product, dealer and fleet strategies. Rigid tippers are expected to retain their importance because UK construction logistics depend heavily on vehicles capable of carrying aggregates, asphalt, demolition waste and excavated material between sites through the public-road network. The 8×4 configuration is particularly suited to payload-intensive operations where operators need high carrying capability while preserving manoeuvrability and legal road access.
The articulated dump truck segment will develop around quarrying, major earthmoving and infrastructure projects. Articulated haulers provide superior traction on loose, uneven or steep ground and can operate in conditions where conventional rigid road tippers are unsuitable. Equipment selection will increasingly incorporate cycle time, tonnes moved per hour, payload accuracy, fuel or electricity consumption and site-specific haul-road design.
Major Players
- DAF Trucks Ltd. – XBC / XDC / XFC Construction Tippers / 6×4 and 8×4 Rigid Applications
- Volvo Trucks UK Ltd. – FMX Construction Tippers / 6×4 and 8×4 Heavy-Duty Applications
- Scania Great Britain Ltd. – P-Series / G-Series / XT Construction Tippers / Multi-Axle Applications
- Mercedes-Benz Trucks UK Ltd. – Arocs Construction Tippers / 6×4 and 8×4 Heavy Construction Applications
- MAN Truck & Bus UK Ltd. – TGS Construction Tippers / Multi-Axle Heavy-Duty Applications
- Renault Trucks UK Ltd. – K Range / C Range Construction Tippers / Quarry and Muckaway Applications
- IVECO Ltd. – X-Way / T-Way Tippers / On-Road and Off-Road Construction Applications
- Volvo Construction Equipment – A-Series Articulated Haulers / Quarry / Earthmoving / Electric Haulers
- Caterpillar Inc. – Articulated Trucks / Rigid Dump Trucks / Quarry and Heavy Earthmoving Applications
- Komatsu Ltd. – Articulated Dump Trucks / Rigid Dump Trucks / Quarry and Mining Applications
- Bell Equipment Ltd. – E-Series Articulated Dump Trucks / Quarry / Earthmoving / Heavy Haul Applications
- Rokbak Ltd. – RA30 / RA40 Articulated Haulers / UK-Manufactured Quarry and Construction Equipment
- Hydrema A/S – Compact Articulated Dump Trucks / Low-Ground-Pressure / Electric Dump Trucks
- DEVELON – Articulated Dump Trucks / Quarry / Construction / Earthmoving Applications
- Liebherr Group – Dump Truck Solutions / Heavy Earthmoving / Quarry and Extraction Applications
Key Target Audience
- Dump Truck and Heavy Commercial Vehicle Manufacturers
- Construction Equipment and Articulated Hauler Manufacturers
- Tipper Bodybuilders and Hydraulic Equipment Suppliers
- Construction Quarrying and Aggregate Operators
- Plant Hire Fleet Rental and Heavy Equipment Leasing Companies
- Heavy Commercial Vehicle Dealers and Aftermarket Service Networks
- Investments and Venture Capitalist Firms
- Government and Regulatory Bodies (Department for Transport, Driver and Vehicle Standards Agency, Vehicle Certification Agency, Health and Safety Executive, Transport for London)
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves constructing an ecosystem map of the UK Dump Truck Market covering truck manufacturers, off-highway equipment OEMs, tipper bodybuilders, dealers, construction contractors, quarry operators, plant-hire companies and fleet operators. Key variables include truck type, payload, GVW, axle configuration, application, fleet size, replacement cycle, rental penetration and propulsion technology.
Step 2: Market Analysis and Construction
Historical market development is assessed through HGV registrations, construction activity, quarry and aggregate demand, infrastructure activity and equipment replacement patterns. Top-down analysis is reconciled with bottom-up assessment of road-tipper registrations, articulated dump truck placements, typical fleet replacement cycles, bodybuilder activity and application-level demand to establish a consistent market structure.
Step 3: Hypothesis Validation and Expert Consultation
Market hypotheses are validated through computer-assisted telephone interviews with dump-truck dealers, fleet managers, construction contractors, quarry operators, plant-hire companies, bodybuilders and equipment service providers. Interviews examine payload requirements, 6×4 versus 8×4 preferences, articulated-hauler utilisation, procurement cycles, rental behaviour, fleet uptime, safety requirements and adoption barriers for electric equipment.
Step 4: Research Synthesis and Final Output
The final phase triangulates registration data, construction-sector indicators, dealer intelligence, fleet procurement patterns and application-level equipment requirements. Road-going rigid tippers are evaluated separately from off-highway articulated and rigid dump trucks before being consolidated into the overall market framework, ensuring that fundamentally different operating environments and replacement cycles are appropriately represented.

- Executive Summary
- Research Methodology (Market Definition and Scope, UK Dump Truck Taxonomy, On-Road Rigid Tipper and Off-Highway Dump Truck Classification, Articulated Dump Truck Mapping, Vehicle Registration Assessment, Construction and Quarry Equipment Fleet Assessment, Payload and GVW Mapping, Fleet Replacement Assessment, Plant Hire and Rental Fleet Mapping, Tipper Bodybuilder Assessment, Dealer and Service Network Assessment, Market Sizing Framework)

- Definition and Scope
- UK Dump Truck Industry Evolution and Construction Haulage Development
- Dump Truck Manufacturing and Assembly Process
- Dump Truck Value Chain Analysis
- UK Dump Truck Supply Chain Analysis
- Chassis, Cab, Engine, Transmission, Axle, Hydraulic Tipping Gear, Tipper Body and Tyre Ecosystem Analysis
- UK Dump Truck Assembly, Bodybuilding, Dealer and Rental Footprint Assessment
- OEM, Bodybuilder, Dealer, Plant Hire, Fleet Operator and Aftermarket Framework

- Growth Drivers (Infrastructure and Civil Engineering Activity, Quarry and Aggregate Haulage Demand, Replacement of Ageing Tipper Fleets, High Utilisation of 8×4 Construction Tippers, Plant Hire and Rental Demand, Major Earthmoving Projects, Fleet Safety Modernisation, Demand for Higher Payload Productivity)
- Market Challenges (Construction Cycle Dependence, Seasonal and Project-Based Equipment Utilisation, Skilled HGV and Plant Operator Availability, High Fuel and Maintenance Intensity, Heavy Vehicle Safety Compliance, Diesel Fleet Decarbonisation Pressure, Residual Value Risk, High-Capacity Equipment Utilisation Constraints)
- Market Opportunities (Battery-Electric Articulated Haulers, Low-Emission Urban Construction Tippers, High-Payload Lightweight Tipper Bodies, Fleet Telematics and Payload Monitoring, Dump Truck Rental Fleet Expansion, Remanufactured Components and Used Equipment, Quarry Fleet Automation, Operator-Assistance Systems)
- Market Trends (8×4 Rigid Tipper Adoption, High-Strength Lightweight Tipper Bodies, On-Board Payload Weighing, Automatic Traction Control, Articulated Hauler Telematics, Camera-Based Visibility Systems, Predictive Maintenance, Battery-Electric Hauling)
- Regulatory and Standards Landscape (Driver and Vehicle Standards Agency Heavy Vehicle Requirements, Vehicle Certification Agency Type Approval, Euro VI Road Vehicle Emission Requirements, Stage V Non-Road Mobile Machinery Requirements, Transport for London Direct Vision Standard, Progressive Safe System Requirements, HGV Safety Permit Requirements, Construction and Use Regulations, Operator Licensing Requirements, PUWER and LOLER Requirements)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Competition Ecosystem

- By Market Value (2020-2025)
- By New Dump Truck and Tipper Volume (2020-2025)
- By Replacement Dump Truck Volume (2020-2025)
- By On-Road Rigid Tipper Volume (2020-2025)
- By Articulated Dump Truck Volume (2020-2025)
- By Heavy Construction and Quarry Dump Truck Volume (2020-2025)

- By Truck Type (In Value %)
On-Road Rigid Tipper Trucks
Articulated Dump Trucks
Rigid Off-Highway Dump Trucks
Compact Articulated Dump Trucks
Construction-Specification Tippers
Heavy-Duty Quarry Tippers
Mining and Extraction Dump Trucks
Electric Dump Trucks
Special-Purpose Dump Trucks - By Payload and GVW Class (In Value %)
Below 10-Tonne Payload
10-Tonne to 20-Tonne Payload
Above 20-Tonne to 30-Tonne Payload
Above 30-Tonne to 40-Tonne Payload
Above 40-Tonne Payload
18-Tonne GVW Road Tippers
26-Tonne GVW Road Tippers
32-Tonne GVW Road Tippers
Heavy Off-Highway Payload Classes - By Axle and Drive Configuration (In Value %)
4×2 Tippers
4×4 Tippers
6×4 Tippers
6×6 Tippers
8×4 Tippers
8×4 Tridem Tippers
8×8 Heavy-Duty Tippers
Three-Axle Articulated Dump Trucks
Other Multi-Axle Configurations - By Application Type (In Value %)
Residential and Commercial Construction
Road and Highway Construction
Civil Engineering and Infrastructure
Quarrying and Aggregates
Sand, Gravel and Mineral Products
Earthmoving and Site Preparation
Mining and Extraction
Demolition and Muckaway
Waste and Recycling
Utilities and Groundworks
Rail Infrastructure
Tunnelling and Major Projects - By Propulsion Type (In Value %)
Euro VI Diesel Road Tippers
Stage V Diesel Articulated Dump Trucks
Stage V Diesel Rigid Off-Highway Dump Trucks
Battery-Electric Dump Trucks
Battery-Electric Articulated Haulers
Hybrid and Electrically Assisted Dump Trucks
HVO-Compatible Dump Trucks
Other Alternative-Fuel Dump Trucks - By Ownership and Procurement Model (In Value %)
Construction Contractor Direct Ownership
Quarry and Aggregate Operator Ownership
Fleet Operator Ownership
Plant Hire and Rental
Long-Term Contract Hire
Finance Lease and Hire Purchase
Short-Term Project Rental
Used Dump Truck Procurement
Government and Municipal Procurement - By Region (In Value %)
London
South East England
South West England
East of England
East Midlands
West Midlands
North West England
North East England
Yorkshire and the Humber
Scotland
Wales
Northern Ireland

- Market Share of Major Players (By Revenue, Truck Type, Payload Class, Application, Propulsion Type, Fleet Ownership Model, Region, Rental Fleet Presence)
- Cross Comparison Parameters (UK Road Tipper and Off-Highway Dump Truck Portfolio Breadth, Payload GVW and 6×4 8×4 Articulated Configuration Coverage, Construction Quarry Mining Waste and Infrastructure Application Coverage, Euro VI Stage V Diesel and Severe-Duty Powertrain Capability, Battery-Electric and Low-Emission Dump Truck Readiness, UK Dealer Rental Parts Uptime and Technical Support Network, Tipper Bodybuilder Integration Payload Optimisation and Hydraulic System Capability, Direct Vision Progressive Safe System Telematics and Operator-Assistance Capability)
- SWOT Analysis of Major Players
- Competitive Positioning Matrix
- Pricing and Distribution Network Benchmarking
- Detailed Profiles of Major Companies
DAF Trucks Ltd. – XBC / XDC / XFC Construction Tippers / 6×4 and 8×4 Rigid Applications
Volvo Trucks UK Ltd. – FMX Construction Tippers / 6×4 and 8×4 Heavy-Duty Applications
Scania Great Britain Ltd. – P-Series / G-Series / XT Construction Tippers / Multi-Axle Applications
Mercedes-Benz Trucks UK Ltd. – Arocs Construction Tippers / 6×4 and 8×4 Heavy Construction Applications
MAN Truck & Bus UK Ltd. – TGS Construction Tippers / Multi-Axle Heavy-Duty Applications
Renault Trucks UK Ltd. – K Range / C Range Construction Tippers / Quarry and Muckaway Applications
IVECO Ltd. – X-Way / T-Way Tippers / On-Road and Off-Road Construction Applications
Volvo Construction Equipment – A-Series Articulated Haulers / Quarry / Earthmoving / Electric Haulers
Caterpillar Inc. – Articulated Trucks / Rigid Dump Trucks / Quarry and Heavy Earthmoving Applications
Komatsu Ltd. – Articulated Dump Trucks / Rigid Dump Trucks / Quarry and Mining Applications
Bell Equipment Ltd. – E-Series Articulated Dump Trucks / Quarry / Earthmoving / Heavy Haul Applications
Rokbak Ltd. – RA30 / RA40 Articulated Haulers / UK-Manufactured Quarry and Construction Equipment
Hydrema A/S – Compact Articulated Dump Trucks / Low-Ground-Pressure / Electric Dump Trucks
DEVELON – Articulated Dump Trucks / Quarry / Construction / Earthmoving Applications
Liebherr Group – Dump Truck Solutions / Heavy Earthmoving / Quarry and Extraction Applications

- Dump Truck Buyer Segmentation
- Construction Contractor and Quarry Operator Procurement Behaviour
- Dump Truck Supplier and Dealer Selection Criteria
- Fleet Operator and Plant Hire Pain Points
- Payload, Uptime and Electrification Adoption Assessment
- Replacement and Repurchase Behaviour

- By Market Value (2026-2035)
- By New Dump Truck and Tipper Volume (2026-2035)
- By Replacement Dump Truck Volume (2026-2035)
- By On-Road Rigid Tipper Volume (2026-2035)
- By Articulated Dump Truck Volume (2026-2035)
- By Heavy Construction and Quarry Dump Truck Volume (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
