
 Download PDF
Market Overview
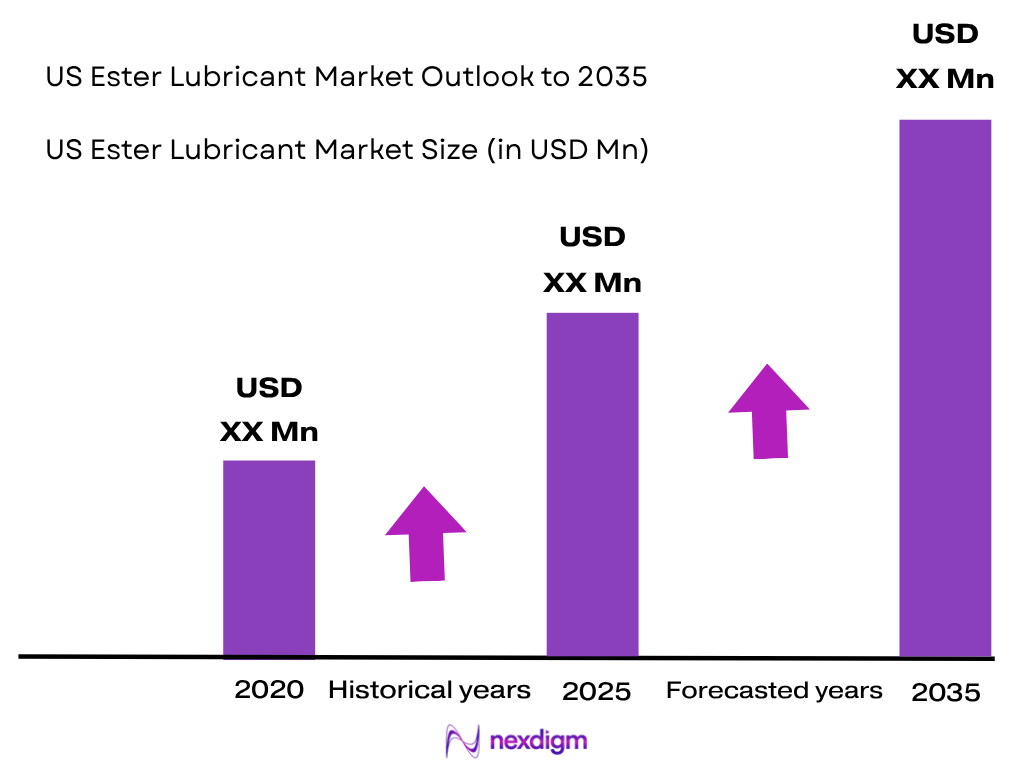
The US Ester Lubricant Market is positioned within the broader synthetic and specialty lubricant ecosystem, where ester base stocks are used when lubricants require high lubricity, thermal stability, low volatility, solvency and performance across demanding operating conditions. The 2024 market size is represented as ~USD XX million, while the forecast CAGR for 2026-2035 is ~XX.X% as a placeholder for report development. Demand is supported by the scale of US lubricant consumption: EIA reports that the United States consumed 20.3 million barrels per day of petroleum products in 2024, including lubricants within its “other” petroleum-products category. The US manufacturing ecosystem provides another major demand base, with 2024 manufacturing sales, shipments and revenue reaching USD 6.98 trillion and employment reaching 12.01 million, creating a substantial installed base of machinery, automotive equipment and industrial systems requiring lubrication.
The US Ester Lubricant Market benefits from extensive automotive, aerospace and industrial equipment activity, with demand increasingly linked to applications requiring specialized lubricant performance rather than conventional lubrication alone. The automotive aftermarket remains significant, with the Bureau of Labor Statistics reporting approximately 81,800 workers in automotive oil-change and lubrication shops and related automotive repair activities in December 2024. Aerospace represents another technically important application because ester-based lubricants are used in demanding aviation environments; the Federal Aviation Administration’s 2024 activity survey tracks active aircraft, flight hours and fuel consumption across general aviation and Part 135 operations. Meanwhile, US electric-car sales reached 1.6 million units in 2024, expanding the requirement for specialized fluids and thermal-management technologies while gradually changing conventional engine-oil demand patterns.
Market Segmentation
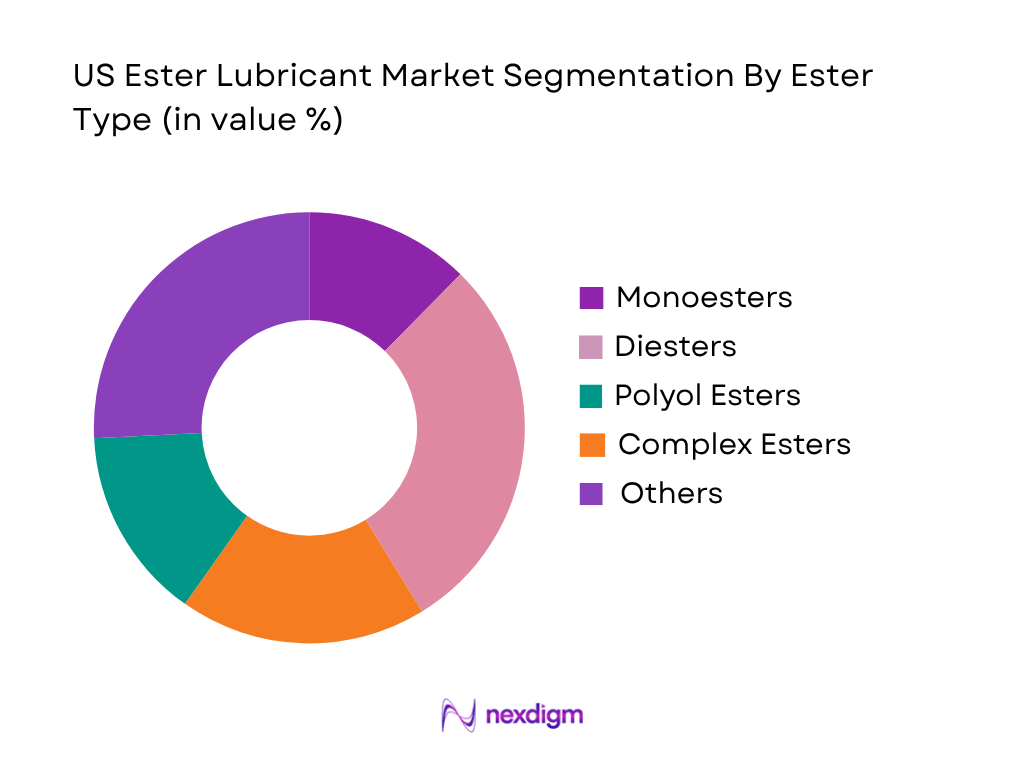
By Ester Type
The US Ester Lubricant Market is segmented by ester type into monoesters, diesters, polyol esters, complex esters, trimellitate esters, phosphate esters, neopolyol esters and other specialty esters. Polyol esters represent the key high-performance sub-segment because their molecular structure enables strong thermal stability, low volatility and effective lubrication under demanding temperature conditions. These characteristics make them particularly relevant to aerospace, aviation, refrigeration, compressor, turbine and specialized industrial applications. Polyol esters can also provide favorable solvency and compatibility characteristics in formulated lubricant systems, allowing formulators to optimize additive response and deposit control. Diesters remain important in applications where good low-temperature characteristics, lubricity and solvency are required, while monoesters are frequently used as blending components and performance enhancers. Complex esters offer formulators additional flexibility where customized viscosity-temperature and oxidative-performance characteristics are required. The US market’s large aerospace and industrial equipment base supports specialty ester consumption, while the continued development of high-performance lubricants creates opportunities for ester chemistries that provide performance advantages over conventional mineral-base formulations.
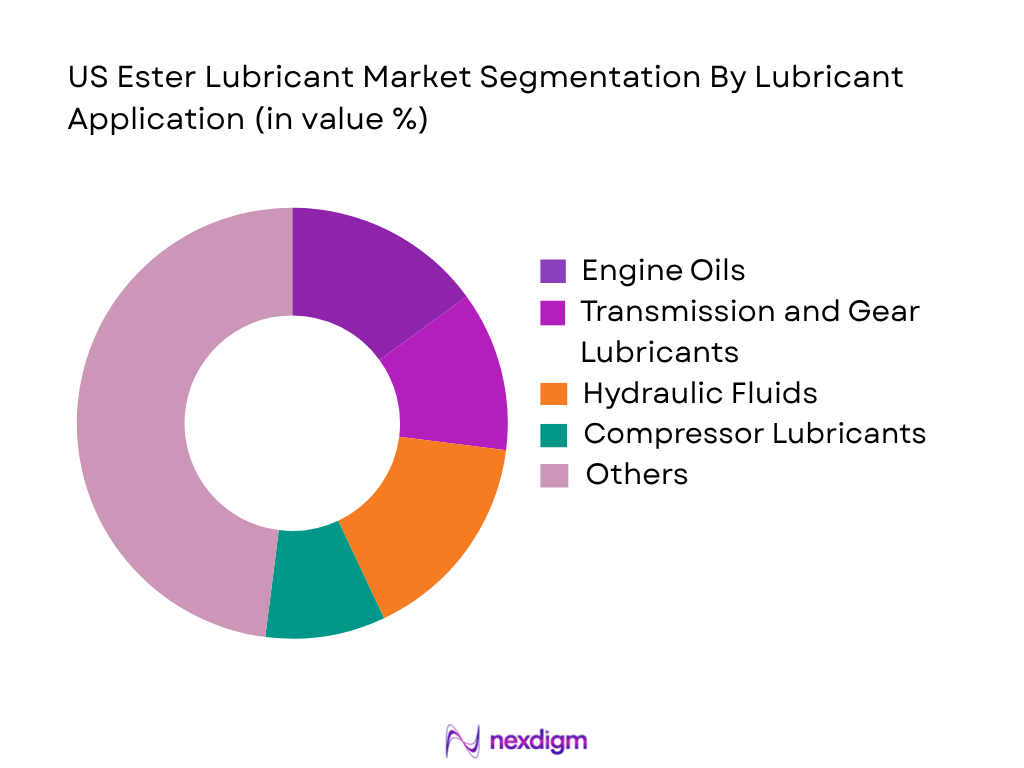
By Lubricant Application
The US Ester Lubricant Market is segmented by lubricant application into engine oils, transmission and gear lubricants, hydraulic fluids, compressor lubricants, turbine lubricants, metalworking fluids, greases, aerospace lubricants, marine lubricants and refrigeration lubricants. Aerospace lubricants represent a particularly important specialty application because aviation systems require fluids capable of maintaining lubrication performance across wide temperature ranges, high rotational speeds and demanding operating environments. Ester chemistry has a long-established role in aviation lubrication because of its combination of thermal performance, lubricity and volatility characteristics. The breadth of US aviation activity supports this application: the FAA maintains dedicated 2024 datasets covering active aircraft, total flight hours, aircraft utilization and fuel consumption. Industrial applications provide another substantial demand base, particularly metalworking, compressors, turbines and hydraulic equipment. US manufacturing recorded USD 6.98 trillion in 2024 sales, shipments and revenue and employed 12.01 million people, indicating the scale of the machinery ecosystem requiring industrial lubrication.
Competitive Landscape
The US Ester Lubricant Market comprises diversified specialty-chemical companies, lubricant additive suppliers, ester manufacturers and lubricant formulators serving automotive, aerospace, industrial and environmentally sensitive applications. Competition is differentiated by ester chemistry breadth, base-stock manufacturing capabilities, formulation expertise, technical service, OEM approvals and distribution reach. Major participants include ExxonMobil, BASF, Croda, Emery Oleochemicals and Afton Chemical, alongside other specialty ester and lubricant suppliers. Their competitive positioning is influenced by their ability to provide application-specific formulations, maintain consistent base-stock quality and support qualification requirements for demanding industrial and aerospace customers.
| Company | Establishment Year | Headquarters | Ester Base Stock Portfolio | Aerospace Applications | Automotive Applications | Industrial Lubricants | Bio-Based Ester Capability | Technical Support | Distribution Reach |
| ExxonMobil | 1999 | Spring, Texas, US | ~ | ~ | ~ | ~ | ~ | ~ | ~ |
| BASF | 1865 | Ludwigshafen, Germany | ~ | ~ | ~ | ~ | ~ | ~ | ~ |
| Croda | 1925 | Snaith, UK | ~ | ~ | ~ | ~ | ~ | ~ | ~ |
| Emery Oleochemicals | 1840 | Cincinnati, Ohio, US | ~ | ~ | ~ | ~ | ~ | ~ | ~ |
| Afton Chemical | 1887 | Richmond, Virginia, US | ~ | ~ | ~ | ~ | ~ | ~ | ~ |
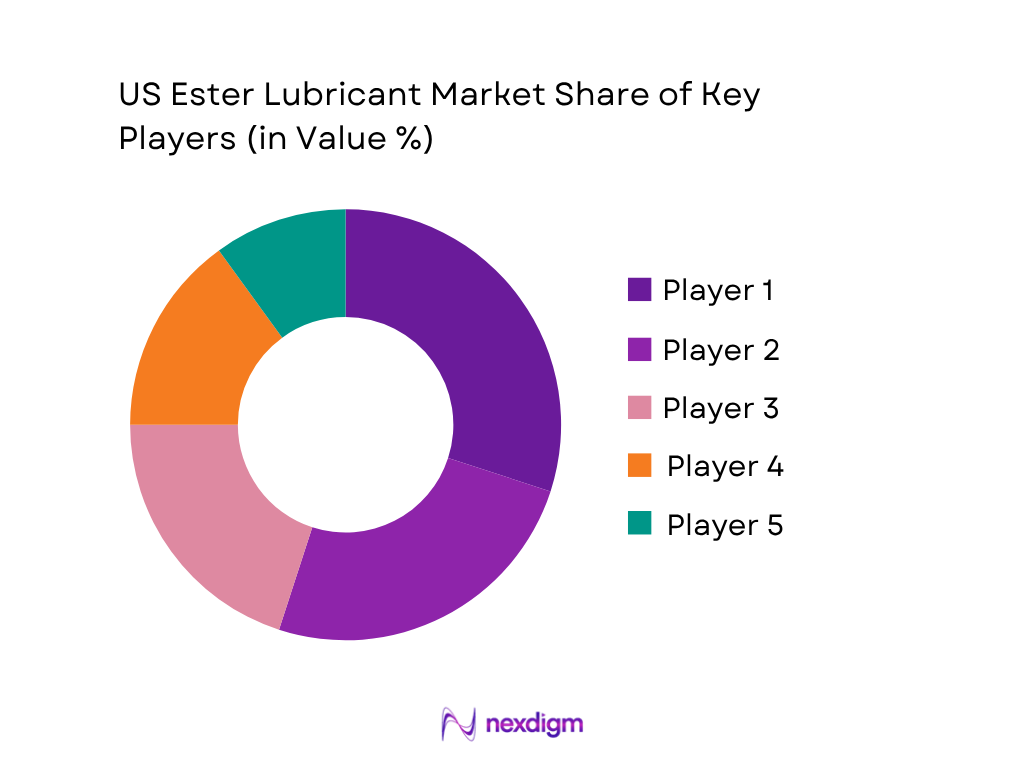
US Ester Lubricant Market Analysis
Growth Drivers
Expansion of Aerospace and High-Performance Industrial Applications
The US Ester Lubricant Market is supported by increasing demand from aerospace, industrial machinery and high-performance equipment applications where conventional mineral lubricants may not provide sufficient thermal stability, oxidation resistance and operating reliability. The aerospace sector remains a critical consumption area for ester-based lubricants due to their ability to perform under extreme temperature variations and high mechanical stress conditions. The Federal Aviation Administration reported that the US civil aviation ecosystem maintained a significant operational base with more than 204,000 active general aviation aircraft operations tracked annually and continued monitoring of flight activity across commercial and general aviation segments. The industrial equipment ecosystem further strengthens demand, as the US manufacturing sector recorded USD 6.98 trillion in total value of shipments, sales and revenue in 2024, with 12.01 million employees engaged across manufacturing industries. The presence of extensive machinery fleets in metalworking, automotive production, chemical processing and power-generation facilities creates recurring requirements for specialty lubricants. Ester lubricants are increasingly preferred in applications requiring improved lubrication efficiency, reduced volatility and extended operating performance, supporting their adoption across aerospace components, compressors, turbines, hydraulic systems and specialized manufacturing equipment.
Growth of Electric Vehicles and Advanced Mobility Lubrication Requirements
The transformation of the US automotive industry toward electrification is creating demand for advanced lubricant technologies, including ester-based fluids used in thermal management systems, electric driveline components, specialized greases and high-performance automotive applications. The International Energy Agency reported that US electric car sales reached approximately 1.6 million units in 2024, reflecting continued expansion of electrified mobility and increasing requirements for specialized fluid technologies. The automotive manufacturing ecosystem remains a major contributor to lubricant demand, with the United States producing approximately 10.6 million light vehicles in 2024, according to automotive production statistics. The transition toward electric vehicles requires lubricants capable of supporting new operating conditions, including higher electrical compatibility requirements, improved heat transfer performance and reduced friction losses. Ester-based formulations provide advantages such as strong lubricity, biodegradability potential and thermal performance, making them relevant for next-generation mobility applications. In addition, the growing adoption of advanced transmissions, hybrid systems and performance vehicles is increasing demand for specialty lubricant formulations beyond traditional engine oils. These developments are expected to strengthen opportunities for ester lubricant manufacturers supplying automotive OEMs, component producers and specialty lubricant formulators.
Market Challenges
High Raw Material Dependency and Specialty Chemical Supply Constraints
The US Ester Lubricant Market faces challenges related to dependence on specialty chemical feedstocks, including fatty acids, polyols, alcohols and other esterification inputs required for producing performance-grade lubricants. Supply fluctuations in chemical raw materials can influence manufacturing consistency and availability of specialty ester formulations. The US chemical manufacturing industry remains a major industrial consumer, with chemical manufacturing shipments reaching approximately USD 918.2 billion in 2024, highlighting the scale and complexity of chemical supply chains supporting lubricant production. Ester lubricant manufacturers must manage sourcing requirements for high-purity raw materials while maintaining consistent formulation quality for aerospace, automotive and industrial applications. Global disruptions affecting chemical logistics, energy availability and intermediate production can create challenges for specialty lubricant producers. Additionally, ester lubricants often require application-specific formulation expertise, testing and qualification processes, increasing development complexity compared with conventional lubricant products. Manufacturers must balance performance requirements with supply-chain resilience, sustainability objectives and regulatory expectations. These factors can increase operational challenges for companies producing advanced ester lubricant solutions for demanding industrial and transportation applications.
Competition from Alternative Synthetic Lubricant Technologies
The US Ester Lubricant Market experiences competitive pressure from other synthetic lubricant technologies, including polyalphaolefin (PAO), polyalkylene glycol (PAG) and other advanced base-stock formulations. While ester lubricants provide advantages such as high lubricity, thermal stability and biodegradability potential, alternative synthetic chemistries may offer advantages in specific applications related to compatibility, cost efficiency or formulation flexibility. The US automotive sector demonstrates the scale of lubricant demand transformation, with approximately 283 million registered vehicles in operation in the United States in 2024, creating a broad market for different lubricant technologies. Industrial users often evaluate lubricants based on equipment requirements, maintenance intervals, operating temperatures and total lifecycle performance. As manufacturers seek optimized solutions, ester lubricants must compete through technical differentiation, OEM approvals and application-specific advantages. The increasing adoption of electric vehicles also creates uncertainty because some traditional lubrication requirements are declining while new fluid requirements are emerging. Companies operating in the ester lubricant segment need continuous formulation development, customer qualification support and innovation investment to maintain relevance across changing automotive and industrial applications.
Market Opportunities
Development of Bio-Based and Environmentally Acceptable Ester Lubricants
The US Ester Lubricant Market has significant opportunities through the development of bio-based, biodegradable and environmentally acceptable lubricant formulations designed for industries seeking improved sustainability performance. Demand for environmentally responsible lubricants is increasing across industrial sectors such as marine, forestry, construction equipment, agriculture and manufacturing where lubricant leakage and environmental impact are key concerns. The US agricultural sector provides a relevant application ecosystem, with the United States operating approximately 880 million acres of farmland in 2024, creating potential demand for environmentally suitable lubricants used in agricultural machinery and equipment. Ester-based lubricants derived from renewable feedstocks can provide improved biodegradability characteristics while maintaining performance requirements such as oxidation resistance and lubrication efficiency. Industrial users are increasingly evaluating products based on environmental compliance, equipment protection and operational efficiency. The expansion of sustainability initiatives across manufacturing and transportation industries creates opportunities for ester lubricant producers to develop renewable-content formulations, low-toxicity products and specialty fluids for environmentally sensitive applications. These opportunities are supported by increasing demand for advanced lubrication technologies that combine technical performance with environmental considerations.
Increasing Demand for Specialty Lubricants in Industrial Automation and Advanced Manufacturing
The expansion of automated manufacturing, precision equipment and advanced industrial processes creates opportunities for ester lubricants designed for high-performance machinery applications. Modern manufacturing systems require lubricants that can support higher operating speeds, reduced downtime, extended equipment life and improved efficiency. The US manufacturing sector remains a significant industrial base, generating USD 6.98 trillion in shipments, sales and revenue in 2024 and employing 12.01 million workers, according to national economic statistics. Advanced manufacturing facilities increasingly utilize robotics, precision machining systems, automated production lines and specialized equipment requiring reliable lubrication under demanding conditions. Ester lubricants can provide advantages in applications requiring low volatility, excellent film strength and stable performance across temperature variations. Industries such as semiconductor manufacturing, aerospace production, automotive assembly and industrial machinery are potential growth areas for specialty ester lubricant adoption. Furthermore, the increasing focus on energy efficiency and predictive maintenance creates demand for premium lubrication solutions capable of reducing friction losses and improving equipment reliability. This shift toward advanced industrial operations provides opportunities for ester lubricant manufacturers to expand into high-value applications requiring specialized performance characteristics.
Future Outlook
The US Ester Lubricant Market is expected to evolve toward higher-performance and application-specific lubricant formulations. Growth will be influenced by continued demand from aerospace, automotive, industrial machinery, metalworking and environmentally sensitive applications. The expansion of electric vehicles is also changing lubricant formulation requirements, creating opportunities for specialized fluids beyond traditional engine lubrication. US manufacturing activity provides a broad installed equipment base, while aviation activity supports technically demanding ester applications. Development of bio-based esters, high-temperature formulations, low-volatility lubricants and environmentally acceptable fluids is expected to remain important for product innovation.
The broader US industrial environment remains substantial, with manufacturing generating USD 6.98 trillion in 2024 sales, shipments and revenue and chemical manufacturing generating USD 918.2 billion in shipments. This creates opportunities for ester-based lubricants in production equipment, hydraulic systems, compressors, metalworking operations and specialty machinery. The transportation sector is also undergoing structural change: US electric-car sales reached 1.6 million units in 2024, while 24 new electric-car models entered the US market during the year. These developments are likely to increase the importance of formulation technologies designed for new thermal, electrical and mechanical operating requirements.
Major Players
- ExxonMobil Corporation
- BASF Corporation
- Croda Inc.
- Emery Oleochemicals
- LANXESS Corporation
- The Lubrizol Corporation
- Cargill, Incorporated
- Afton Chemical Corporation
- Vantage Performance Materials
- Zschimmer & Schwarz
- Quaker Houghton
- NYCO
- Valtris Specialty Chemicals
- Lubriplate Lubricants Company
- PMC Biogenix, Inc.
Key Target Audience
- Automotive OEMs and Tier-1 Component Manufacturers
- Aerospace OEMs, Aircraft Operators and Aviation Maintenance Organizations
- Industrial Machinery and Equipment Manufacturers
- Lubricant Blenders and Formulators
- Specialty Ester and Base Oil Manufacturers
- Investments and Venture Capitalist Firms
- Government and Regulatory Bodies (US Environmental Protection Agency, Federal Aviation Administration, Occupational Safety and Health Administration)
- Industrial Lubricant Distributors and Specialty Chemical Procurement Organizations
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves constructing an ecosystem map encompassing ester base-stock producers, specialty chemical manufacturers, lubricant blenders, additive suppliers, OEMs and industrial end users. The assessment identifies ester chemistry, application, viscosity, performance and end-use variables influencing US demand.
Step 2: Market Analysis and Construction
Historical market information is compiled through analysis of ester production, lubricant consumption, industrial activity, automotive applications, aerospace utilization and trade flows. Top-down and bottom-up approaches are applied to establish market value, volume, product segmentation and application-level demand.
Step 3: Hypothesis Validation and Expert Consultation
Market hypotheses are developed around ester chemistry adoption, application requirements, OEM qualification, bio-based lubricant penetration and specialty lubricant demand. These hypotheses are validated through discussions with lubricant manufacturers, formulators, distributors, OEM-linked specialists and industrial users.
Step 4: Research Synthesis and Final Output
The final stage integrates secondary information, industry interviews, application assessments and company-level analysis. Market estimates are cross-checked through demand-side and supply-side calculations, with segmentation assumptions, competitive positioning and forecast drivers reconciled before final reporting.

- Executive Summary
- Research Methodology (Market Definition and Scope, US Ester Lubricant Market Classification, Ester Base Stock Mapping, Ester Chemistry Assessment, Ester Molecular Structure Assessment, Monoester and Diester Evaluation, Polyol Ester Assessment, Complex Ester Assessment, Trimellitate Ester Assessment, Synthetic and Bio-Based Ester Assessment, Viscosity Grade Mapping, Performance Property Assessment, Application-Level Demand Analysis, End-Use Industry Assessment, Lubricant Formulation Mapping, Base Oil Supply Assessment, Domestic Production Assessment, Import and Export Trade Analysis, Raw Material Supply Assessment, Demand-Side Assessment, Supply-Side Assessment, Top-Down Market Sizing, Bottom-Up Market Sizing, Primary Industry Interviews, Data Triangulation, Forecasting Framework, Market Share Validation, Limitations and Future Conclusions)

- Definition and Scope
- US Ester Lubricant Industry Evolution and Development of Synthetic Base Oil Technology, High-Performance Lubricant Formulation, Aerospace Lubrication, Automotive Lubricants, Industrial Fluid Applications and Bio-Based Lubricant Technologies
- Ester Lubricant Value Chain Analysis
- Ester Lubricant Supply Chain Analysis
- Fatty Acid and Alcohol Feedstock Suppliers, Petrochemical Feedstock Suppliers, Ester Base Stock Manufacturers, Specialty Ester Producers, Lubricant Additive Manufacturers, Lubricant Blenders, Industrial Lubricant Manufacturers, Automotive Lubricant Suppliers, Aerospace Lubricant Suppliers, Distributors, Industrial OEMs and End-Use Industries
- Ester Lubricant Integration Across Automotive Engine Oils, Transmission Fluids, Gear Lubricants, Hydraulic Fluids, Compressor Oils, Turbine Lubricants, Metalworking Fluids, Greases, Aerospace Lubricants, Marine Lubricants and Environmentally Acceptable Lubricants

- Growth Drivers (Demand for High-Performance Synthetic Lubricants, Aerospace Lubricant Requirements, Automotive Efficiency Improvements, Industrial Equipment Modernization, High-Temperature Lubrication Requirements, Growth of Environmentally Acceptable Lubricants, Increasing Equipment Service-Life Requirements, Advanced Metalworking Applications, Demand for Low-Volatility Lubricants)
- Market Challenges (Raw Material Price Volatility, Specialty Ester Feedstock Availability, Complex Ester Manufacturing Requirements, Formulation Compatibility Constraints, Stringent Product Qualification Requirements, Competition from PAO and Other Synthetic Base Stocks, Hydrolytic Stability Challenges, High Performance-Testing Requirements, Supply Chain Disruptions)
- Market Opportunities (Bio-Based Ester Expansion, Electric Vehicle Thermal and Lubrication Applications, Aerospace and Turbine Lubricants, Environmentally Acceptable Hydraulic Fluids, High-Temperature Industrial Lubricants, Advanced Metalworking Fluids, Food-Grade Lubricants, Specialty Greases, Renewable Feedstock-Based Esters)
- Market Trends (Shift Toward Synthetic Base Stocks, Bio-Based Lubricant Development, Low-Volatility Ester Formulations, High-Temperature Performance Enhancement, Electrification-Driven Lubricant Development, Environmentally Acceptable Lubricants, Advanced Metalworking Fluids, Specialty Aerospace Lubricants, Longer Drain Intervals, High-Performance Ester-PAO Blending)
- Government Regulations and Standards (US Environmental Protection Agency Requirements, Occupational Safety and Health Administration Requirements, Toxic Substances Control Act Requirements, American Petroleum Institute Lubricant Standards, SAE Lubricant Standards, ASTM Testing Standards, Federal Aviation Administration Requirements, US Department of Defense Lubricant Specifications, NSF Food-Grade Lubricant Requirements, Vessel General Permit Requirements)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Competition Ecosystem

- By Market Value (2020-2025)
- By Market Volume (2020-2025)
- By Ester Base Stock Consumption Volume (2020-2025)
- By Synthetic Ester Consumption Volume (2020-2025)
- By Bio-Based Ester Consumption Volume (2020-2025)
- By Monoester Consumption Volume (2020-2025)
- By Diester Consumption Volume (2020-2025)
- By Polyol Ester Consumption Volume (2020-2025)

- By Ester Type (In Value %)
Monoesters
Diesters
Polyol Esters
Complex Esters
Trimellitate Esters
Phosphate Esters
Neopolyol Esters
Other Specialty Esters - By Base Stock Origin (In Value %)
Petrochemical-Based Esters
Oleochemical-Based Esters
Bio-Based Esters
Renewable Feedstock-Based Esters
Blended Ester Base Stocks - By Lubricant Application (In Value %)
Engine Oils
Transmission and Gear Lubricants
Hydraulic Fluids
Compressor Lubricants
Turbine Lubricants
Metalworking Fluids
Greases
Aerospace Lubricants
Marine Lubricants
Refrigeration Lubricants - By End-Use Industry (In Value %)
Automotive and Transportation
Aerospace and Defense
Industrial Manufacturing
Metalworking
Power Generation
Oil and Gas
Marine and Shipping
Food and Beverage Processing
Mining and Construction
Chemical and Pharmaceutical Manufacturing - By Region (In Value %)
Northeast US
Midwest US
South US
West US

- Market Share of Major Players (By US Revenue, Ester Base Stock Sales Volume, Ester Chemistry Portfolio, Production Capacity, Synthetic Ester Portfolio, Bio-Based Ester Portfolio, Automotive Application Exposure, Aerospace Application Coverage, Industrial Application Coverage, Distribution Network Coverage, Regional Presence, OEM Customer Coverage, Technical Service Capability)
- Cross Comparison Parameters (Ester Lubricant Revenue, Ester Chemistry Portfolio Breadth, Polyol Ester Technology Coverage, Diester and Monoester Capability, Aerospace Lubricant Capability, Automotive Lubricant Application Coverage, Bio-Based Ester Portfolio Breadth, US Distribution Network Reach)
- SWOT Analysis of Major Players
- Competitive Positioning Matrix
- Detailed Profiles of Major Companies
ExxonMobil Corporation
BASF Corporation
Croda Inc.
Emery Oleochemicals
LANXESS Corporation
The Lubrizol Corporation
Cargill, Incorporated
Afton Chemical Corporation
Vantage Performance Materials
Zschimmer & Schwarz Lubricant Components
Quaker Houghton
NYCO
Valtris Specialty Chemicals
Lubriplate Lubricants Company
PMC Biogenix, Inc.

- Automotive OEM Ester Lubricant Requirement Assessment
- Aerospace and Aircraft Lubricant Procurement Assessment
- Industrial Machinery Lubricant Requirement Analysis
- Metalworking Fluid Formulation Assessment
- Power Generation Lubricant Procurement Analysis
- Oil and Gas Equipment Lubrication Assessment
- Marine Lubricant Requirement Analysis
- Food Processing Lubricant Procurement Assessment
- Mining and Construction Equipment Lubricant Analysis
- Compressor and Turbine Lubricant Requirement Assessment
- Lubricant Blender Ester Base Stock Procurement Analysis
- Industrial OEM Ester Lubricant Qualification Assessment

- By Market Value (2026-2035)
- By Market Volume (2026-2035)
- By Ester Base Stock Consumption Volume (2026-2035)
- By Synthetic Ester Consumption Volume (2026-2035)
- By Bio-Based Ester Consumption Volume (2026-2035)
- By Monoester Consumption Volume (2026-2035)
- By Diester Consumption Volume (2026-2035)
- By Polyol Ester Consumption Volume (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
