
 Download PDF
Market Overview
The Vietnam Laminated Glass Market is valued at approximately ~USD XX million in 2024 and is driven by increasing demand from commercial construction, residential buildings, automotive manufacturing and infrastructure projects. Vietnam’s construction sector remained a major contributor to economic activity, with the General Statistics Office reporting construction industry growth of 7.87% in 2024. The country recorded more than 2,000 new foreign-invested projects in 2024, supporting demand for modern buildings requiring safety glazing, facade systems and high-performance glass solutions.
Vietnam’s laminated glass demand is concentrated in Ho Chi Minh City, Hanoi, Binh Duong, Dong Nai, Hai Phong and Da Nang due to their concentration of construction projects, industrial zones, automotive manufacturing facilities and commercial developments. Ho Chi Minh City and Hanoi dominate architectural laminated glass consumption because of high-rise residential, office, retail and hospitality developments. Binh Duong and Dong Nai support industrial and manufacturing demand due to their large industrial parks. Vietnam attracted USD 25.35 billion in registered foreign direct investment in 2024, strengthening demand for modern industrial facilities and commercial infrastructure requiring advanced glazing systems.
Market Segmentation
By Product Type
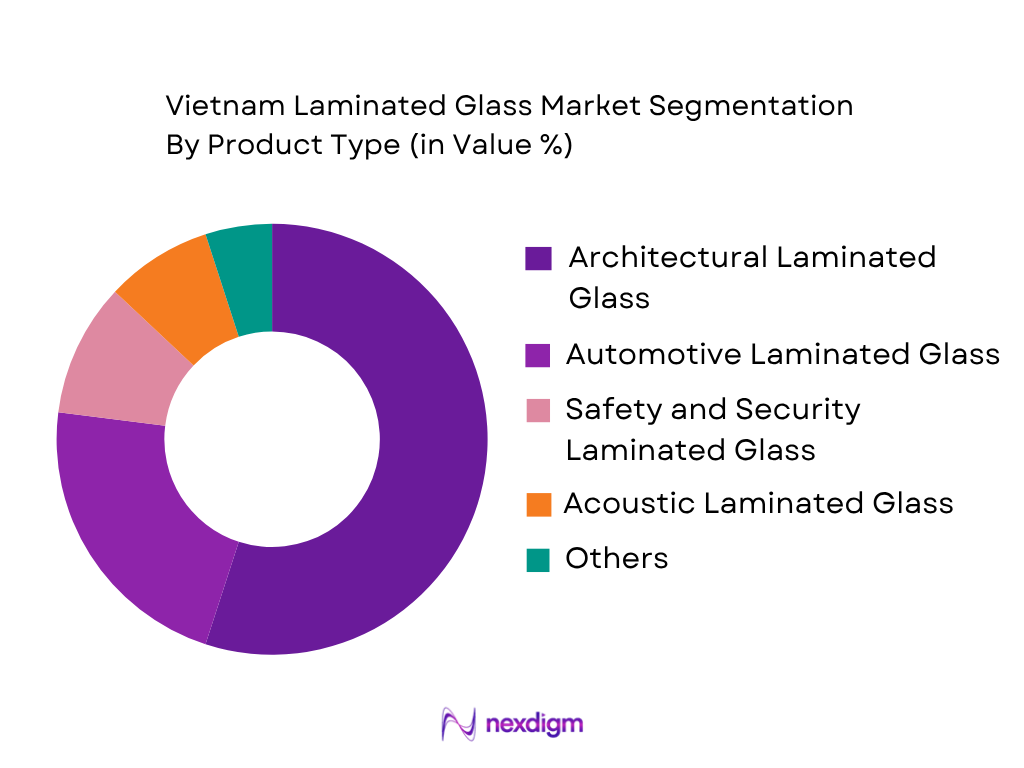
The Vietnam Laminated Glass Market is segmented by application type into architectural laminated glass, automotive laminated glass, safety and security laminated glass, acoustic laminated glass and specialty laminated glass applications. Architectural laminated glass holds the dominant market position due to rapid urbanization, expansion of commercial buildings and increasing adoption of modern facade systems. High-rise residential towers, office buildings, shopping malls and hospitality projects increasingly use laminated glass because of its safety performance, sound insulation capability and compliance with modern building requirements. Vietnam’s urban construction expansion, particularly in Hanoi and Ho Chi Minh City, has increased demand for curtain walls, skylights, balustrades and structural glazing systems. The growth of premium real estate developments and green building projects further supports adoption of laminated architectural glass over conventional glazing solutions.
By Interlayer Material Type
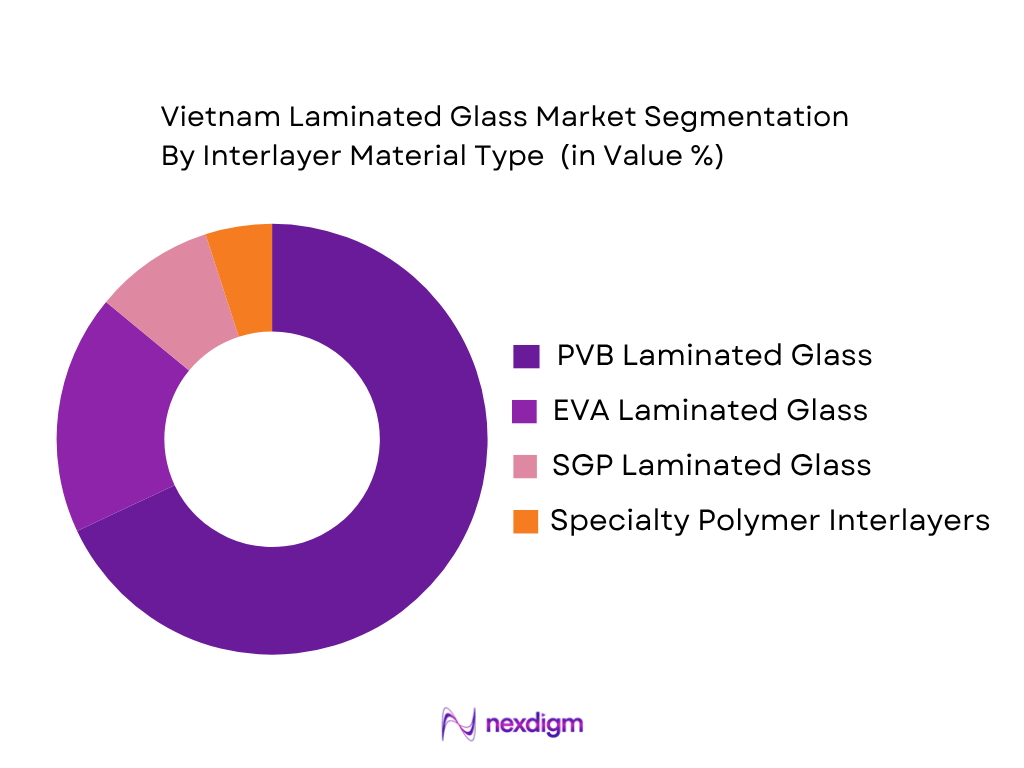
The Vietnam Laminated Glass Market is segmented by interlayer material type into PVB laminated glass, EVA laminated glass, SGP laminated glass and specialty polymer interlayer laminated glass. Polyvinyl Butyral (PVB) laminated glass dominates the segment because of its extensive use in architectural and automotive applications. PVB provides strong adhesion between glass layers, impact resistance, UV protection and noise reduction characteristics, making it suitable for building facades, windows and automotive windshields. Automotive manufacturers widely prefer PVB laminated glass due to safety regulations requiring windshield durability and occupant protection. In architectural applications, PVB-based laminated glass is increasingly adopted in commercial buildings where safety, acoustic performance and aesthetic flexibility are important. The availability of multiple PVB options, including clear, acoustic and colored variants, supports its continued dominance in Vietnam.
Competitive Landscape
The Vietnam Laminated Glass Market consists of multinational glass manufacturers, domestic glass processors and automotive glass suppliers. The market is influenced by companies including AGC Glass, Saint-Gobain, NSG Group, Viglacera and Xinyi Glass, which have established manufacturing capabilities, technology expertise and distribution networks. Competition is based on production capacity, glass-processing technology, interlayer capability, project approvals, automotive OEM relationships and ability to supply large-scale construction projects.
| Company | Establishment Year | Headquarters | Vietnam Presence | Product Portfolio | Manufacturing Capability | Major Application | Technology Focus |
| AGC Glass | 1907 | Tokyo, Japan | ~ | ~ | ~ | ~ | ~ |
| Saint-Gobain Glass | 1665 | Courbevoie, France | ~ | ~ | ~ | ~ | ~ |
| NSG Group / Pilkington | 1918 | Tokyo, Japan | ~ | ~ | ~ | ~ | ~ |
| Viglacera Corporation | 1974 | Hanoi, Vietnam | ~ | ~ | ~ | ~ | ~ |
| Xinyi Glass | 1988 | Hong Kong, China | ~ | ~ | ~ | ~ | ~ |
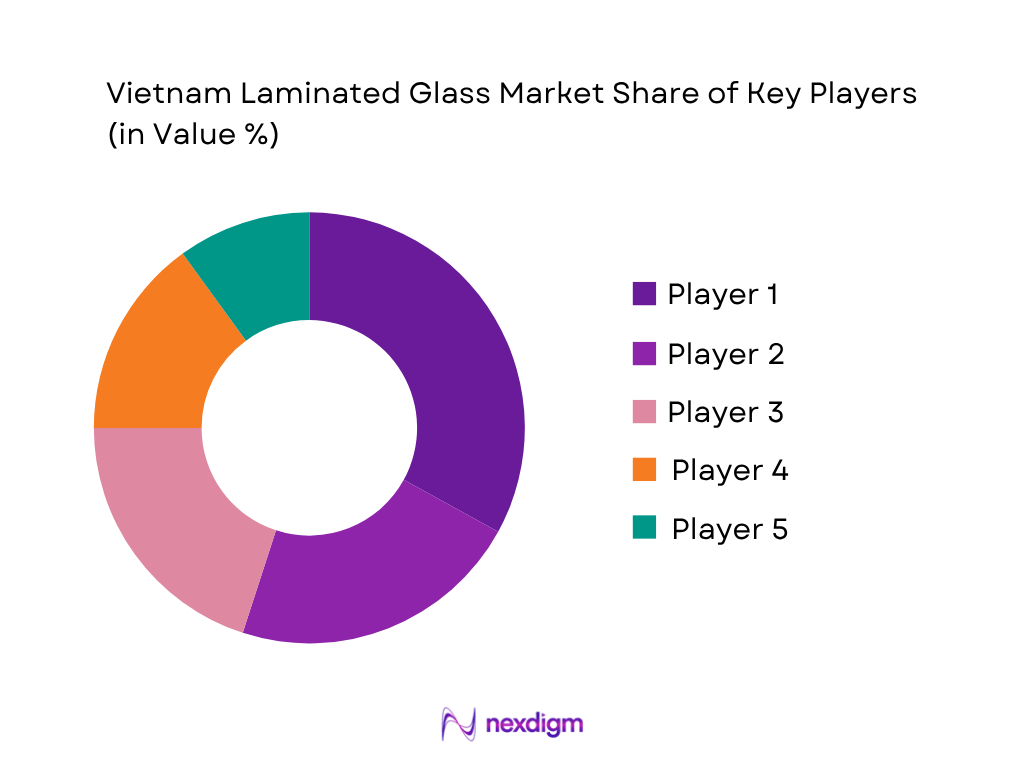
Vietnam Laminated Glass Market Analysis
Growth Drivers
Rapid Urbanization and High-Rise Construction Expansion
Rapid urbanization and large-scale real estate development are strengthening demand for laminated glass in Vietnam, particularly across high-rise residential towers, commercial complexes, hospitality projects and modern infrastructure. The General Statistics Office of Vietnam reported that the country’s urban population reached 38.6 million people in 2024, increasing demand for advanced building materials that support safety, durability and architectural performance. Vietnam’s construction sector recorded a growth rate of 7.87% in 2024, reflecting continued activity in residential, commercial and infrastructure projects. The Ministry of Construction reported that urban development programs continued across major cities, including Hanoi, Ho Chi Minh City, Hai Phong and Da Nang, where high-rise buildings increasingly require laminated glazing systems for facades, windows and safety applications. Ho Chi Minh City recorded more than 10 million residents, creating strong demand for vertical construction due to land constraints. Laminated glass adoption is further supported by foreign investment-driven industrial and commercial developments, with Vietnam registering USD 25.35 billion in foreign direct investment in 2024, increasing the need for modern factories, offices and infrastructure facilities incorporating advanced glazing systems.
Expansion of Automotive Manufacturing Capacity
The expansion of Vietnam’s automotive manufacturing ecosystem is increasing demand for laminated glass, particularly for windshields, electric vehicles and advanced vehicle glazing systems. Vietnam produced approximately 388,000 motor vehicles in 2024, according to industry statistics reported through national automotive production data, supporting demand for automotive safety glass components. The country’s automotive sector is concentrated around manufacturing clusters in Hai Phong, Quang Nam, Vinh Phuc and Hanoi, where vehicle assembly facilities require reliable laminated windshield supply. Vietnam’s manufacturing sector recorded a manufacturing industrial production index increase of 8.4 points in 2024, reflecting improved industrial activity and supporting component demand. Electric vehicle development is also expanding automotive glass requirements, with domestic EV manufacturers increasing vehicle production capacity and requiring lightweight, durable glazing solutions. Laminated glass provides impact resistance, acoustic insulation and occupant protection, making it a preferred material for automotive windshields. The country’s automotive supply-chain expansion, supported by USD 25.35 billion in registered foreign direct investment in 2024, is creating additional opportunities for laminated glass manufacturers supplying OEM and replacement markets.
Market Challenges
Dependence on Imported PVB and Specialty Interlayers
Vietnam’s laminated glass industry faces challenges due to dependence on imported PVB, EVA and SGP interlayer materials required for high-performance laminated glass production. Advanced laminated glass applications rely on specialized polymer films that are often sourced from international suppliers because domestic production capabilities remain limited. Vietnam recorded total merchandise imports of approximately USD 380 billion in 2024, demonstrating the country’s significant dependence on imported industrial inputs and intermediate materials. The chemical and plastics-related manufacturing ecosystem remains integrated with global supply chains, increasing exposure to international raw-material availability and logistics conditions. PVB interlayers are essential for architectural safety glass, acoustic glazing and automotive windshields, while specialty interlayers such as SGP are required for structural and security applications. The Ministry of Industry and Trade reported continued growth in imported machinery, chemicals and production materials supporting manufacturing activities. These import dependencies can increase supply-chain complexity for laminated glass producers, particularly when manufacturers require customized interlayer specifications, color options or enhanced performance characteristics for premium construction and automotive applications.
High Production and Processing Investment Requirements
Laminated glass manufacturing requires significant investment in specialized processing equipment, including glass cutting systems, washing lines, clean-room environments, lamination systems and autoclave technology. The capital-intensive nature of production creates entry barriers for smaller processors and limits domestic availability of advanced laminated glass categories. Vietnam’s manufacturing sector recorded total sales of approximately VND 11,000 trillion in 2024, reflecting the scale of industrial activity but also highlighting the competitive environment where manufacturers must continuously invest in technology upgrades. The glass industry is energy intensive, requiring stable electricity supply and advanced thermal processing capabilities. Vietnam’s total electricity consumption exceeded 300 billion kWh in 2024, demonstrating the scale of industrial energy demand supporting manufacturing operations. Large-format architectural laminated glass, security glass and acoustic glass require higher technical precision compared with conventional glazing products. Manufacturers must maintain quality certifications, testing capability and skilled technical labor to meet requirements from construction developers, automotive companies and infrastructure contractors. These investment requirements create challenges for smaller domestic players competing against integrated multinational glass manufacturers.
Market Opportunities
Expansion of Energy-Efficient Building Glass Solutions
The growing focus on sustainable construction and energy-efficient buildings creates opportunities for laminated glass manufacturers to develop advanced glazing solutions combining safety, thermal insulation and solar-control performance. Vietnam’s construction industry is increasingly influenced by green building requirements as developers seek materials that improve energy efficiency and occupant comfort. The country recorded USD 25.35 billion in foreign direct investment in 2024, supporting the development of industrial facilities, commercial buildings and international-standard projects requiring high-performance building materials. Hanoi and Ho Chi Minh City continue to experience demand for modern office buildings, residential towers and commercial complexes where energy-efficient facades are becoming more important. Vietnam’s Ministry of Construction has promoted sustainable building practices through energy-efficiency regulations and green construction initiatives. Laminated glass with advanced interlayers can support reduced heat gain, improved acoustic insulation and enhanced occupant safety. The opportunity is further strengthened by the country’s urban population reaching 38.6 million people in 2024, increasing demand for high-density residential and commercial developments. Manufacturers capable of producing low-emissivity, solar-control and multifunctional laminated glass can capture increasing demand from premium construction projects.
Increasing Automotive Laminated Glass Production and Electric Vehicle Glass Demand
Vietnam’s expanding automotive and electric vehicle ecosystem creates opportunities for laminated glass manufacturers to increase local production and supply advanced glazing solutions. The country’s vehicle manufacturing industry produced approximately 388,000 vehicles in 2024, supporting demand for automotive windshields and specialty glass components. Vietnam has also emerged as a regional electric vehicle production hub, with domestic manufacturers expanding EV assembly and battery-related investments. Automotive laminated glass is essential for windshields because it provides safety performance, impact resistance and acoustic benefits while supporting lightweight vehicle design. The country attracted USD 25.35 billion in foreign direct investment in 2024, including investments in manufacturing sectors that strengthen automotive supply chains. Major automotive clusters in Hai Phong, Quang Nam, Hanoi and Vinh Phuc provide localized opportunities for glass suppliers to integrate with OEM production networks. As vehicle manufacturers introduce more advanced models, demand is expected to shift toward lightweight laminated glass, solar-control glazing and acoustic automotive glass technologies. Local manufacturing of automotive laminated glass can reduce dependence on imports and improve supply-chain responsiveness for domestic vehicle production.
Future Outlook
Over the next decade, the Vietnam Laminated Glass Market is expected to demonstrate significant growth driven by urban development, infrastructure expansion, automotive manufacturing growth and increasing demand for energy-efficient buildings. The adoption of safety glazing solutions is expected to increase as developers prioritize advanced building envelopes and compliance with modern construction standards.Commercial real estate expansion, foreign investment projects and industrial park development will continue supporting architectural laminated glass demand. Automotive manufacturing growth will further strengthen demand for laminated windshields and specialty vehicle glazing. Future market development will also be influenced by smart glass technologies, acoustic laminated solutions and sustainable construction requirements.
Major Players
- AGC Glass Vietnam
- Saint-Gobain Vietnam
- NSG Group / Pilkington Vietnam
- Viglacera Corporation
- Xinyi Glass Vietnam
- Taiwan Glass Vietnam
- Chu Lai Truong Hai Glass
- Euroglass Vietnam
- Phu My Glass
- Hai Long Glass
- Hanoi Glass Joint Stock Company
- Guardian Glass
- Fuyao Glass Vietnam
- Vietnam Glass Industries Corporation
- Kibing Group Vietnam
Key Target Audience
- Laminated Glass Manufacturers and Glass Processing Companies
- Architectural Glass Fabricators and Facade Contractors
- Automotive OEMs and Automotive Glass Suppliers
- Construction Developers and Real Estate Companies
- Solar and Specialty Glass Manufacturers
- Investments and Venture Capitalist Firms
- Government and Regulatory Bodies (Ministry of Construction, Ministry of Industry and Trade, Vietnam Energy Efficiency Program, Directorate for Standards Metrology and Quality)
- Infrastructure Development Companies and Transportation Project Developers
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves developing a comprehensive ecosystem map covering laminated glass manufacturers, float glass suppliers, interlayer suppliers, processors, construction companies, automotive manufacturers and end users. Secondary research is conducted using industry databases, government publications and company information to identify key market variables including production capacity, application demand, technology adoption and supply-chain structure.
Step 2: Market Analysis and Construction
This phase involves analyzing historical market information related to laminated glass consumption, production capacity, import dependency, application penetration and end-use industry demand. Architectural construction, automotive manufacturing and infrastructure development trends are evaluated to determine demand patterns. Supply-side assessment includes manufacturer capabilities, processing facilities and distribution structures.
Step 3: Hypothesis Validation and Expert Consultation
Market assumptions are validated through discussions with glass manufacturers, construction companies, automotive suppliers, facade contractors and industry specialists. These consultations provide insights into product preferences, procurement behavior, technology adoption, manufacturing constraints and competitive dynamics. Expert feedback is used to refine market segmentation and validate demand estimates.
Step 4: Research Synthesis and Final Output
The final stage combines primary and secondary research findings to develop a comprehensive market assessment. Company-level analysis, production trends, application demand and industry developments are consolidated to create a validated outlook. The research output provides insights into market structure, competition, opportunities and future growth areas.

- Executive Summary
- Research Methodology (Market Definition and Scope, Vietnam Laminated Glass Market Classification, Architectural Laminated Glass Demand Assessment, Automotive Laminated Glass Consumption Mapping, Safety and Security Glass Requirement Assessment, Acoustic Laminated Glass Application Assessment, Domestic Laminated Glass Manufacturing Capacity Assessment, Float Glass Supply and Processing Capacity Assessment, Imported Laminated Glass Supply Assessment, PVB EVA and SGP Interlayer Material Assessment, Glass Lamination Technology and Autoclave Processing Mapping, Construction Project Pipeline Assessment, High-Rise Building and Facade Glass Demand Mapping, Replacement and Renovation Glass Demand Assessment, Application-Level Demand Assessment, End-Use Industry Demand Mapping, Primary Industry Interviews, Top-Down Market Sizing, Bottom-Up Company Revenue and Production Volume Assessment, Trade Flow Analysis, Data Triangulation, Pricing Assessment, Forecasting Framework)

- Definition and Scope
- Vietnam Laminated Glass Industry Evolution
- Laminated Glass Manufacturer Structure
- Vietnam Laminated Glass Value Chain Analysis
- Vietnam Laminated Glass Supply Chain Analysis

- Growth Drivers (Rapid Urbanization and High-Rise Construction Expansion, Increasing Demand for Safety and Security Glass, Growth of Commercial Real Estate Development, Expansion of Automotive Manufacturing Capacity, Rising Adoption of Modern Glass Facades, Infrastructure Development Projects, Increasing Green Building Adoption, Tourism and Hospitality Construction Growth, Demand for Acoustic Noise Reduction Solutions, Replacement of Conventional Glass with Safety Laminated Glass)
- Market Challenges (High Production and Processing Investment Requirements, Dependence on Imported PVB and Specialty Interlayers, Energy-Intensive Glass Manufacturing Process, Limited Domestic Production of Advanced Laminated Glass Types, Raw Material Price Volatility, Complex Quality Certification Requirements, Competition from Tempered Glass Products, Skilled Workforce Requirement for Glass Processing, Transportation and Handling Challenges for Large Glass Panels, Fragmented Fabrication Network)
- Market Opportunities (Expansion of Energy-Efficient Building Glass Solutions, Growth of Premium Architectural Facades, Increasing Automotive Laminated Glass Production, Electric Vehicle Glass Demand Growth, Development of Acoustic Laminated Glass for Urban Buildings, Local Production of Advanced Interlayers, Security Glass Applications in Infrastructure Projects, Smart Laminated Glass Adoption, Sustainable Construction Material Demand, High-Performance Glass Solutions for Green Buildings)
- Market Trends (Low-Iron Laminated Glass Adoption, Large-Format Architectural Laminated Glass Panels, Acoustic PVB Technology Growth, Solar Control Laminated Glass Integration, Smart Glass and Electrochromic Laminated Solutions, Sustainable Glass Processing, Lightweight Automotive Laminated Glass, Digital Glass Processing Technology, High-Performance Building Envelope Design, Advanced Interlayer Technology Development)
- Government Regulations and Standards (Vietnam Construction Standards, Ministry of Construction Building Regulations, Safety Glass Requirements, Fire Safety Construction Regulations, Energy Efficiency Building Standards, Green Building Certification Requirements, Automotive Safety Glass Standards, Quality Standards for Flat Glass Products, Import Quality Control Requirements, Environmental Regulations for Glass Manufacturing)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem
- Competition Ecosystem

- By Market Value (2020-2025)
- By Laminated Glass Consumption Volume (2020-2025)
- By Architectural Laminated Glass Consumption Volume (2020-2025)
- By Automotive Laminated Glass Consumption Volume (2020-2025)

- By Product Type (In Value %)
Architectural Laminated Glass
Automotive Laminated Glass
Safety Laminated Glass
Security Laminated Glass
Acoustic Laminated Glass
Decorative Laminated Glass
Bullet Resistant Laminated Glass
Fire Resistant Laminated Glass
Solar Control Laminated Glass
Smart Laminated Glass - By Interlayer Material Type (In Value %)
Polyvinyl Butyral (PVB) Laminated Glass
Acoustic PVB Laminated Glass
Colored PVB Laminated Glass
Structural PVB Laminated Glass
Ethylene Vinyl Acetate (EVA) Laminated Glass
SentryGlas Plus (SGP) Laminated Glass
Ionoplast Interlayer Laminated Glass
Specialty Polymer Interlayer Laminated Glass - By Glass Thickness Type (In Value %)
Thin Laminated Glass
Standard Laminated Glass
Thick Laminated Glass
Multi-Layer Laminated Glass
Ultra-Thick Security Laminated Glass - By Application (In Value %)
Curtain Wall Systems
Structural Glazing Systems
Facade Glazing
Window and Door Systems
Skylights and Canopies
Balustrades and Railings
Interior Partitions
Automotive Windshields
Side and Rear Automotive Glass
Public Transport Glass Applications - By End-Use Industry (In Value %)
Commercial Construction
Residential Construction
Hospitality and Tourism Infrastructure
Automotive Manufacturing
Electric Vehicle Manufacturing
Transportation Infrastructure
Airports and Railway Stations
Healthcare Facilities
Educational Buildings
Government and Institutional Buildings
Industrial Facilities - By Performance Attribute (In Value %)
Safety and Impact Resistance Glass
Acoustic Insulation Glass
UV Protection Glass
Solar Control Glass
Thermal Performance Glass
Security and Forced Entry Resistant Glass
Blast Resistant Glass
Fire Resistant Glass
Decorative and Design-Oriented Glass

- Market Share of Major Players (By Vietnam Revenue, Laminated Glass Sales Volume, Architectural Glass Sales Volume, Automotive Glass Sales Volume, Product Type, Interlayer Type, End-Use Industry, Manufacturing Capacity, Distribution Network, Fabrication and Installation Coverage)
- Cross Comparison Parameters (Vietnam Laminated Glass Revenue, Architectural-Automotive-Safety Glass Product Portfolio Breadth, PVB-EVA-SGP Interlayer Technology Capability, Large-Format Facade Glass Processing Capacity, Automotive OEM Glass Supply Capability, High-Rise Construction and Infrastructure Project Exposure, Domestic Manufacturing and Fabrication Network Coverage, Quality Certification and Technical Support Capability)
- SWOT Analysis of Major Players
- Detailed Profiles of Major Companies
Viglacera Corporation
Vietnam Glass Industries Corporation
AGC Glass Vietnam
NSG Group / Vietnam Float Glass Co.
Saint-Gobain Vietnam
Euroglass Vietnam
Phu My Glass
Chu Lai Truong Hai Glass
Hanoi Glass Joint Stock Company
Hai Long Glass
Kibing Group Vietnam
Xinyi Glass Vietnam
Taiwan Glass Vietnam
Guardian Glass Vietnam
Fuyao Glass Vietnam

- Commercial Building Developer Laminated Glass Procurement Assessment
- High-Rise Residential Project Glass Specification Analysis
- Architectural Firm Facade Glass Selection Assessment
- Facade Contractor Laminated Glass Installation Requirement Analysis
- Window and Door Manufacturer Laminated Glass Demand Assessment

- By Market Value (2026-2035)
- By Laminated Glass Consumption Volume (2026-2035)
- By Architectural Laminated Glass Consumption Volume (2026-2035)
- By Automotive Laminated Glass Consumption Volume (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
