
 Download PDF
Market Overview
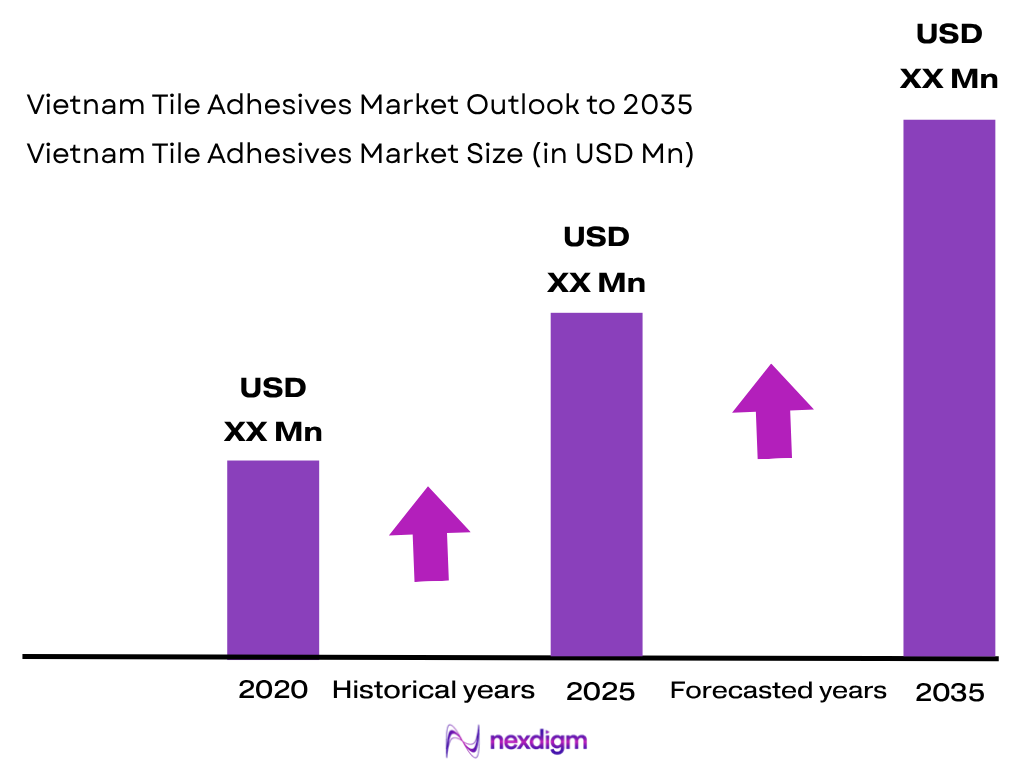
The Vietnam Tile Adhesives Market is valued at approximately ~USD XX million, supported by residential construction, industrial investment, porcelain tile installation and the shift toward factory-mixed mortars. GDP increased from approximately VND 10,221.8 trillion to VND 11,511.9 trillion, while GDP per capita moved from USD 4,323 to USD 4,700 across the two latest observations. Commercial housing and industrial construction consequently provide an expanding installation base for polymer-modified and flexible tile adhesives.
Ho Chi Minh City, Hanoi, Hai Phong, Bac Ninh, Binh Duong and Dong Nai dominate the Vietnam Tile Adhesives Market because they combine dense housing, commercial development and manufacturing construction. Ho Chi Minh City attracted more than USD 5.85 billion of FDI in the earlier observation; subsequently Bac Ninh attracted USD 5.12 billion, Hai Phong USD 4.94 billion and Ho Chi Minh City USD 3.04 billion, reinforcing tile-installation demand around industrial and residential development corridors.
Market Segmentation
By Adhesive Technology
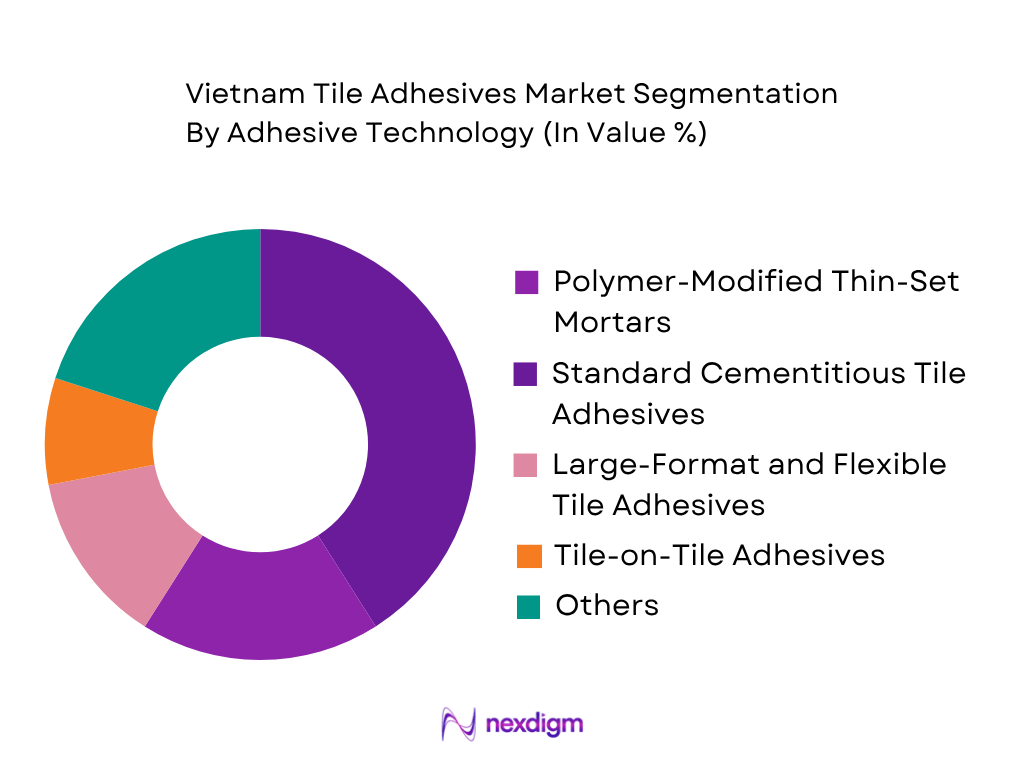
The Vietnam Tile Adhesives Market is segmented into standard cementitious adhesives, polymer-modified cementitious adhesives, flexible adhesives, large-format tile mortars, rapid-setting adhesives, tile-on-tile systems, dispersion adhesives and reaction-resin products. Polymer-modified cementitious adhesives hold the dominant modeled market share because they address the broadest range of ceramic, porcelain and homogeneous tile installations while offering improved adhesion, water retention and open time compared with conventional cement-sand mortar. Vietnam’s TCVN 7899-1 is technically equivalent to ISO 13007-1 and formally classifies cementitious, dispersion and reaction-resin tile adhesives, reinforcing performance-based product differentiation. Commercial housing also provides a large addressable base: the Ministry of Construction recorded 937 projects representing about 403,349 units under construction in the fourth quarter, while 69 commercial housing projects totaling approximately 23,041 units were completed across the full year. This construction volume favors repeatable factory-mixed systems on large multi-unit developments.
By Tile and Stone Type
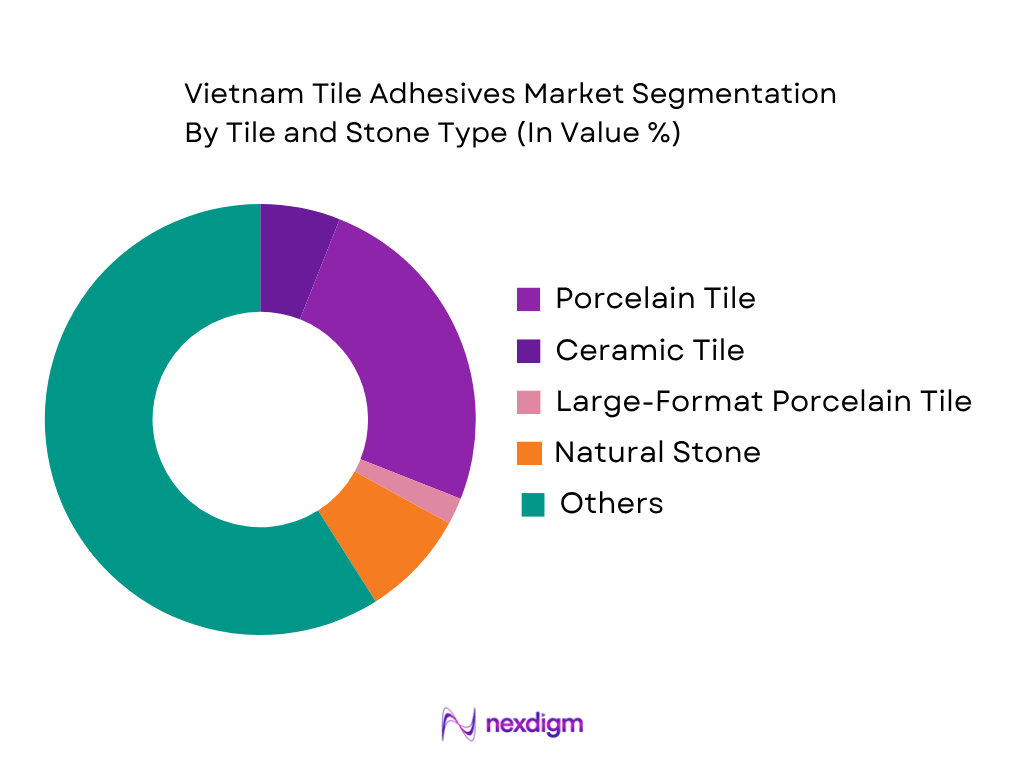
The Vietnam Tile Adhesives Market is segmented into ceramic tiles, porcelain tiles, homogeneous tiles, large-format tiles, porcelain slabs, natural stone, marble, granite, mosaics and engineered stone. Porcelain and homogeneous tiles represent the dominant modeled demand group because their low absorption and increasingly larger dimensions make polymer-modified adhesives technically preferable to conventional mortar. Large-format surfaces also require stronger wetting, better transfer, extended open time and lower vertical slip. Current product portfolios already reflect this shift: Weber Vietnam offers high-performance systems for large tiles and swimming pools, flexible adhesives for heavy-traffic or vibration-prone areas, and epoxy tile-and-grout products for more demanding applications. These technologies indicate that tile installation is moving toward application-specific chemistry. Vietnam’s residential and industrial construction base further supports this trend, particularly in Ho Chi Minh City, Hanoi, Bac Ninh, Hai Phong, Binh Duong and Dong Nai, where premium apartments, factories and commercial interiors increasingly use low-absorption tile formats.
Competitive Landscape
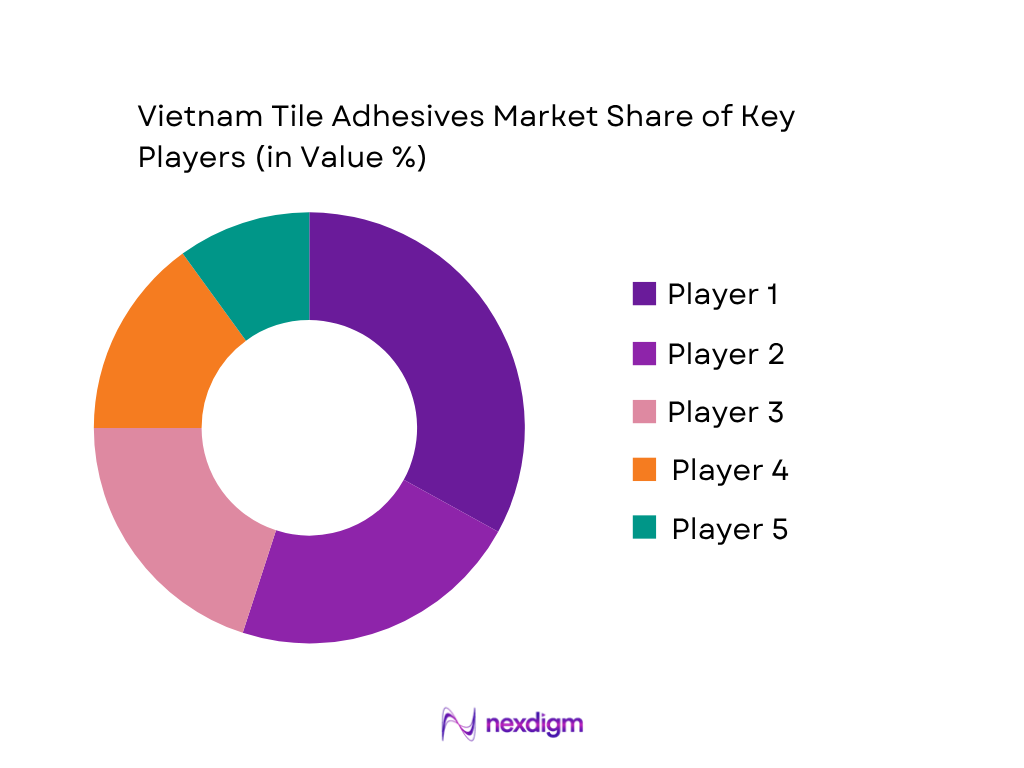
The Vietnam Tile Adhesives Market includes multinational construction-chemical suppliers, specialist tile-installation brands and domestic dry-mix manufacturers. Sika, Saint-Gobain Weber, MAPEI, LATICRETE and ARDEX compete through polymer technology, large-format tile capability, technical specification, local supply and contractor support. Competitive advantage increasingly depends on matching tile size, substrate, exposure conditions and TCVN/ISO performance classifications rather than simply supplying standard cementitious mortar.
| Major Player | Establishment Year | Headquarters | High-Performance Tile Adhesives | Large-Format / Porcelain Capability | Vietnam Manufacturing / Supply | Wet-Area / Exterior Capability | Specialty / Epoxy Systems | Technical Support |
| Sika | 1910 | Baar, Switzerland | ~ | ~ | ~ | ~ | ~ | ~ |
| Saint-Gobain Weber | 1900 | Courbevoie, France | ~ | ~ | ~ | ~ | ~ | ~ |
| MAPEI | 1937 | Milan, Italy | ~ | ~ | ~ | ~ | ~ | ~ |
| LATICRETE | 1956 | Bethany, Connecticut, USA | ~ | ~ | ~ | ~ | ~ | ~ |
| ARDEX | 1949 | Witten, Germany | ~ | ~ | ~ | ~ | ~ | ~ |
Vietnam Tile Adhesives Market Analysis
Growth Drivers
Urban Housing Development and Residential Construction Are Expanding Tile Adhesive Consumption
Vietnam’s expanding housing pipeline is increasing consumption of polymer-modified cementitious adhesives across apartment floors, bathrooms, kitchens, balconies and common areas. The Ministry of Construction recorded 937 commercial housing projects representing about 403,349 units under construction in 2024, alongside 79 newly licensed projects totaling 38,345 units and 69 completed projects containing approximately 23,041 units. Social housing added another substantial tile-installation base, with 20,284 units completed and 25,399 units licensed or started during the year. Construction momentum continued into 2025, when the second quarter contained 899 commercial housing projects representing 398,124 units under construction, including 148,811 apartments. Repetitive multi-unit projects favour factory-mixed adhesives because manufacturers can provide controlled polymer content, water retention and predictable bond performance that are difficult to reproduce consistently with jobsite cement-sand mortar. Bathrooms and kitchens additionally create demand for waterproofing-compatible and slip-resistant products. Vietnam’s macroeconomic scale supports this building activity: World Bank data place 2024 GDP at USD476.39 billion, GDP per capita at USD4,717.3, and population at 100,987,686. These current housing and economic indicators establish a substantial demand base for organized tile-fixing materials.
Manufacturing FDI and Industrial Construction Are Increasing Performance Requirements
Industrial and manufacturing investment is strengthening demand for higher-performance tile adhesives used in factories, electronics facilities, worker amenities, laboratories, offices and associated residential developments. Vietnam registered USD38.23 billion of foreign investment in 2024, including 3,375 newly licensed projects worth USD19.7 billion and 1,539 projects receiving USD14 billion of additional capital. Processing and manufacturing attracted USD25.58 billion, while realized foreign investment reached USD25.35 billion. At the end of the year, Vietnam had 42,002 valid foreign-invested projects with cumulative registered capital of USD502.8 billion. These industrial projects generate tile installations across washrooms, cafeterias, production-support spaces, administrative buildings and high-traffic service areas, where predictable adhesion and rapid installation are more important than informal mortar preparation. Industrial investment also stimulates surrounding housing and commercial development in Bac Ninh, Hai Phong, Binh Duong and Dong Nai, widening downstream demand for porcelain and homogeneous tile adhesives. The World Bank records Vietnam’s 2024 GDP at USD476.39 billion, GDP per capita at USD4,717.3, and population at 100,987,686. This combination of industrial investment and national economic scale supports wider adoption of specification-based, factory-produced tile adhesive systems.
Market Challenges
Traditional Cement-Sand Mortar and Installation Variability Continue to Constrain Conversion
Traditional cement-sand mortar remains a strong substitute for packaged tile adhesives in Vietnam, especially where installers rely on familiar jobsite practices instead of performance-classified fixing systems. The challenge is significant because installation volumes are large: 937 commercial housing projects with about 403,349 units were under construction in 2024, while 899 commercial housing projects containing 398,124 units remained under construction in the second quarter of 2025. Across this scale, poor substrate preparation, excess mixing water, insufficient adhesive coverage, incorrect trowel selection and excessive open time can produce hollow spots, lippage or tile detachment. The problem becomes more serious with porcelain and large-format tiles because their low absorption leaves less tolerance for poorly transferred mortar. Vietnam’s TCVN 7899 framework formally defines requirements for ceramic-tile adhesives and provides a technical route toward standardized cementitious, dispersion and reaction-resin products, but site practice ultimately determines whether laboratory performance is reproduced in buildings. World Bank data place Vietnam’s 2024 GDP at USD476.39 billion, GDP per capita at USD4,717.3, and population at 100,987,686. The combination of extensive construction activity and varied applicator practices therefore makes contractor training and standardized installation a central market challenge.
Imported Polymer and Chemical Inputs Create Formulation and Supply-Chain Exposure
Vietnamese tile adhesive manufacturers remain exposed to international chemical supply because polymer-modified products require redispersible polymers, cellulose ethers, rheology modifiers and other specialty additives that are linked to imported chemical and plastics streams. Vietnam Customs recorded 5,398,481 tonnes of plastics imports worth USD7.53 billion during the first eight months of 2024, while imported plastic products reached USD5.70 billion during the same period. Although these customs categories are broader than tile-adhesive raw materials, they demonstrate the scale of external polymer dependence across Vietnam’s manufacturing economy. For tile adhesive formulators, inconsistent availability of specialized polymers can influence water retention, open time, slip resistance, deformability and bonding to dense porcelain surfaces. The risk becomes more consequential as construction becomes increasingly specification-driven and factories require consistent batches rather than locally improvised formulations. Vietnam simultaneously carried 42,002 valid foreign-invested projects with USD502.8 billion of registered capital at the end of 2024, increasing expectations for internationally recognizable construction quality. World Bank data record 2024 GDP of USD476.39 billion, GDP per capita of USD4,717.3, and population of 100,987,686. Maintaining reliable imported inputs, local inventory and quality control is therefore critical for organized adhesive suppliers.
Market Opportunities
C2, Flexible and Large-Format Tile Adhesives Can Capture Higher-Specification Applications
Higher-performance tile adhesives offer a strong future opportunity as Vietnam’s housing stock grows and developers adopt larger porcelain and homogeneous tile formats requiring more dependable bond performance. Current construction data already provide the installation base: 403,349 commercial housing units were associated with projects under construction in 2024, while the second quarter of 2025 contained 398,124 units under construction across commercial housing projects. Vietnam’s TCVN 7899 framework, aligned with the ISO 13007 approach to tile-adhesive classification and testing, gives suppliers a technical basis for differentiating normal cementitious products from improved, slip-resistant, extended-open-time and deformable systems. The opportunity extends further through social housing. In the first four months of 2026, 40 social housing projects comprising 36,590 units were launched, while 226 projects totaling 228,725 units were under implementation and 5,426 units had already been completed. Large repetitive developments create favourable conditions for standardized thin-bed installation and contractor training. World Bank data place Vietnam’s 2024 GDP at USD476.39 billion, GDP per capita at USD4,717.3, and population at 100,987,686. These current indicators support future expansion of C2-class, flexible and large-format adhesive systems without relying on projected market statistics.
Tile-on-Tile Renovation and Tier-II Expansion Create a Broader Future Demand Base
Tile-on-tile renovation, rapid-setting adhesives and deeper penetration into secondary cities represent another future growth avenue for Vietnam’s tile adhesive suppliers. The installed residential base is expanding quickly enough to create a larger refurbishment pool: 20,284 social housing units were completed in 2024, while 102,633 social housing units were completed during 2025. By the end of 2025, Vietnam had 698 social housing projects representing around 657,395 units, significantly enlarging the stock of bathrooms, kitchens, floors and communal spaces that will eventually require refurbishment or replacement finishes. In the first four months of 2026 alone, 36,590 units were launched across 40 new social-housing projects, including activity in Hai Phong, Da Nang, Can Tho, Quang Ninh and Dong Nai. This geographic spread creates opportunities outside Ho Chi Minh City and Hanoi for distributors, applicator training and application-specific products. Tile-on-tile systems can reduce demolition and shorten renovation cycles, while rapid-setting formulations can limit disruption in occupied apartments, hotels and retail properties. World Bank data record Vietnam’s 2024 GDP at USD476.39 billion, GDP per capita at USD4,717.3, and population at 100,987,686, providing the current macroeconomic foundation for wider organized adhesive penetration.
Future Outlook
The Vietnam Tile Adhesives Market is forecast to expand at approximately ~X.X% CAGR during 2026–2035, supported by residential construction, industrial FDI, porcelain tile adoption, large-format installation and gradual conversion away from site-mixed cement-sand mortar. Higher-performance C2-class, flexible, rapid-setting and renovation-grade systems are expected to become more important as project specifications and tile dimensions become more demanding.
Vietnam’s housing pipeline provides a substantial demand base. The Ministry of Construction recorded 937 commercial housing projects representing about 403,349 units under construction in the fourth quarter of 2024. Across the full year, 79 commercial housing projects totaling about 38,345 units received new licences, while 69 projects representing about 23,041 units were completed. Each apartment or housing unit creates potential adhesive demand across bathroom walls, kitchen surfaces, floors and common areas.
Major Players
- Sika Vietnam
- Saint-Gobain Weber Vietnam
- MAPEI Vietnam
- LATICRETE Vietnam
- ARDEX Vietnam
- Bostik Vietnam / Arkema
- Fosroc Vietnam / Saint-Gobain
- Master Builders Solutions Vietnam
- KOVA Trading
- Vinkems
- Bestmix Corporation
- INTOC
- Terraco Vietnam
- Davco Vietnam
- Viglacera Building Materials
Key Target Audience
- Tile Adhesive and Dry-Mix Mortar Manufacturers
- Ceramic, Porcelain and Natural Stone Manufacturers
- Property Developers and General Contractors
- Industrial Park Developers and Manufacturing Facility Contractors
- Tile and Sanitaryware Distributors
- Tile, Stone and Interior Installation Contractors
- Investments and Venture Capitalist Firms
- Government and Regulatory Bodies (Ministry of Construction, Commission for Standards Metrology and Quality of Vietnam, Ministry of Science and Technology, Provincial Departments of Construction)
Research Methodology
Step 1: Identification of Key Variables
The initial phase involves constructing an ecosystem map covering cement and polymer suppliers, tile adhesive manufacturers, tile producers, distributors, contractors and applicators. Secondary and proprietary research is used to identify critical variables such as adhesive chemistry, tile dimensions, TCVN/ISO classification, substrate type, regional manufacturing, construction activity and industrial investment.
Step 2: Market Analysis and Construction
Historical information for the Vietnam Tile Adhesives Market is analyzed using top-down and bottom-up approaches. Top-down assessment considers housing activity, construction output and industrial FDI, while bottom-up modelling estimates consumption using installed tile area, adhesive coverage, application thickness, tile type, project category and the share of factory-mixed versus traditional mortar systems.
Step 3: Hypothesis Validation and Expert Consultation
Market hypotheses are validated through computer-assisted telephone interviews with adhesive manufacturers, distributors, tile companies, contractors and applicators. These discussions are used to test assumptions around polymer-modified adhesive adoption, large-format tile installation, regional product preferences, contractor practices, technical standards and distributor-channel structures.
Step 4: Research Synthesis and Final Output
The final phase triangulates Ministry of Construction housing data, foreign-investment statistics, TCVN/ISO standards, manufacturer disclosures and primary research. Bottom-up adhesive-consumption estimates are reconciled against construction and housing activity to produce the final segmentation, competitive landscape, regional assessment and strategic outlook for the Vietnam Tile Adhesives Market.

- Executive Summary
- Research Methodology (Market Definitions and Assumptions, Vietnam Tile Adhesives Market Boundary, Cementitious Adhesive Classification, Dispersion Adhesive Assessment, Reaction-Resin Adhesive Assessment, TCVN 7899 Mapping, ISO 13007 Classification, C1 and C2 Adhesive Assessment, Slip-Resistance Classification, Extended Open-Time Classification, Deformability Assessment, Porcelain Tile Adhesive Assessment, Large-Format Tile Adhesive Assessment, Natural Stone Adhesive Assessment, Exterior Tile Adhesive Assessment, Wet-Area Adhesive Assessment, Tile-on-Tile Adhesive Assessment, Dealer and Distributor Mapping, Tile Applicator Mapping, Project Specification Assessment, Supply-Side Assessment, Demand-Side Assessment, Top-Down Market Sizing, Bottom-Up Market Sizing, Primary Industry Interviews, Housing and Industrial Project Pipeline Assessment, Data Triangulation, Forecasting Framework)

- Definition and Scope
- Evolution of Tile Fixing Practices in Vietnam
- Transition from Site-Mixed Cement-Sand Mortar to Factory-Mixed Tile Adhesives
- Development of Polymer-Modified Cementitious Tile Adhesives
- Evolution of Ceramic and Porcelain Tile Fixing
- Expansion of Homogeneous and Low-Absorption Tile Installation
- Emergence of Large-Format Tile and Porcelain Slab Adhesives
- Development of Tile-on-Tile Renovation Systems

- Growth Drivers (Urban Housing Development, Porcelain Tile Adoption, Homogeneous Tile Consumption, Large-Format Tile Installation, Industrial and Manufacturing Construction, Residential Renovation, Hotel and Resort Construction, Factory-Mixed Mortar Adoption, Applicator Productivity Requirements, Premium Natural Stone Installation, Industrial Park Expansion, Specification-Based Construction)
- Market Challenges (Traditional Cement-Sand Mortar Competition, Low-Cost Local Adhesives, Incorrect Adhesive Selection, Poor Substrate Preparation, Incorrect Mixing Water, Insufficient Adhesive Coverage, Applicator Skill Variation, Large-Format Tile Lippage, Polymer Raw Material Dependence, TCVN and ISO Standard Awareness, Counterfeit and Low-Grade Products, Regional Product Quality Variation)
- Market Opportunities (C2 High-Performance Adhesives, Flexible Large-Format Tile Adhesives, Porcelain Slab Adhesives, Tile-on-Tile Renovation Adhesives, Epoxy Tile and Stone Systems, Exterior Façade Adhesives, Rapid-Setting Adhesives, Low-Dust Adhesives, Natural Stone Adhesives, Swimming Pool Adhesives, Contractor Training and Certification, Tier-II City Expansion)
- Market Trends (Polymer-Modified Thin-Bed Adhesives, C2 Adhesive Adoption, Flexible Large-Format Mortars, Porcelain Slab Installation, Extended Open-Time Systems, Slip-Resistant Adhesives, Tile-on-Tile Systems, White Adhesives, Epoxy Systems, Rapid-Setting Mortars, Low-Dust Formulations, Applicator Training)
- Government Regulations and Standards (TCVN 7899 Tile Adhesive Requirements, ISO 13007 Classification, Adhesive Test Methods, Tensile Adhesion Strength, Open Time, Slip Resistance, Deformability, Ministry of Construction Material Requirements, Product Conformity Requirements, Chemical Labelling and Occupational Safety Requirements)
- SWOT Analysis
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Stakeholder Ecosystem

- By Market Value (2020-2025)
- By Tile Adhesive Consumption Volume (2020-2025)
- By Cementitious Tile Adhesive Consumption (2020-2025)
- By Polymer-Modified Tile Adhesive Consumption (2020-2025)
- By Flexible Tile Adhesive Consumption (2020-2025)
- By Large-Format Tile Adhesive Consumption (2020-2025)
- By Epoxy Tile Adhesive Consumption (2020-2025)

- By Adhesive Technology (In Value %)
Standard Cementitious Tile Adhesives
Polymer-Modified Cementitious Tile Adhesives
Flexible Cementitious Tile Adhesives
Highly Deformable Tile Adhesives
Large-Format Tile Adhesives
Rapid-Setting Tile Adhesives
Tile-on-Tile Adhesives
Dispersion Tile Adhesives
Epoxy and Reaction-Resin Adhesives
Ready-to-Use Tile Adhesives
White Tile and Stone Adhesives
Specialty High-Bond Adhesives - By Tile and Stone Type (In Value %)
Ceramic Tiles
Porcelain Tiles
Homogeneous Tiles
Glazed Porcelain Tiles
Large-Format Tiles
Porcelain Slabs
Natural Stone
Marble
Granite
Mosaic Tiles
Glass Tiles
Engineered Stone
Existing Tile Surfaces - By Application (In Value %)
Internal Floor Tile Installation
Internal Wall Tile Installation
Bathroom and Wet-Area Installation
Kitchen Tile Installation
Large-Format Tile Installation
Tile-on-Tile Installation
Exterior Wall Tile Installation
Façade Tile Installation
Swimming Pool Tile Installation
Natural Stone Installation
Commercial Flooring Installation
Industrial Facility Tile Installation
Hotel and Resort Tile Installation - By Performance Classification (In Value %)
C1 Normal Cementitious Adhesives
C2 Improved Cementitious Adhesives
D-Class Dispersion Adhesives
R-Class Reaction-Resin Adhesives
Slip-Resistant Adhesives
Extended Open-Time Adhesives
Fast-Setting Adhesives
Deformable Adhesives
Highly Deformable Adhesives
Water-Resistant Adhesives
Heat-Resistant Adhesives
Heavy-Tile and Large-Format Adhesives - By Construction Activity (In Value %)
New Residential Construction
New Commercial Construction
Industrial and Manufacturing Construction
Hospitality Construction
Institutional Construction
Residential Renovation
Commercial Refurbishment
Bathroom Renovation
Tile Replacement
Tile-on-Tile Renovation
Industrial Facility Upgrade - By Building Type (In Value %)
High-Rise Apartments
Mid-Rise Residential Buildings
Individual Houses and Villas
Commercial Offices
Shopping Malls and Retail Buildings
Hotels and Resorts
Hospitals and Healthcare Facilities
Educational Buildings
Electronics and Semiconductor Facilities
Industrial Factories
Warehouses and Logistics Buildings
Government Buildings
Mixed-Use Developments

- Market Share of Major Players (By Vietnam Revenue, Tile Adhesive Volume, Polymer-Modified Adhesive Portfolio, C2 Adhesive Portfolio, Large-Format Adhesive Portfolio, Porcelain Tile Exposure, Natural Stone Exposure, Exterior Application Exposure, Residential Construction Exposure, Industrial Construction Exposure, Manufacturing Footprint, Distributor Network, Applicator Network, Project Specification Presence, Technical Support)
- Cross Comparison Parameters (Tile and Stone Adhesive Portfolio Breadth, TCVN 7899 and ISO 13007 Performance Capability, Large-Format Porcelain and Slab Adhesive Capability, Exterior Wet-Area Tile-on-Tile and Natural Stone Capability, Vietnam Dry-Mix Manufacturing and Supply Footprint, Tile Dealer Distributor and Applicator Network Reach, Flexible Rapid-Setting Low-Dust and Premium Polymer Technology Capability, Technical Specification Applicator Training and Jobsite Support Capability)
- SWOT Analysis of Major Players (Technology Portfolio, Manufacturing, Distribution, Contractor Reach, Brand Positioning)
- Major Companies
Sika Vietnam
Saint-Gobain Weber Vietnam
MAPEI Vietnam
LATICRETE Vietnam
ARDEX Vietnam
Bostik Vietnam / Arkema
Fosroc Vietnam / Saint-Gobain
Master Builders Solutions Vietnam
KOVA Trading
Vinkems
Bestmix Corporation
INTOC
Terraco Vietnam
Davco Vietnam
Viglacera Building Materials

- Property Developer Requirement Assessment
- Tile Contractor Requirement Assessment
- Applicator Requirement Assessment
- General Contractor Requirement Assessment
- Interior Fit-Out Contractor Requirement Assessment
- Industrial Contractor Requirement Assessment
- Architect and Specification Requirement Assessment
- Tile Manufacturer Partnership Assessment
- Tile Dealer Requirement Assessment
- Construction Chemical Distributor Requirement Assessment
- Large-Format Tile Installer Requirement Assessment
- TCVN / ISO Compliance Requirement Assessment
- Technical Site Support Requirement Assessment
- Applicator Training Requirement Assessment

- By Market Value (2026-2035)
- By Tile Adhesive Consumption Volume (2026-2035)
- By Cementitious Tile Adhesive Consumption (2026-2035)
- By Polymer-Modified Tile Adhesive Consumption (2026-2035)
- By Flexible Tile Adhesive Consumption (2026-2035)
- By Large-Format Tile Adhesive Consumption (2026-2035)
- By Epoxy Tile Adhesive Consumption (2026-2035)


 Request a Sample
 Ask for Customization
 Get a Quote
 Enquire Now
